How to Actually Build a Performance Measurement System That Doesn't Break in Three Months
Most companies build their management accounting performance measurement system wrong from the start. They pick KPIs based on what looks good in a board presentation instead of what actually drives behavior on the shop floor or in the sales team. I've watched this happen repeatedly. You design a dashboard, everyone gets excited, and then within six months the numbers stop being useful because they incentivize the wrong thing or simply don't reflect reality anymore. The first step is not picking metrics. It's mapping out the causal chain between what your people do day-to-day and the financial outcome the business actually cares about. Start with the revenue or cost driver you want to move, then work backward through every layer of operation until you hit something someone can touch. If you can't trace the link without three intermediate assumptions, your metric is too far removed from actual work to be useful for management accounting purposes.Setting Up Performance Measurement In Management Accounting
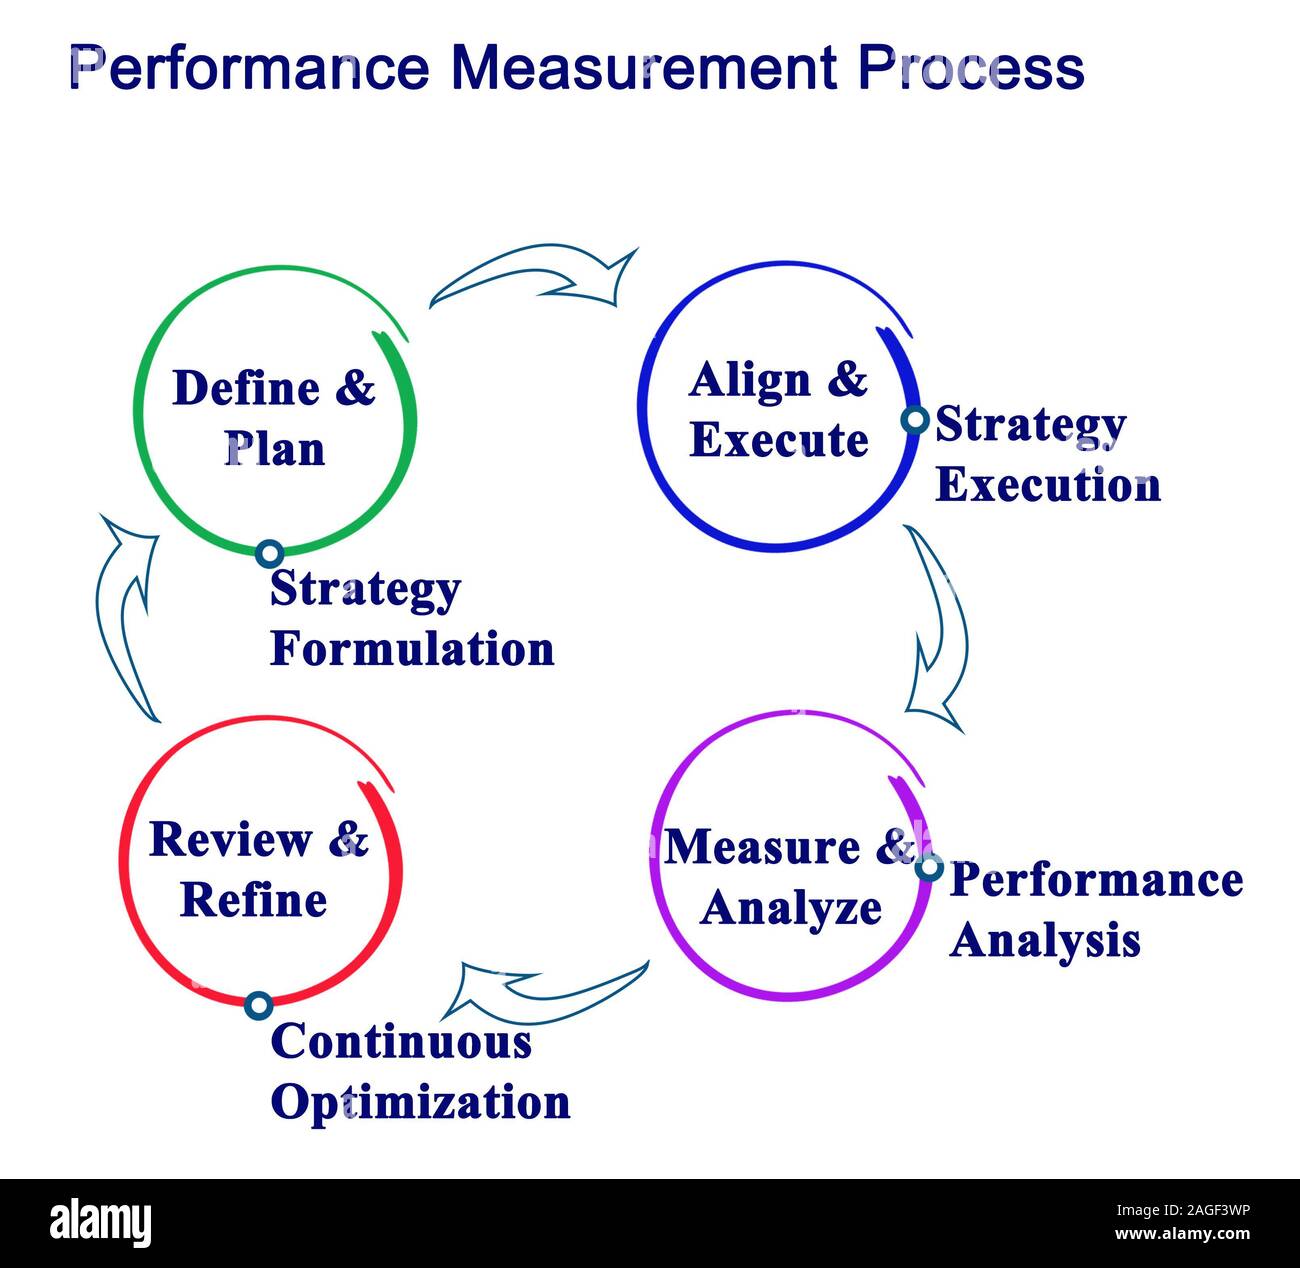
Here's the practical process. I work through this with my team every time we rebuild a division's reporting structure. First, identify the decision points. Who needs to make what decision, and how often? If a plant manager reviews production waste monthly but the data comes out with a forty-five-day lag, the metric is useless for their job. Speed matters more than precision at the operational level. I once spent three weeks building a perfect variance analysis model for our European distribution center only to realize nobody was actually using it because the controller couldn't get the numbers from the ERP before the next quarter started. We switched to a simplified weekly snapshot from a different data source and the adoption rate went from zero to basically mandatory. Second, define the metric with enough granularity that it can't be gamed but simple enough that a frontline supervisor understands it in five seconds. "Efficiency" is a terrible metric. "Line changeover time measured from last good part to first conforming part of next run" is a metric you can actually manage with. Third, establish the baseline before you implement anything. I can't stress this enough. Every time I've seen a performance measurement system fail, it's because they started tracking against a target that had no historical reference point. You need at least three months of actual data before you set a floor or ceiling on any KPI. Otherwise you're either setting an impossible standard that demoralizes people or a trivial one that nobody cares about. Fourth, build in feedback loops. The system needs to tell someone when they're off track fast enough that they can adjust. If the metric only surfaces in a quarterly report, it's a lagging indicator at best. Pair every lagging metric with a leading one that gives early warning.A common mistake is stacking too many metrics on one dashboard. I've seen finance teams create scorecards with forty-two indicators. Nobody reads them. Pick the top five to seven metrics per role, no exceptions. If everything is a priority, nothing is. The cognitive load on the person using the data matters as much as the data itself.
Another nuance people miss is the relationship between variance reporting and behavior. Standard costing variance analysis sounds solid on paper. In practice, it often creates a blame game where department heads hide problems rather than expose them. I switched our production team to a forward-looking throughput accounting approach instead of traditional variance reporting. Instead of reporting favorable and unfavorable variances against a standard, we measured throughput, inventory, and operating expense in real time. It took about two weeks of adjustment for the team to think in those terms, but once they did, the number of "accidents" and write-offs dropped noticeably because people stopped optimizing for variance reduction and started optimizing for actual flow. Segment reporting creates its own distortion. When you measure profitability by product line or customer segment, you inevitably allocate shared costs in arbitrary ways. The allocation base you choose—revenue, headcount, square footage, machine hours—will completely reshape your picture of which segments are actually profitable. I learned this the hard way when we discovered our "least profitable" customer segment became our second most profitable once we stopped allocating corporate overhead using revenue-based proportionality and switched to activity-driven allocation. The segment hadn't changed. Our view of it had. Non-financial metrics are important but tricky. Cycle time, defect rate, employee turnover—all valid. The problem is they don't always connect cleanly to financial outcomes, which makes it hard to justify the effort of tracking them to people who only speak P&L. The workaround is to tie each non-financial metric to a specific financial impact through a documented formula. "We track on-time delivery because each percentage point below our 96 percent target correlates to approximately forty thousand dollars in annual revenue at risk from contract penalties." That sentence does more for metric adoption than any persuasive argument I could make.
What I Wish I'd Known Before Starting
The single biggest factor in whether a performance measurement system works is not the methodology. It's whether the people using it trust the data. If a single incident of inaccurate reporting goes unaddressed, you lose the entire system. I once had a region's controller deliberately inflate a quality metric for two months to hit a bonus target. We caught it, but the damage to credibility with the rest of the organization lasted over a year. Implementing a basic sanity check—random sampling of reported data against source systems—cost us maybe two hours per month and prevented this kind of thing from going undetected.You also need to accept that your system will go stale. Industry dynamics change, products get retired, new competitors appear. A well-run performance measurement review should happen at least annually, ideally with someone not embedded in the current operations providing fresh perspective. What looked like the right five metrics two years ago may be noise now. The whole exercise of Performance Measurement In Management Accounting is ultimately about creating visibility into what matters so decisions can be made faster and better. That sounds straightforward until you try to execute it. The gap between theory and practice is where most of this work actually happens—in the messy details of data availability, human behavior, and organizational politics. Get the basics right, keep it simple, maintain trust in the numbers, and you'll be further ahead than most companies that spend millions on fancy ERP modules nobody uses.
Get the Full Details