The Actual Differences Between Writing a Personal Check and a Business Check
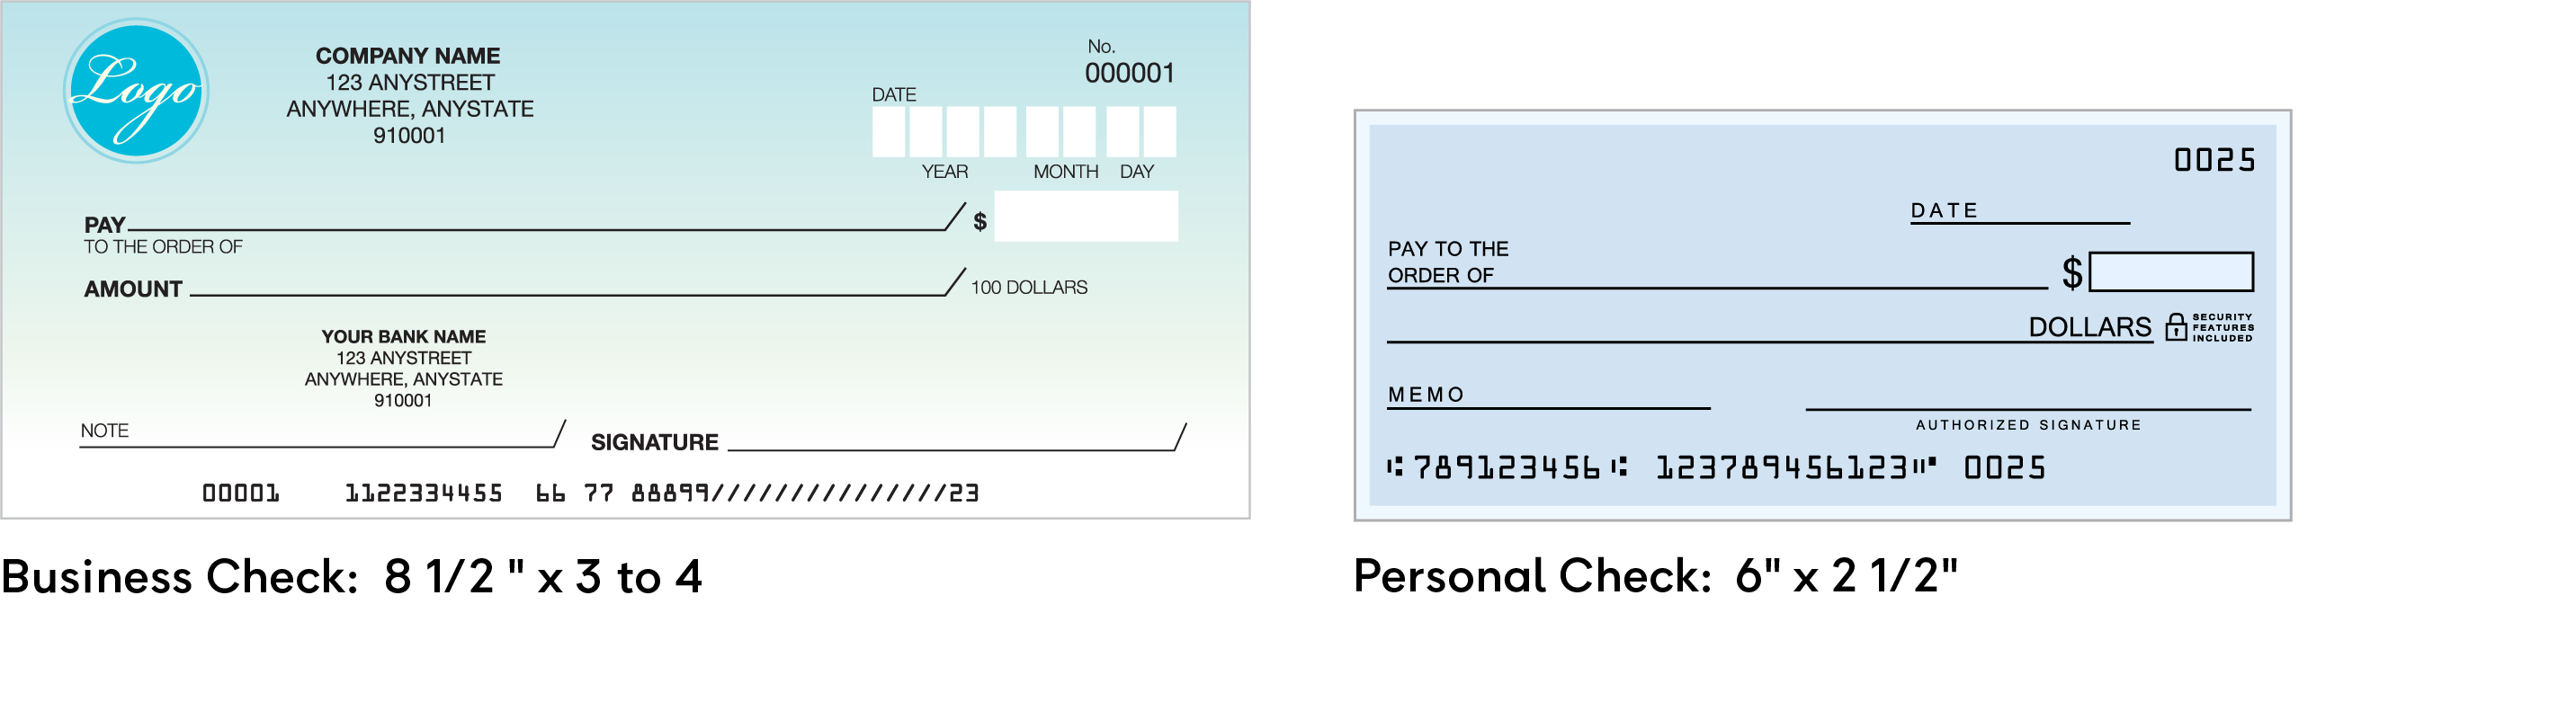
I get this question a lot in thread form, and honestly it's usually coming from someone who either just started freelancing or got confused when a vendor bounced back a payment they sent to their sole proprietorship. The core mechanics are identical. Same ABA routing number on the bottom, same MICR line, same paper size, same deposit process. But there are structural and compliance differences that matter if you're actually trying to run a business and not accidentally commingle funds or trigger an audit flag. When you write a personal check, you're drawing against a personal checking account. The account holder is an individual. When you write a business check, you're drawing against a business checking account, and that account can be structured as a sole proprietorship, LLC, corporation, or partnership. The bank account name has to match the check name exactly. That's not a suggestion. It's how the clearing system validates it.
Personal Check Vs Business Check: What Actually Changes at the Banking Level
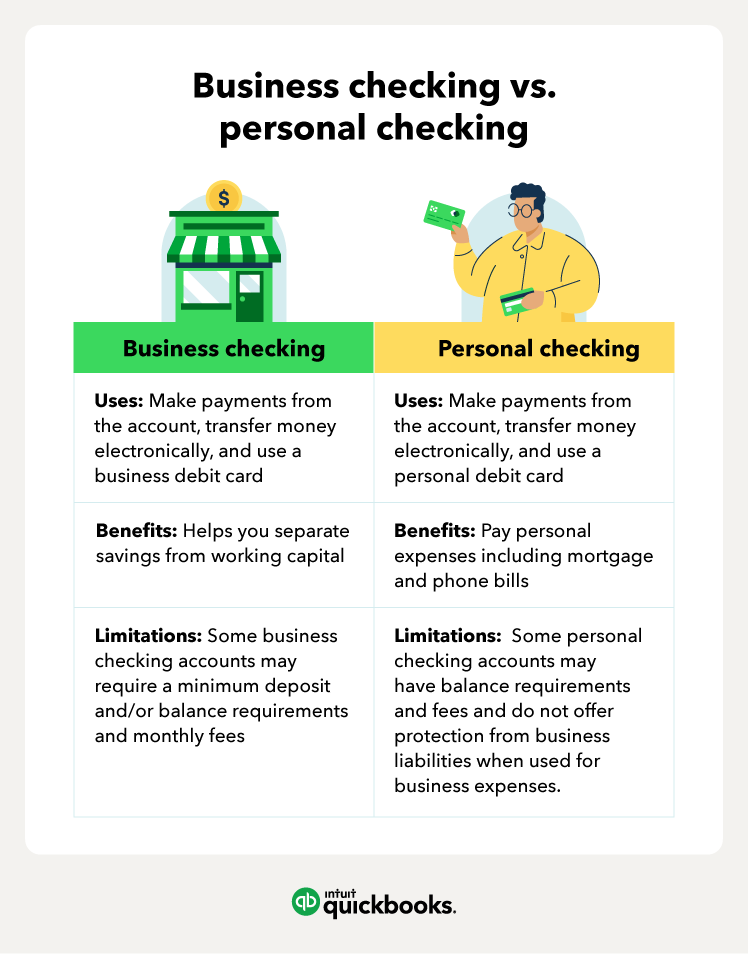
Here's what I've seen trip people up over the years. The check itself doesn't carry a label that says "personal" or "business." The only thing distinguishing them is the account it's drawn against. So if you write a check from your Wells Fargo account registered to "John Smith" on a personal checking, that's a personal check regardless of whether you wrote it to buy office supplies. If you write from an account registered to "Smith Consulting LLC," that's a business check regardless of what you used it for. The real difference shows up in three areas: account structure, compliance expectations, and what happens when something goes wrong. Account structure: Business accounts require formation documents on file. You can't just walk into a bank and open one. You'll need your EIN, Articles of Organization or Incorporation, and usually a resolution authorizing you to operate the account. Personal accounts need nothing more than a government ID and Social Security number. This is why a lot of solo operators skip business accounts initially and then regret it when their first client payment gets deposited into a personal account and suddenly looks like unreported income on their tax return.
Compliance: Business accounts are subject to different monitoring thresholds. The Bank Secrecy Act applies to both, but business accounts typically get flagged at lower transaction volumes because the patterns are different. A personal account moving $50,000 in a month might raise an eyebrow depending on your history. A business account doing the same might trigger a routine CTR review if it's structured a certain way. This isn't scary, it's just procedural. But if you're running a business through a personal account, you're essentially putting all your revenue through a filter that wasn't designed for that volume. What happens when things go wrong: This is the part nobody talks about. If you write a bad check from a personal account, it's a civil matter between you and the payee, possibly a criminal matter if intent can be proven. If you write a bad check from a business account, you now have corporate liability exposure on top of personal liability. For an LLC or corporation, the veil can be pierced if you're using business accounts carelessly. For sole proprietors, there's no veil to begin with, so the distinction is mostly about bookkeeping cleanliness. I had a specific case last year that illustrates why this matters. A client of mine runs a small contracting business as a sole prop. He was paying his subcontractors via personal checks written from his business account, but he'd been labeling them inconsistently in his ledger. One subs got checks marked "payment," others got "refund," and one got left blank. The subs who received "refund" labels came back later claiming they were being double-charged or that there was a billing error. His bank statement didn't show the check amounts clearly enough to cross-reference with his invoices because he'd been using a cheap check printer that omitted the memo field on the bank's side. He lost about three weeks sorting it out with two subs and had to pull his original contracts to prove what each payment was for. The workaround was switching to online bill pay through his bank with mandatory memo fields, which costs him nothing extra and forces a paper trail that actually matches the check image the bank keeps.
Get the Full Details

Here's a counter-intuitive point that most people miss. A business check doesn't automatically give you more credibility with vendors or clients. In fact, some smaller suppliers prefer personal checks from sole proprietors because they find it easier to verify the source. A check from "Doe Enterprises LLC" raises questions about whether that entity actually exists or is just a name on a bank account. A check from "Mike Doe" is transparent. This only matters if you're dealing with vendors who do manual verification, which is still a lot of small businesses. Large corporations will reject a personal check from a business vendor anyway because their accounts payable departments require vendor W-9 forms on file, and those forms have to match the payment source. Another thing people get wrong about the Personal Check Vs Business Check comparison is the deposit side. You can deposit a business check into a personal account, and you can deposit a personal check into a business account. The bank will process it either way. But if you consistently deposit business income into a personal account, you're creating a commingling problem that becomes a nightmare during tax season. The IRS doesn't care about your check types. They care about where the money went. And if you're self-employed, every dollar deposited into a personal account looks like personal income unless you can trace it back to business activity with documentation. That tracing work takes time. I estimate it adds 40 to 60 hours per year for someone doing a few hundred transactions, versus maybe 5 to 10 hours if you keep everything in a dedicated business account with clear memo fields. The practical answer depends on your situation. If you're a sole proprietor making under 50 transactions a year and your client base is mostly individuals who pay by personal check, you can probably manage with a personal account and just be disciplined about your bookkeeping. If you're incorporated, have employees, or process more than 100 transactions annually, a business checking account is basically mandatory. Not because of any legal requirement in most cases, but because the alternative is spending far more time reconciling accounts than you're saving by not paying the minimum monthly fee most banks charge.
One last thing that catches people off guard. Some banks now offer free business checking accounts with no minimum balance requirement, especially online-only banks. So the old excuse of "the fees are too high" doesn't hold up like it used to. If you're still running a business entirely through a personal account because you don't want to deal with a separate bank relationship, you're probably paying a higher cost in time and risk than the monthly fee would have been.