Working Through Personal Finance Activity Sheet Answers Chapter 8
I run into this stuff constantly from students who are stuck on Chapter 8. The chapter typically covers credit scores, credit reports, and how borrowing decisions actually affect your financial life long-term. It sounds straightforward on paper but the activity questions throw people off because they ask you to calculate real scenarios, not just define terms. Here is how I actually approach these worksheets. Most of Chapter 8 boils down to three things: understanding what a credit score is, knowing what goes into it, and working through some math on interest and payments. The tricky part is usually the calculation problems where you have to figure out total interest paid over time or compare two different loan options. I remember one student who was completely stuck on a problem asking them to compare a 3-year loan versus a 5-year loan for a $12,000 car at 6.5% interest. They kept getting confused between monthly payment and total cost. The workaround was simple: I had them build a mini amortization table by hand for just the first three months of each loan. Once they saw that the 5-year loan had a lower monthly payment but you pay nearly twice as much in total interest, the concept clicked. Without writing it out, the numbers just stayed abstract and meaningless.
For the definition questions, stop treating them like vocabulary quizzes. A credit score is not just a number between 300 and 850. It is a risk assessment tool that lenders use in milliseconds to decide whether to approve you and at what rate. The five factors that matter are payment history, amounts owed, length of credit history, new credit, and credit mix. Payment history alone makes up about 35 percent. That is why even one missed payment can drop your score 50 to 100 points depending on where you started. The credit report section trips people up too. Your credit report and your credit score are two different things. The report is the raw data. The score is a mathematical reading of that data. You can pull your free credit report from annualcreditreport.com once a year from each of the three bureaus. That is Equifax, Experian, and TransUnion. Nothing stops you from doing it all at once. I have seen people wait a full year thinking they could only get one report per year across the board. That is not how it works. One thing most textbooks gloss over is the difference between a hard inquiry and a soft inquiry. A hard inquiry happens when a lender checks your credit as part of a formal application. It can knock a few points off your score and stays on your report for two years, though it only affects your score for the first 12 months. A soft inquiry is you checking your own report or a pre-approved offer. It does not touch your score at all. I had a caller once who was frustrated that her score dropped after she applied for a credit card and then immediately changed her mind and did not use it. The damage was already done. The inquiry was recorded regardless of whether she accepted the card.
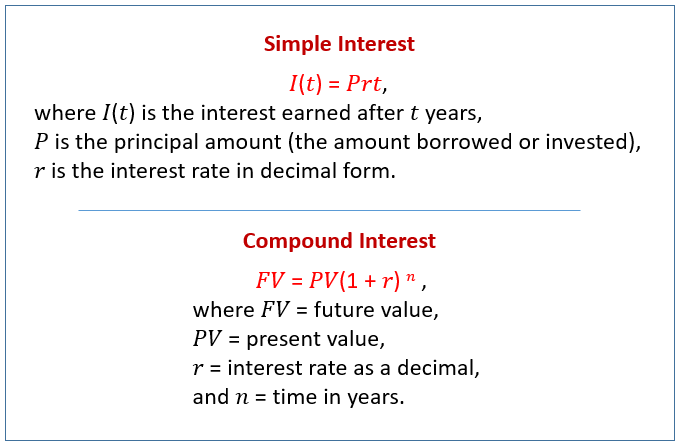
When you get to the interest calculations, remember that most of these problems assume simple interest or standard amortizing loans. If the problem mentions APR, that is your annual percentage rate and it includes not just the interest but sometimes fees too. For a straightforward monthly payment calculation, the formula is M equals P times r times (1 plus r) to the power of n, all divided by (1 plus r) to the power of n minus 1. P is the principal, r is your monthly interest rate, and n is the total number of payments. It looks worse than it is. Plug in the numbers and your calculator does the rest. A common pitfall on these sheets is confusing annual interest with monthly interest. If a car loan is 6.5% annual, you divide by 12 to get the monthly rate of about 0.5417 percent. Using 6.5 directly in the formula will give you a wildly wrong answer. I have caught this in more answer keys than I care to admit. Double check that conversion step before you move on. Another counter-intuitive detail: paying extra toward principal never hurts, but it does not always help as much as you think if you are early in the loan term. In the first few years of a mortgage or auto loan, the vast majority of your monthly payment goes toward interest, not principal. Throwing an extra $100 at the start of a 5-year car loan saves you more than throwing the same amount at year four. The schedule is front-loaded with interest by design. This is true for almost any amortizing loan except interest-only arrangements, which are rare for consumers anyway.
If your activity sheet includes a question about rebuilding credit after a bad event, the realistic answer is not dramatic. It is consistent, on-time payments over 12 to 24 months. A single missed payment fades from major impact after two years. A bankruptcy stays for up to ten. No app or scheme changes that. Secured credit cards exist for exactly this purpose, and they work if you treat them like a regular debit card and pay the balance every month. For the specific answer key questions, here is the general direction most worksheets expect. When asked what lowers a credit score, the strongest answer is missing payments and maxing out credit cards. When asked what raises it, the strongest answer is paying on time and keeping utilization below 30 percent. Utilization is the ratio of your balances to your limits. If you have a $1,000 limit and a $400 balance, your utilization is 40 percent, which is above the threshold most scoring models prefer. Paying it down to $300 drops you to 30 percent and can add points back quickly. Some chapters also ask about co-signers. A co-signer takes on equal legal responsibility for the debt. If the primary borrower misses a payment, the co-signer's credit takes the hit just the same. Schools sometimes frame this as a helpful option for teens or young adults with no history. In practice it is risky. I know people who co-signed student loans for relatives and watched their own ability to rent an apartment get blocked because the debt showed up on their report as theirs too.
If you are looking for the official answer key, check with your instructor first. Many teachers distribute it directly or post it on the class learning management system. Some textbooks have answer sections in the back of the book. Be careful with random websites that claim to have the full answers. A lot of them are outdated, mismatched to edition, or just copy-pasted without checking the math. One wrong number in an answer key and the whole rest of your work looks wrong when it was actually fine. The most useful strategy for Chapter 8 is to redo every calculation problem twice. First time on your own. Second time checking against whatever solution you have. If the answers do not match, figure out exactly where you diverged. That divergence point is usually a rate conversion error or a calculator entry mistake. Both are fixable once you spot them. For the conceptual questions, write answers in your own words instead of copying definitions verbatim. Teachers can tell. They also retain more when you have to translate the textbook language into something you would actually say to someone else. Explain credit scores to an imaginary friend who has never heard of banking. If you can do that plainly, you understand the material well enough to pass the worksheet and the test that follows.
One last thing about credit report errors. They are surprisingly common. I have personally called three bureaus to dispute an account that showed up on my report that was not mine. It turned out to be a clerical mix-up with someone who shared my name and part of my Social Security number. The dispute process took about three weeks and the entry was removed. These errors show up on activity sheets too, usually in a question about what to do when you find inaccurate information. The correct practical answer is to file a dispute with the bureau that issued the report and with the creditor who supplied the data. Doing both speeds things up. Chapter 8 wraps up a lot of foundational material that everything else in personal finance builds on. Budgeting means nothing if you cannot borrow reasonably. Investing gets harder fast if your credit is in the basement. Tackle the sheet while the concepts are fresh instead of letting them sit until the night before the quiz. The math is not hard. The vocabulary is the only real barrier, and that clears up once you stop treating it like a foreign language and start treating it like a set of tools you will actually use.
