Working With Personal Finance Activity Worksheets Actually Makes Sense
I spent about three years managing financial literacy materials for a community college program, and the most common problem I saw wasn't that people couldn't do the math. It was that they filled out the worksheets without understanding what the numbers were supposed to represent. The gap between entering data and understanding it is where most people get stuck. A personal finance activity worksheet is essentially a structured exercise designed to walk you through a specific financial concept—budgeting, compound interest, debt payoff, credit utilization. The answer key at the end isn't meant to be a shortcut. It's meant to help you identify where your logic broke down if your results don't match. That distinction matters more than you'd think.
Where to Find Reliable Personal Finance Activity Worksheet Answers
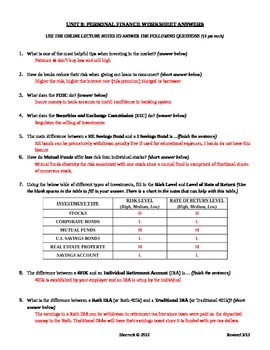
The safest sources are your course textbook's companion website, your instructor's learning management system, or published educational workbooks from recognized financial literacy organizations. The Kiplinger Educational Programs and the Council for Economic Education both publish answer keys alongside their materials. Avoid random PDF repositories that aggregate worksheets without attribution—you'll encounter outdated tax brackets, incorrect compound interest formulas, and worksheets with internal calculation errors that will throw off your work for no reason. I ran into this exact problem with a debt snowball worksheet that used an incorrect allocation formula for partial payments. The answer key showed $47.32 going toward the lowest-balance card, but recalculating it manually with standard debt avalanche methodology gave $51.89. The source worksheet had a rounding error baked into the template itself. I flagged it to my department and we switched to using the revised version the publisher had quietly updated two weeks later. Always verify the numbers yourself before assuming the key is correct.
How to Actually Use the Answer Keys Without Cheating Yourself
The productive workflow is straightforward. Complete the entire worksheet on your own first, even if you're unsure about a few steps. Then compare your answers line by line against the key. When you find a discrepancy, don't just copy the correct number. Trace back through your calculation to find where the divergence happened. That's where the actual learning occurs. For budgeting worksheets, the most common error I see is people forgetting to include irregular expenses. A worksheet might ask you to calculate a monthly surplus, and the student will plug in their paycheck and rent and utilities and declare a $400 surplus. Then they get surprised when it's gone by mid-month because they never budgeted for car registration, annual subscriptions, or quarterly insurance payments. The answer key will show a different number, and that difference is usually coming from exactly that kind of overlooked category. Compound interest worksheets trip people up on the compounding frequency. The formula A = P(1 + r/n)^(nt) looks simple, but if you use n=12 for monthly compounding and then also make the rate monthly without adjusting the exponent, you'll get a materially wrong answer. The answer key will flag this quickly. I've seen students waste 20 minutes rechecking their arithmetic when the real problem was a misapplied variable.
Get the Full Details
Personal Finance Activity Worksheet Answers for Debt Management
Debt payoff worksheets are where the answer keys become most useful because there are genuinely two valid approaches—the debt snowball and the debt avalanche—and they produce different results. A good worksheet will ask you to calculate both and compare the total interest paid. The avalanche method typically saves between 12 and 18 percent in total interest compared to the snowball for a standard consumer debt profile, but the psychological win rate of the snowball is higher because you eliminate accounts faster. Here's a counter-intuitive point that most beginner worksheets don't address: debt payoff calculations that ignore the tax implications of certain deductions are slightly incomplete. If you're paying down a mortgage while also claiming the standard deduction, the marginal tax benefit changes. For most people this is a rounding-level difference, but on larger balances over longer timeframes it shifts the optimal strategy enough that you should be aware of it. The answer key won't mention this. It's something you pick up from actually doing the work multiple times.
Common Pitfalls That Make Worksheets Feel Pointless
The biggest issue I encountered was that many published worksheets assume a single income, fixed expenses, and zero unexpected events. Real financial lives don't work that way. A student filling out a monthly budget worksheet with perfect numbers all month long will feel confident until their first real-month experience hits—car repair, reduced hours at work, an unexpected medical bill—and suddenly the worksheet model feels irrelevant. The workaround is to stress-test your worksheet answers. Take your calculated monthly surplus and subtract 10 percent as a buffer for variability. See if you still come out positive. If you don't, your budget is too tight to be sustainable regardless of what the clean numbers say. This is the kind of thing that separate answer keys won't teach you. It comes from running the same worksheet through edge cases until you understand its limits. Another pitfall is using worksheets with stale tax tables. The IRS adjusts brackets annually, and some workbook publishers update slowly. If you're working with a 2019 tax bracket table in a 2025 context, your effective tax rate calculations will be off by a noticeable margin. Cross-reference any tax-related worksheet answers with current IRS Publication 15-T or the relevant revenue authority for your country. It takes two extra minutes and prevents you from building financial plans on incorrect assumptions.
The honest limitation of personal finance activity worksheets is that they're diagnostic tools, not planning tools. They tell you whether you understand a concept. They don't replace a full financial plan built around your actual numbers, actual obligations, and actual goals. I've had people memorize worksheet answers and then fail to apply the same logic to their real budgets because the worksheet variables were clean and their real variables weren't. That disconnect is normal. It's also fixable once you recognize it. If you're looking for downloadable materials, start with your textbook publisher's resource page. Second choice is the OER (open educational resource) platforms like OpenStax or the Financial Literacy and Education Initiative materials. Both provide free worksheets and answer keys that are at least as accurate as paid products and frequently better maintained because the revision process is faster.