What You're Actually Looking For
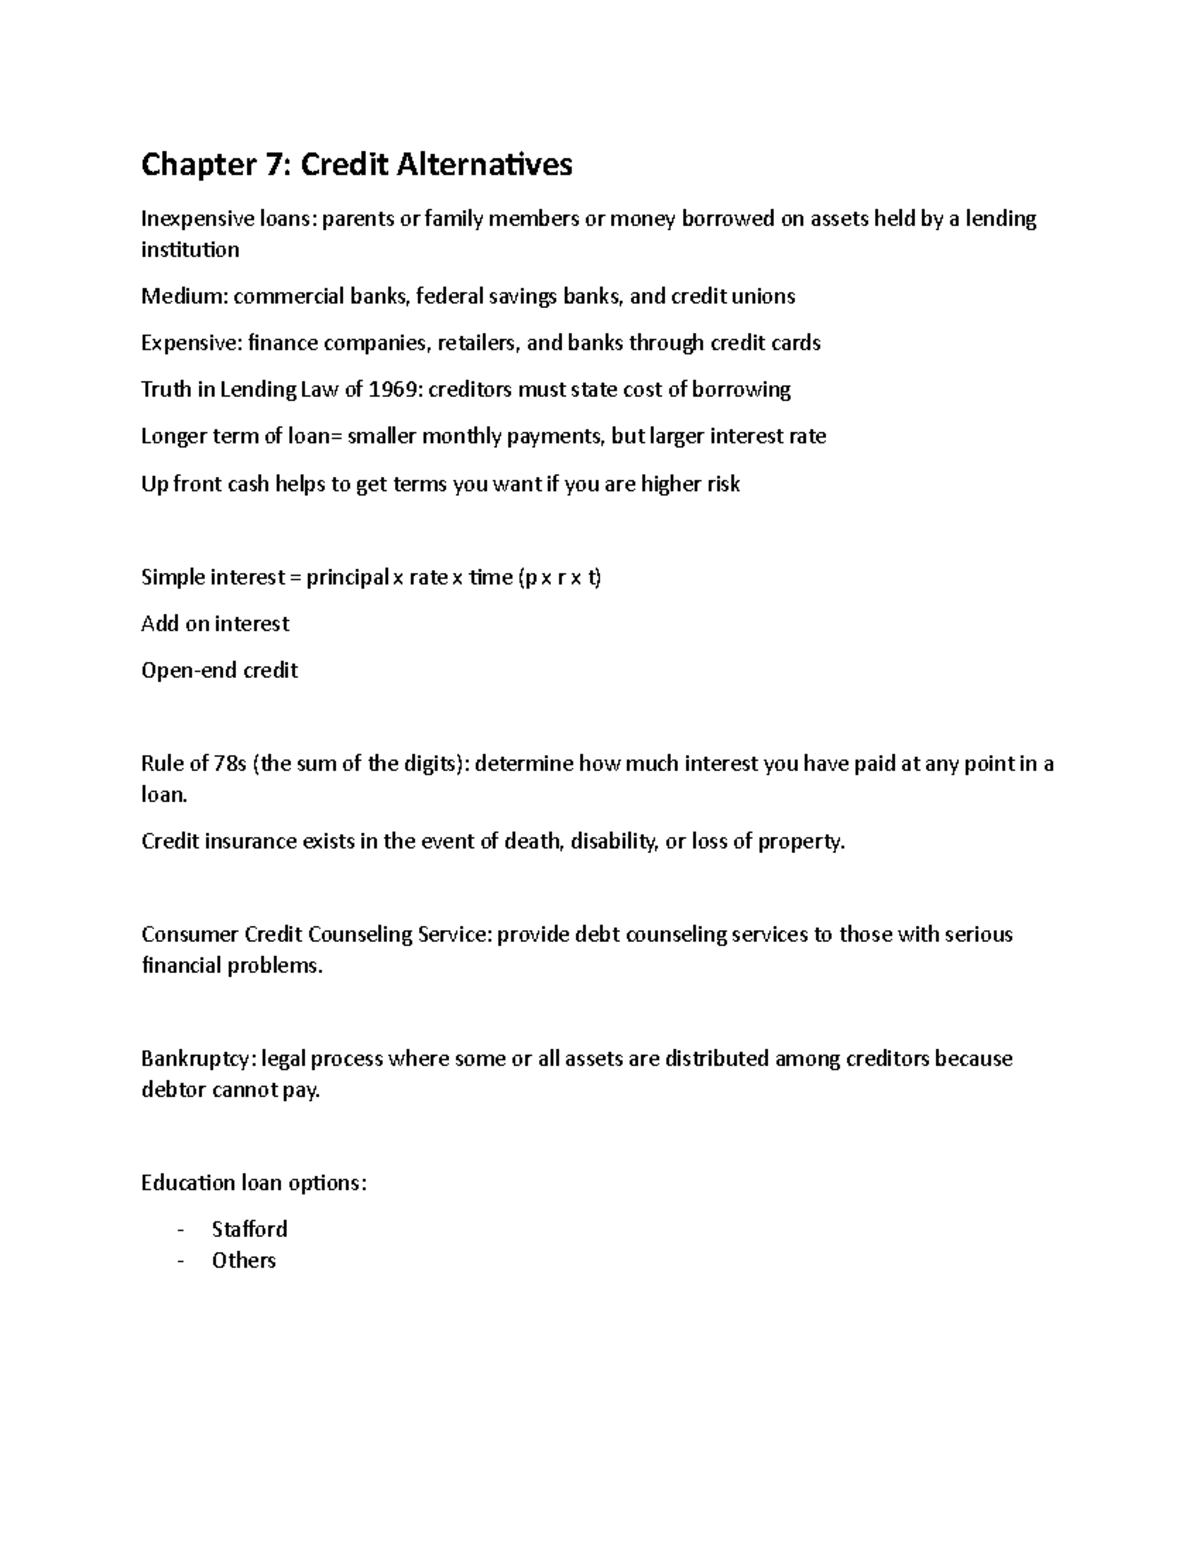
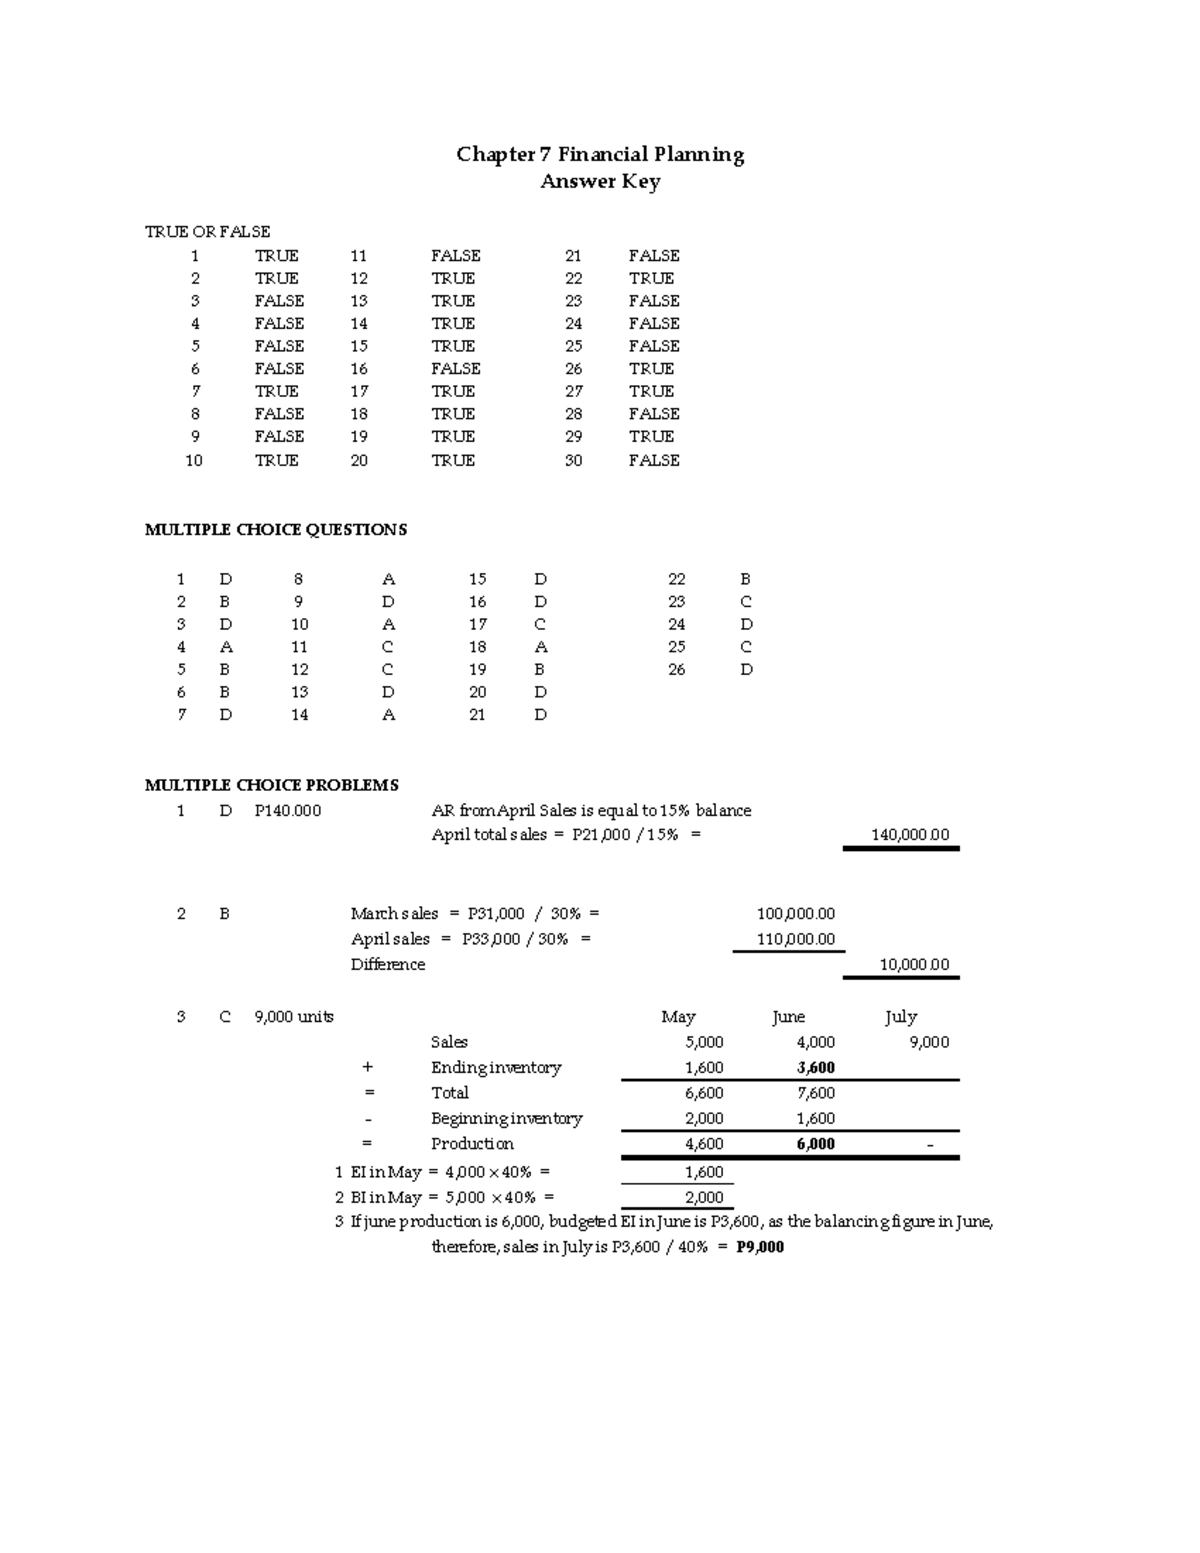
The Money in Review Chapter 7 answer key covers personal finance fundamentals like budgeting, credit scores, debt management, and basic financial planning. Most students end up searching for it because the textbook uses real-world scenarios that aren't always obvious without working through the practice problems first. I spent a couple years grading intro personal finance courses before moving into actual financial advising, and the Chapter 7 material is where things start to get practical. The answer key isn't just about matching letters to questions. It's about understanding why certain financial decisions make sense in specific situations.
Personal Finance Money In Review Chapter 7 Answer Key
The core topics in this chapter typically include understanding your net worth, building a realistic budget, managing different types of debt, and establishing emergency savings. If you're working through the chapter on your own, the answer key becomes useful mainly for checking your reasoning, not just copying responses. Here's something most answer keys won't tell you: the budgeting questions in Chapter 7 often have multiple correct approaches depending on your starting income and expenses. I had a student once who got marked wrong on a problem because her spending allocation differed from the answer key by about eight percent. She was technically more accurate than the textbook model, but the grading rubric didn't account for that. The workaround was walking the professor through her actual numbers and showing the calculation steps. That actually counted for more than the final answer in most cases.
How the Answer Key Breaks Down
Multiple choice questions tend to focus on definitions and basic calculations. Short answer sections ask you to apply those definitions to concrete scenarios. The problem sets at the end are where most people get stuck, and where the answer key shows its real value. The debt-to-income ratio questions are particularly important. These require you to take total monthly debt payments and divide them by gross monthly income. Students frequently mistake net income for gross income here, which throws off every subsequent calculation. The answer key will show you the correct approach if you track which income figure they're using. Credit score questions usually involve understanding how different factors weigh into the score. Payment history matters most, followed by amounts owed, length of credit history, new credit, and credit mix. This order matters more than most students realize when answering scenario-based questions.
Get the Full Details
Working Through the Problem Sets
The review exercises typically ask you to create a monthly budget from given income and expense data, calculate total debt obligations, and determine whether someone is in a sustainable financial position. Start with the income side before touching expenses. Too many students begin with spending categories and then get confused when their numbers don't balance. When I was tutoring this material, I noticed a pattern. Students would correctly calculate their monthly expenses but forget to include annual obligations like insurance premiums or property taxes. The answer key accounts for these by spreading them across twelve months, but the question rarely spells that out explicitly. I started keeping a separate sheet where I listed every recurring payment, annual or otherwise, before building any budget. It added maybe five minutes to the process but eliminated most errors.
Common Mistakes to Avoid
One issue that comes up constantly involves the emergency fund calculations. The chapter typically recommends three to six months of expenses, but students often calculate this based on income instead of actual spending. Your emergency fund should cover what you actually spend, not what you bring home. This distinction matters most when answering applied questions rather than definition-based ones. Another frequent problem appears with compound interest questions. The textbook formulas work fine, but students struggle when the compounding frequency changes. Monthly compounding versus quarterly compounding produces different results even with the same nominal rate. If a question specifies the compounding period, make sure you adjust your calculations accordingly rather than defaulting to annual. The net worth section has its own trap. Students sometimes omit liabilities entirely when calculating net worth, or they include assets that aren't actually theirs. A car you're financing is still your asset, but the loan against it is your liability. Both belong in the calculation. The answer key expects this treatment, and exam questions will test it.
Using the Answer Key Effectively
Cheating yourself out of learning happens when you check answers before attempting the problems. Even a quick glance at the multiple choice section can prime your brain to recognize patterns rather than work through the material. Try to complete at least half the problem set before opening the key. When you do check your work, focus on the questions you got wrong. The ones you answered correctly don't need verification. Spend your time understanding why the incorrect approaches don't work rather than confirming what already seems right. This is where the actual learning happens in personal finance. Some answer keys online are outdated or incomplete. I've seen versions missing the budget calculation sections entirely, which leaves students without feedback on the most important part of the chapter. If the key you find seems incomplete, try looking for the instructor version rather than the student edition. They often contain the full solution sets with worked examples.
What the Chapter Actually Tests
Beyond the answer key itself, Chapter 7 is really testing whether you can make sensible financial decisions with incomplete information. Real budgeting rarely has perfect data. You might not know your exact utility bill until after the month ends. Credit card balances fluctuate. The textbook scenarios simplify this, but the underlying skill is adjusting your plan as new information arrives. The most useful takeaway from this chapter isn't any single formula. It's the habit of tracking your actual financial position regularly. People who maintain this habit tend to make better decisions regardless of whether they have an answer key or not. The chapter material gives you the framework, but consistent application is what actually moves the needle. If you're struggling with a specific problem type, the textbook's example problems at the beginning of each section usually mirror the exercise format. Work through those first before consulting any answer key. They're designed to build the exact skill sequence the review questions expect you to use.