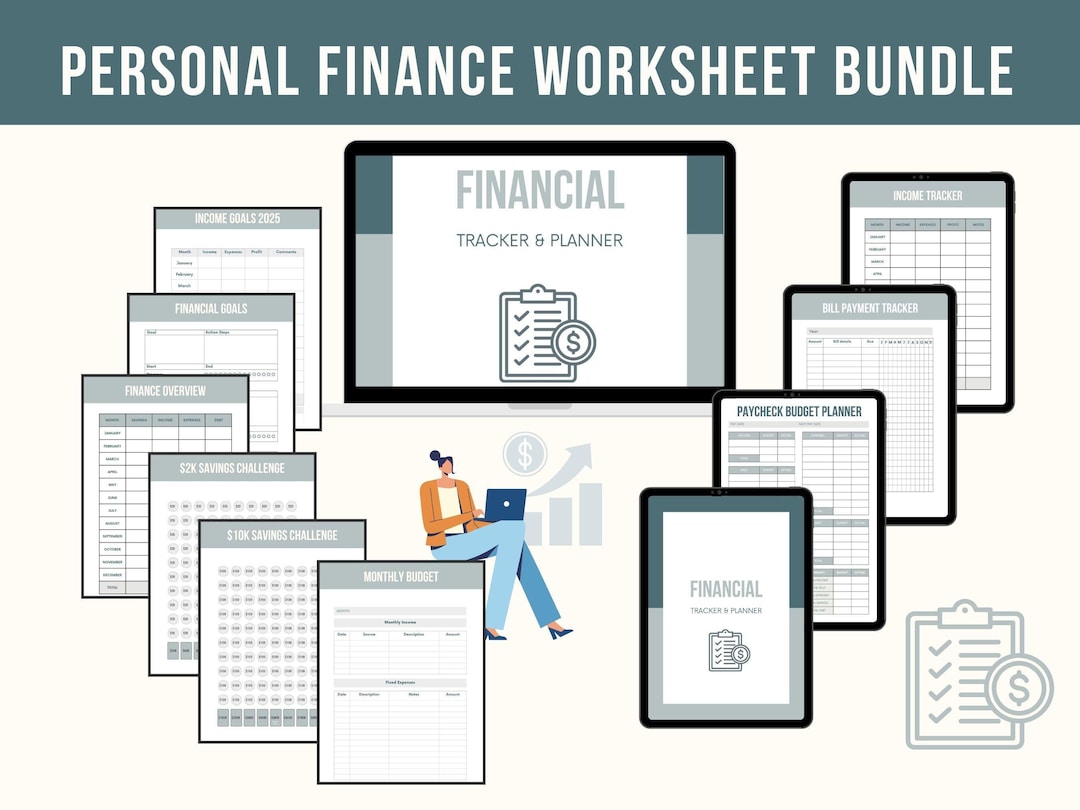
Personal Finance Worksheets Are Just Spreadsheets With Intent
Most people treat personal finance worksheets like they're supposed to transform your life the moment you fill them in. They don't. A personal finance worksheets system is just a structured way to see where money actually goes versus where you thought it went. The structure matters more than any particular template. Here's how I actually use them. I keep one sheet for fixed income and expenses, another for variable categories, and a third that tracks month-over-month drift. The third sheet is the one nobody tells you about. Without it, you're just filling in numbers each month with no way to know if things are actually getting better or worse. I learned that the hard way after spending three months carefully logging every coffee purchase and realizing my net worth was flatlining because my variable categories were bleeding in ways the other sheets didn't surface.
How to Build a Personal Finance Worksheets System That Actually Sticks
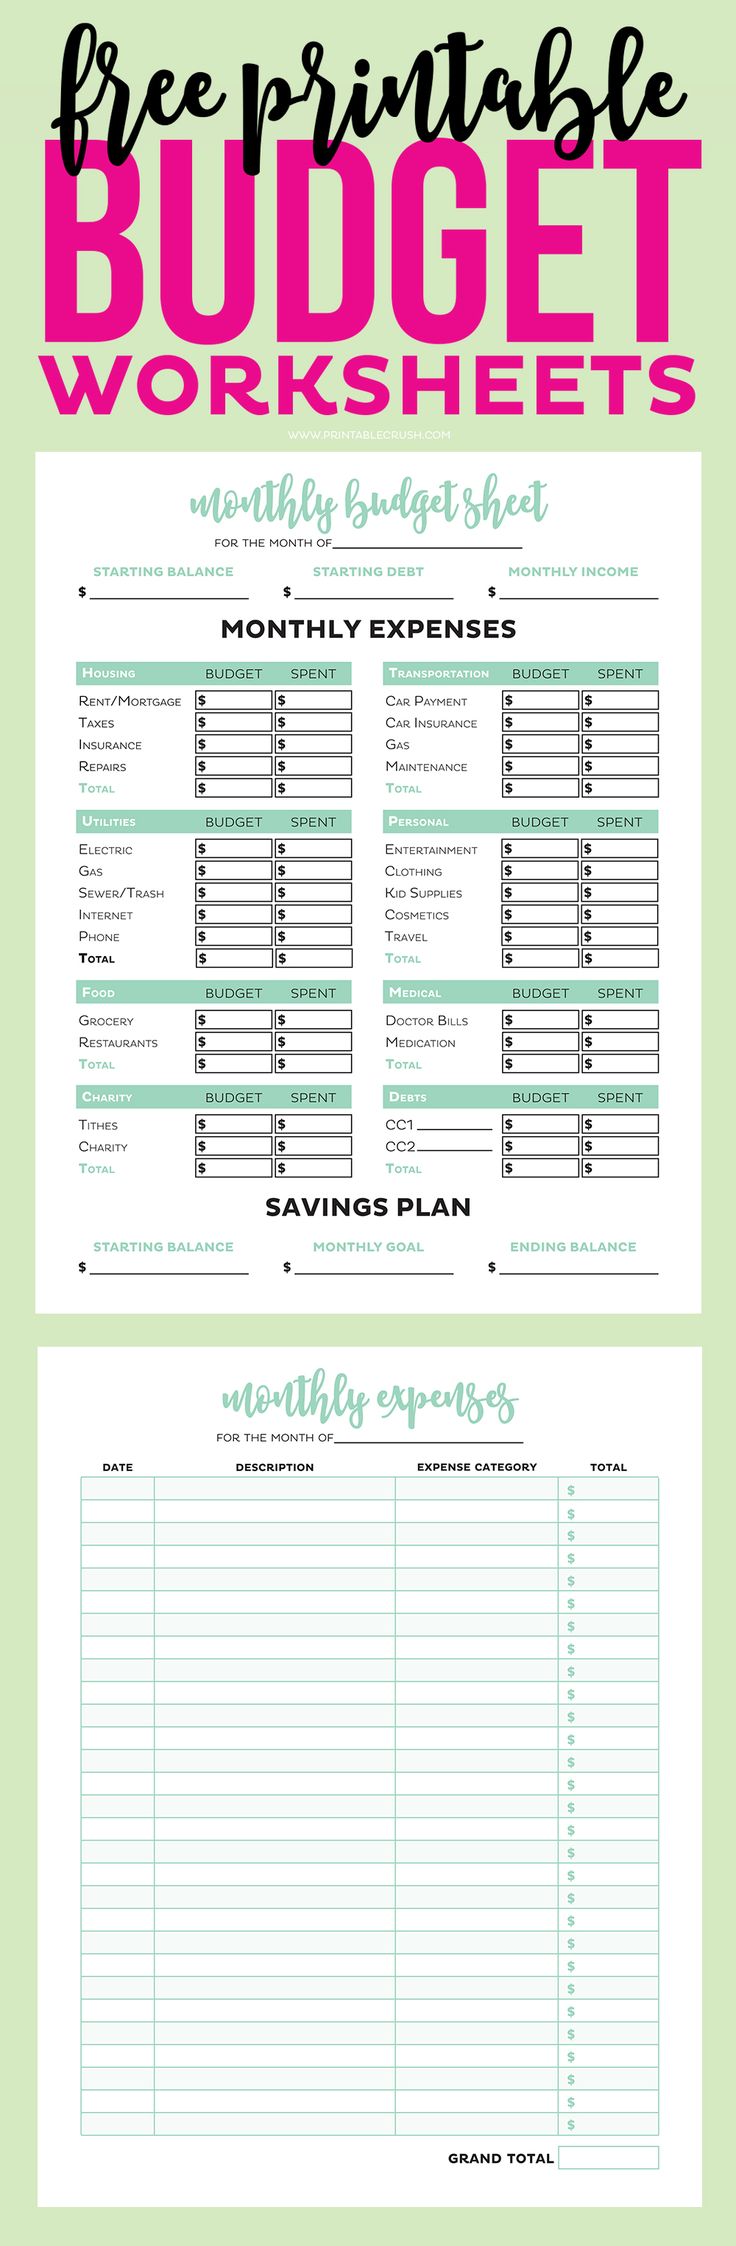
Start with income. List every source, not just your paycheck. Side work, dividends, interest, occasional sales. Most people omit the irregular stuff and then get confused when their budget looks tight on paper but empty in reality. Next, fixed expenses. Rent, insurance, loan minimums, subscriptions you can't cancel without losing access to something critical. Put them at the top. These are non-negotiable. Everything below them is where decisions happen. Variable expenses are where the actual work lives. Groceries, dining, transport, entertainment, medical. The tricky part is setting realistic ceilings. Look at your last six months of actual spending in each category, not what you think you should spend. There's a difference. I once tried to budget $200 a month for groceries based on a coupon-clipping fantasy. My actual average was $410. That $210 gap showed up as a mystery deficit every single month until I just used real numbers.
Set up a reconciliation row at the bottom of each category. Income minus expenses equals surplus or deficit. Do this monthly. Then do it again the following month and compare. The comparison is the whole point. For the tracking piece, I recommend using conditional formatting to flag anything that overshoots by more than ten percent. It sounds excessive but it catches the slow leaks. A category creeping from $300 to $380 over three months doesn't trigger alarm bells unless you're actively comparing month to month. Conditional formatting makes the drift visible without requiring you to squint at raw numbers. One thing most guides won't mention: your worksheet needs a debt section if you carry any. Not just balances, but interest rates and minimum payments. The order in which you pay down debt matters enormously. High interest first, or the avalanche method, versus smallest balance first, which is the snowball method. Both work. The snowball method has better psychological retention because you close accounts faster. The avalanche method saves more money long-term. Neither is wrong. The only wrong move is not tracking which one you chose, because you'll second-guess yourself within six months and abandon the system entirely.
Get the Full Details
I found that combining a simple net worth snapshot into the same workbook as your monthly worksheets cuts down on decision fatigue. Instead of switching between two tools, everything lives in one file. I keep a separate sheet for net worth with assets on one side and liabilities on the other. Subtracting liabilities from assets each month shows you whether your efforts are compounding or stalling. This took me from feeling like I was managing money to actually seeing progress, which is a different psychological state entirely. The main limitation of worksheets is that they require consistent input. If you skip a month, the comparison data becomes meaningless. I've seen people build elaborate systems, spend two hours setting up formulas and formatting, then use them for eleven days and never open the file again. The tool is only as good as the follow-through. If you know you'll be inconsistent, start smaller. A single sheet with ten categories updated weekly beats a fifty-row masterpiece you abandon in January. Another edge case worth noting: couples or shared households create friction in worksheet systems because spending habits and priorities diverge. I worked with a client where one partner tracked everything meticulously and the other treated the shared spreadsheet like a suggestion. The system broke within three months because there was no agreement on who was responsible for updating which categories. We solved it by splitting responsibility clearly and running a monthly review together. Not daily. Monthly. The weekly check-ins were creating resentment, not accountability.
Templates exist online. Some are decent. But the best personal finance worksheets are the ones you adapt to your actual life, not the ones you force your life into. Download something free, break it, rebuild the parts that matter, and ignore the rest. The spreadsheet that works is the one you actually maintain.
Common Mistakes That Make People Quit
Categorizing too granularly. I've seen people with fifty expense categories. That's not detailed tracking. That's administrative overhead disguised as discipline. Ten to fifteen categories maximum keeps the system usable. You can always dig deeper later if a specific category needs more attention. Setting budgets based on aspirations instead of history. Your budget should reflect who you actually are, not who you want to be. If you spent $500 on dining last quarter, budgeting $150 will fail. Budget $400, track closely, and adjust downward gradually if that's a goal. Ignoring inflation and wage changes. A worksheet you built two years ago without adjusting for cost increases is essentially a time capsule. Update your baseline numbers annually or whenever a significant change hits your income or housing costs.
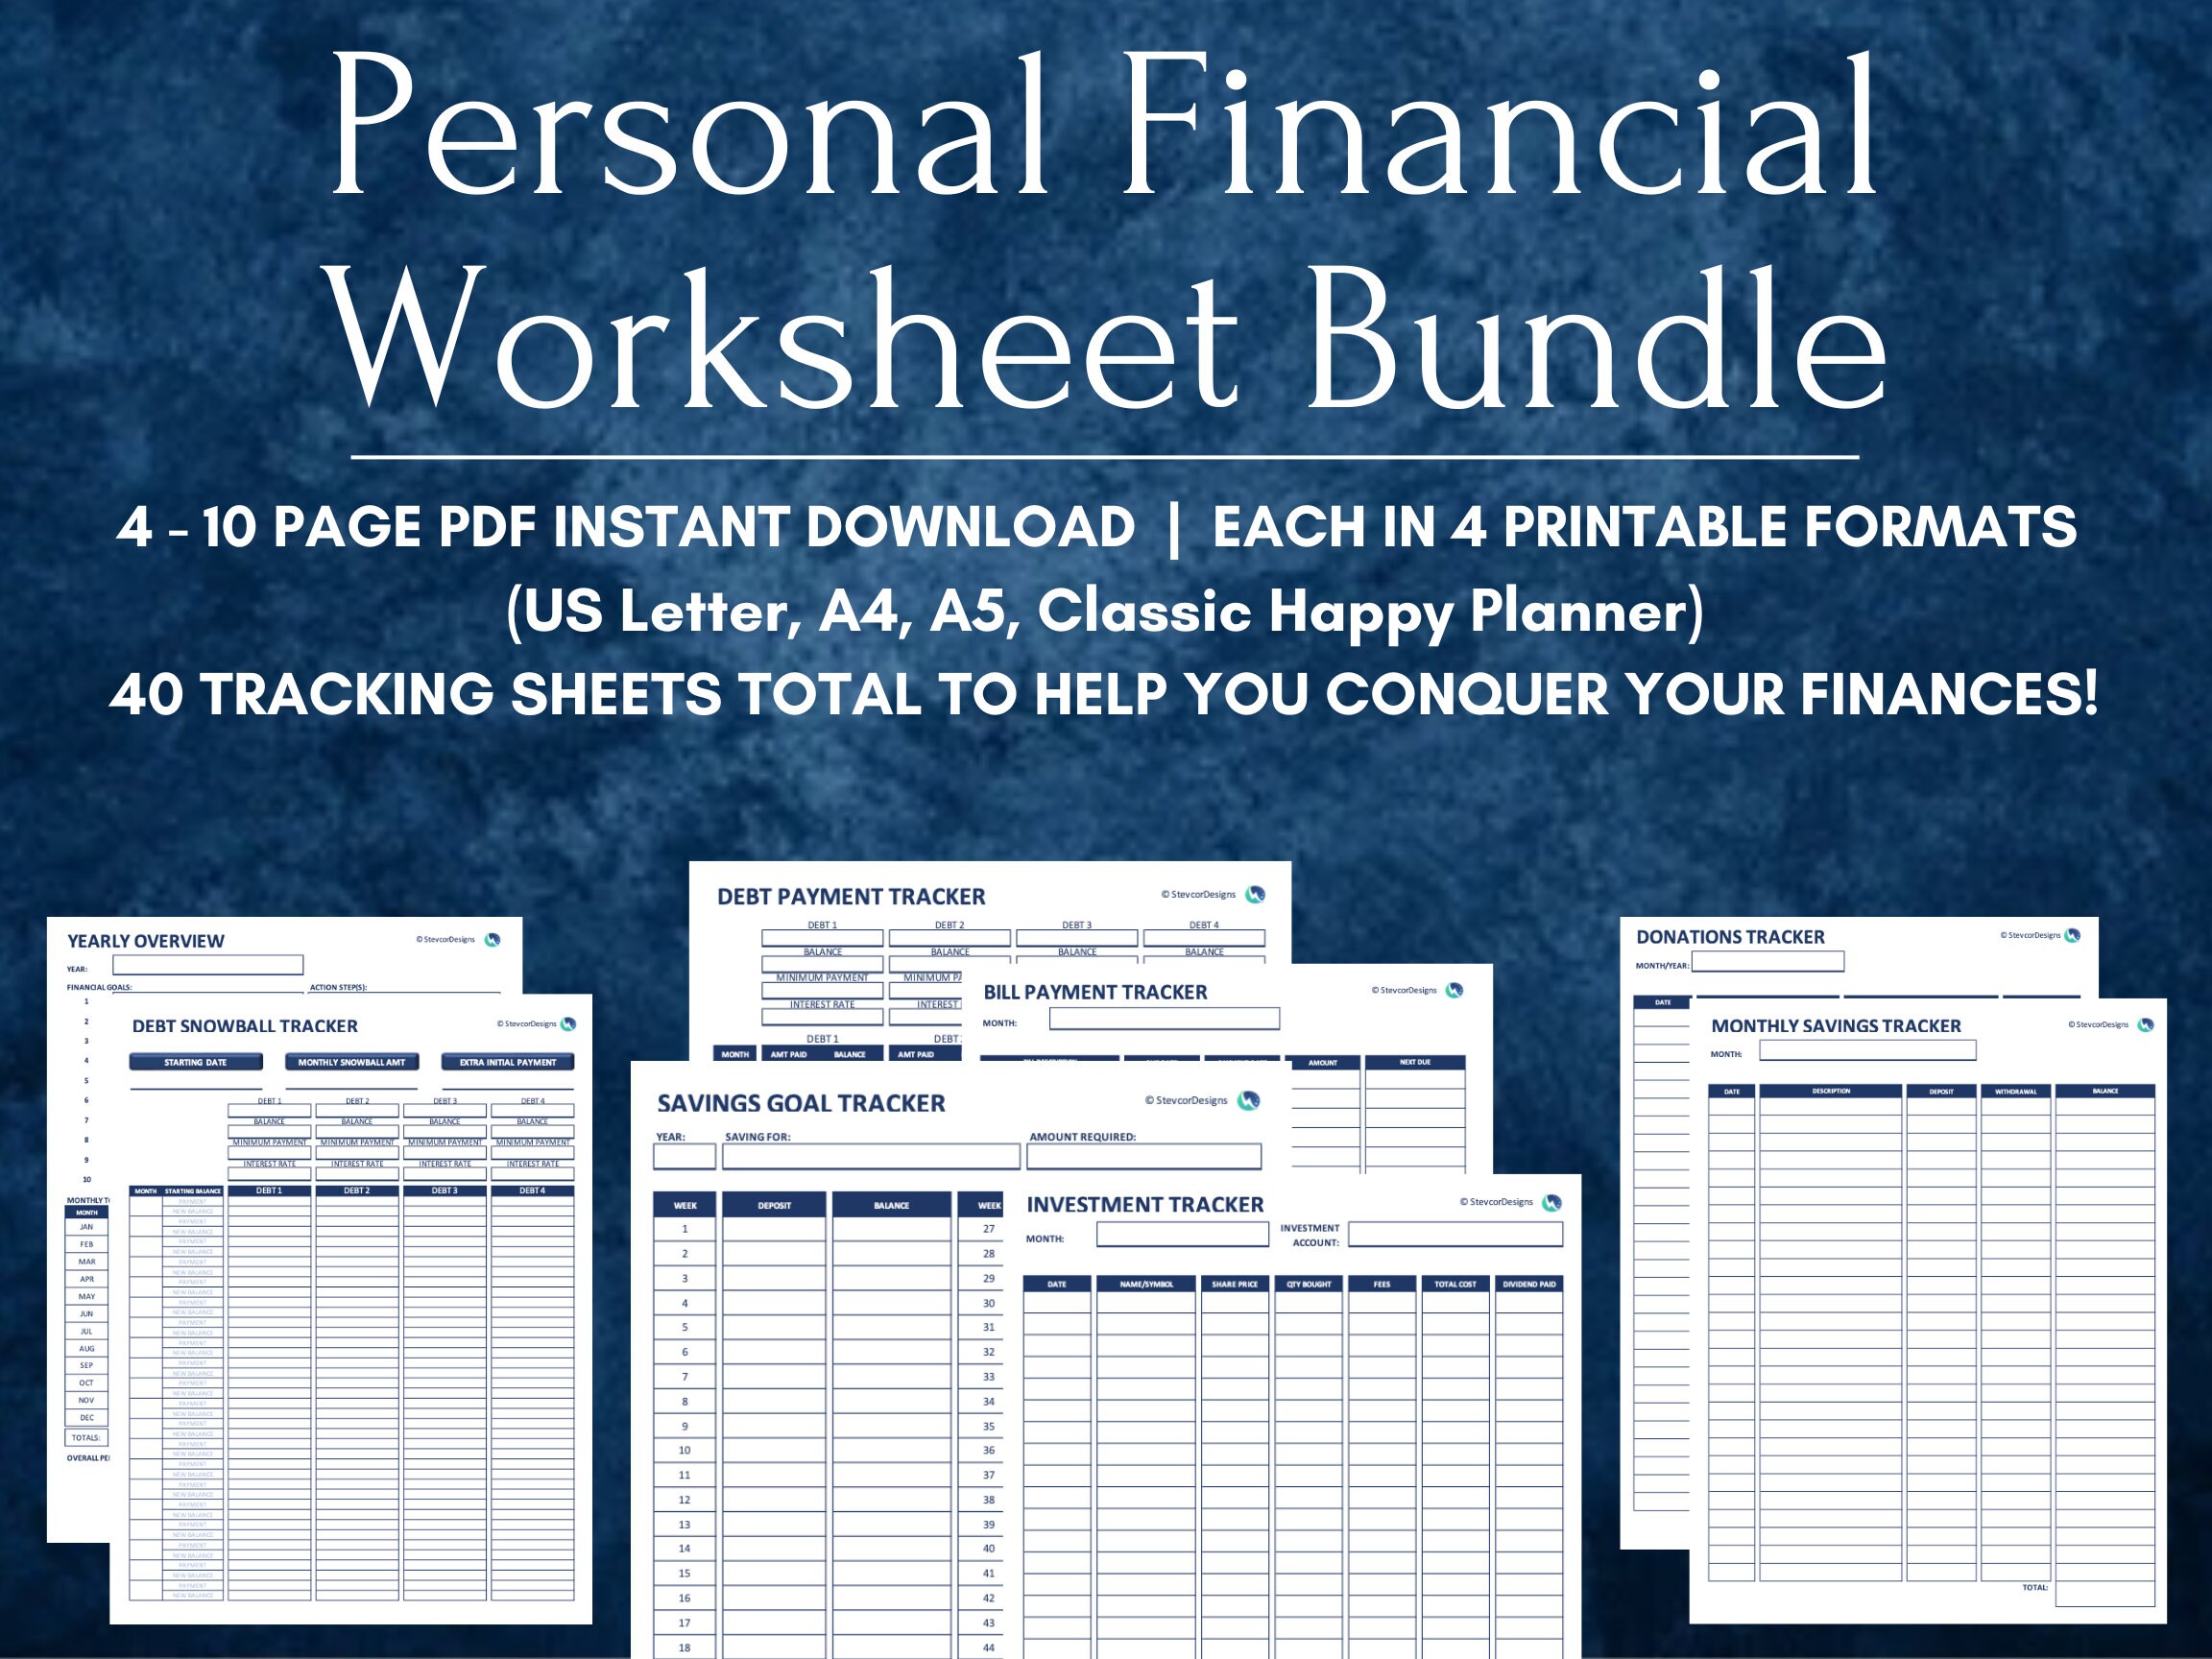
Using multiple disconnected tools. One spreadsheet for budgeting, another app for investments, a third for debt. The context switching eats away at consistency. Keep it in one place if you can. If worksheets feel too manual, that's a valid observation. The alternative is automated tracking through banking apps and budgeting software. Those work well for people who want set-and-forget monitoring. But they rarely give you the same level of customization or the sense of ownership that building your own system creates. Neither approach is objectively superior. They serve different types of financial engagement. The core idea is simple: put numbers on paper, compare them over time, adjust based on what the comparison shows. Everything else is decoration.