How to actually use free printable financial forms without making a mess
Most people grab a random PDF from some site and fill it out by hand, then wonder why it looks like a tax audit nightmare waiting to happen. The whole process is simpler than that, but it requires you to treat the form like a tool rather than a decoration. Here's what happens when you do it right.
What You Actually Need When You Go Looking for Personal Financial Forms Free Printable
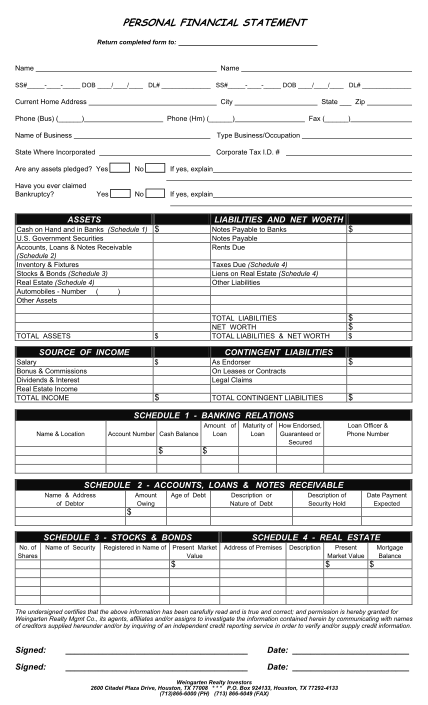
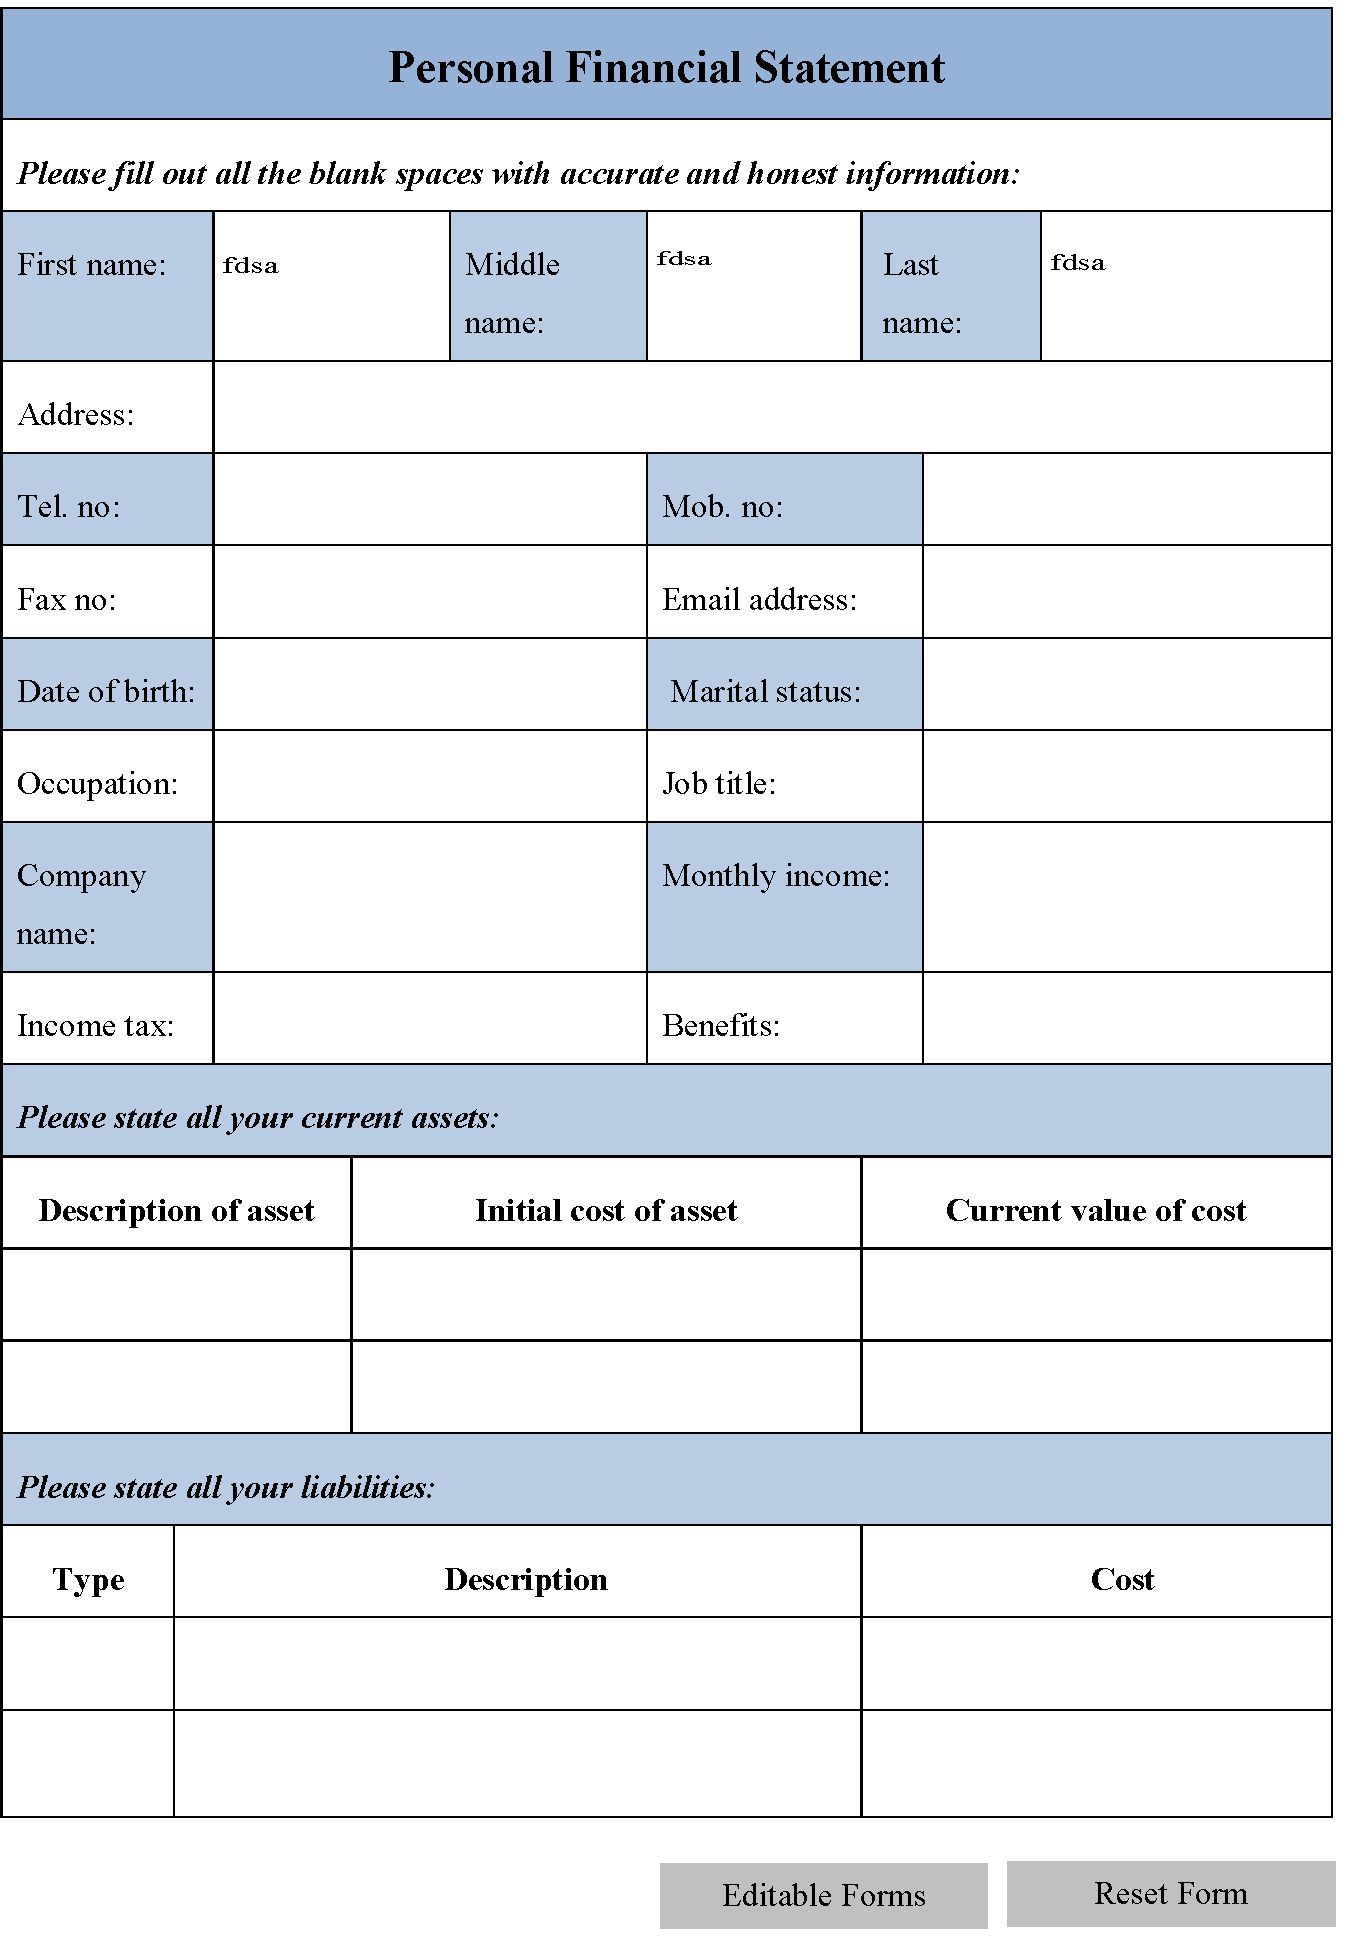
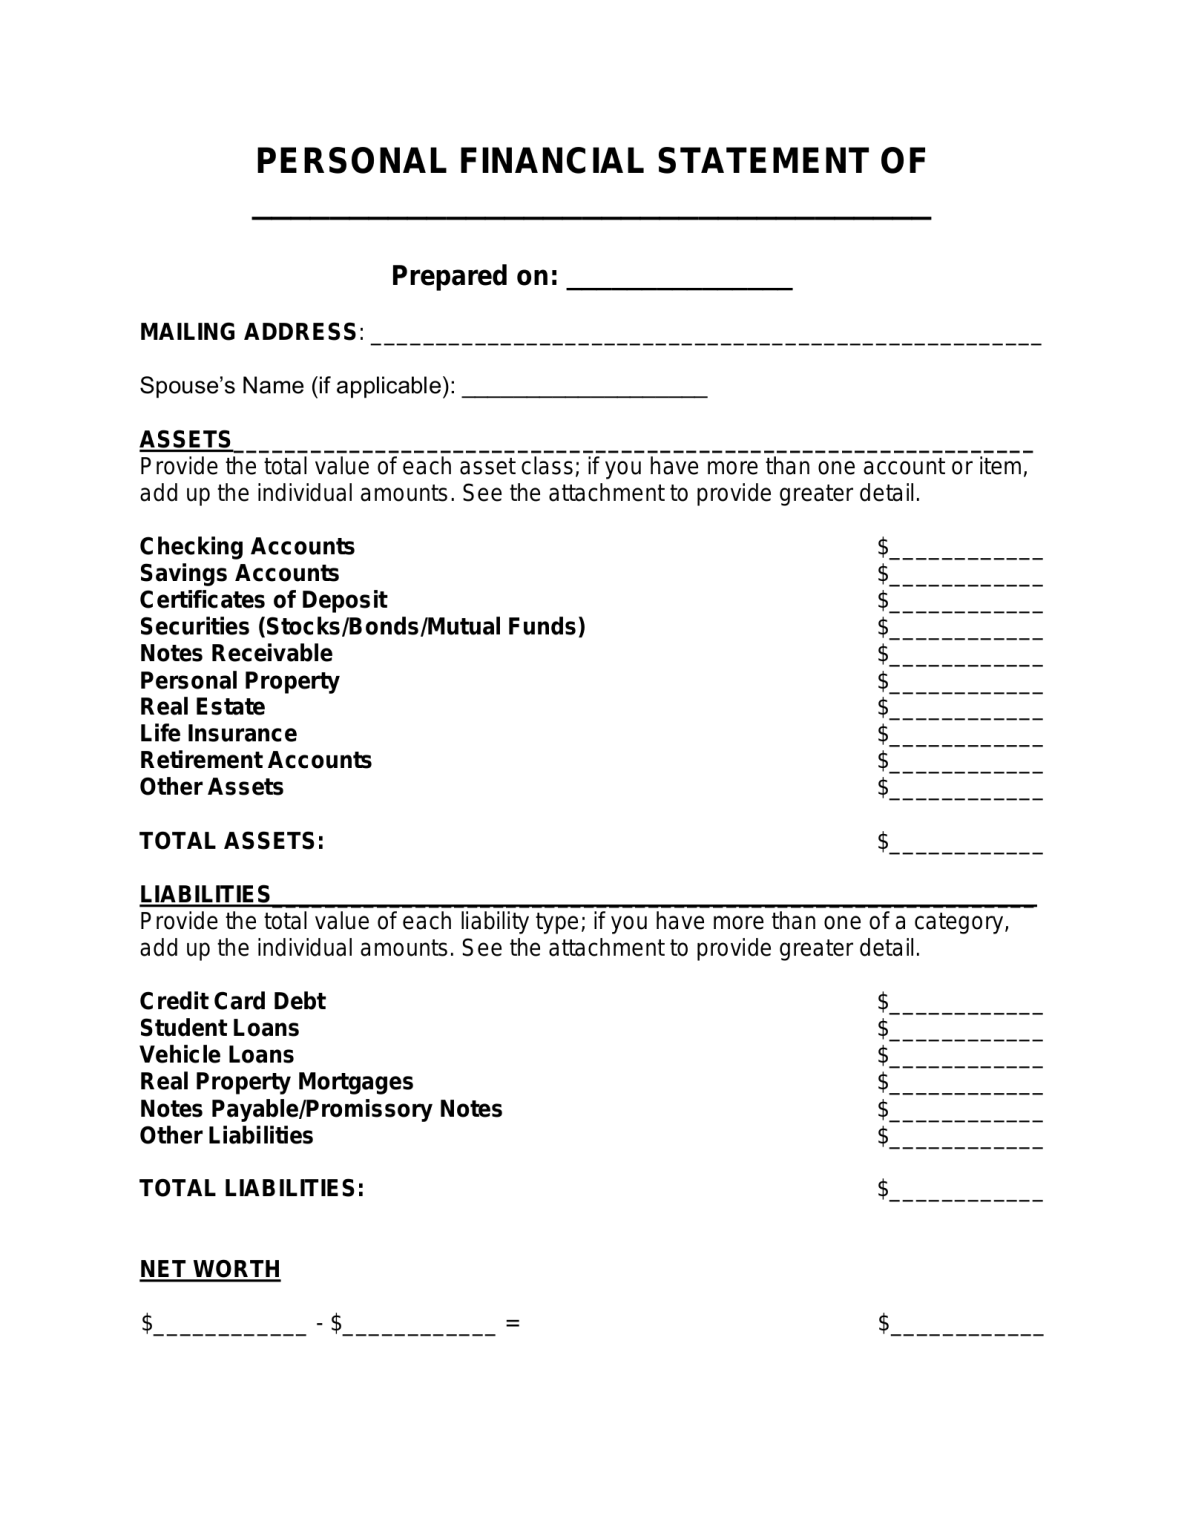
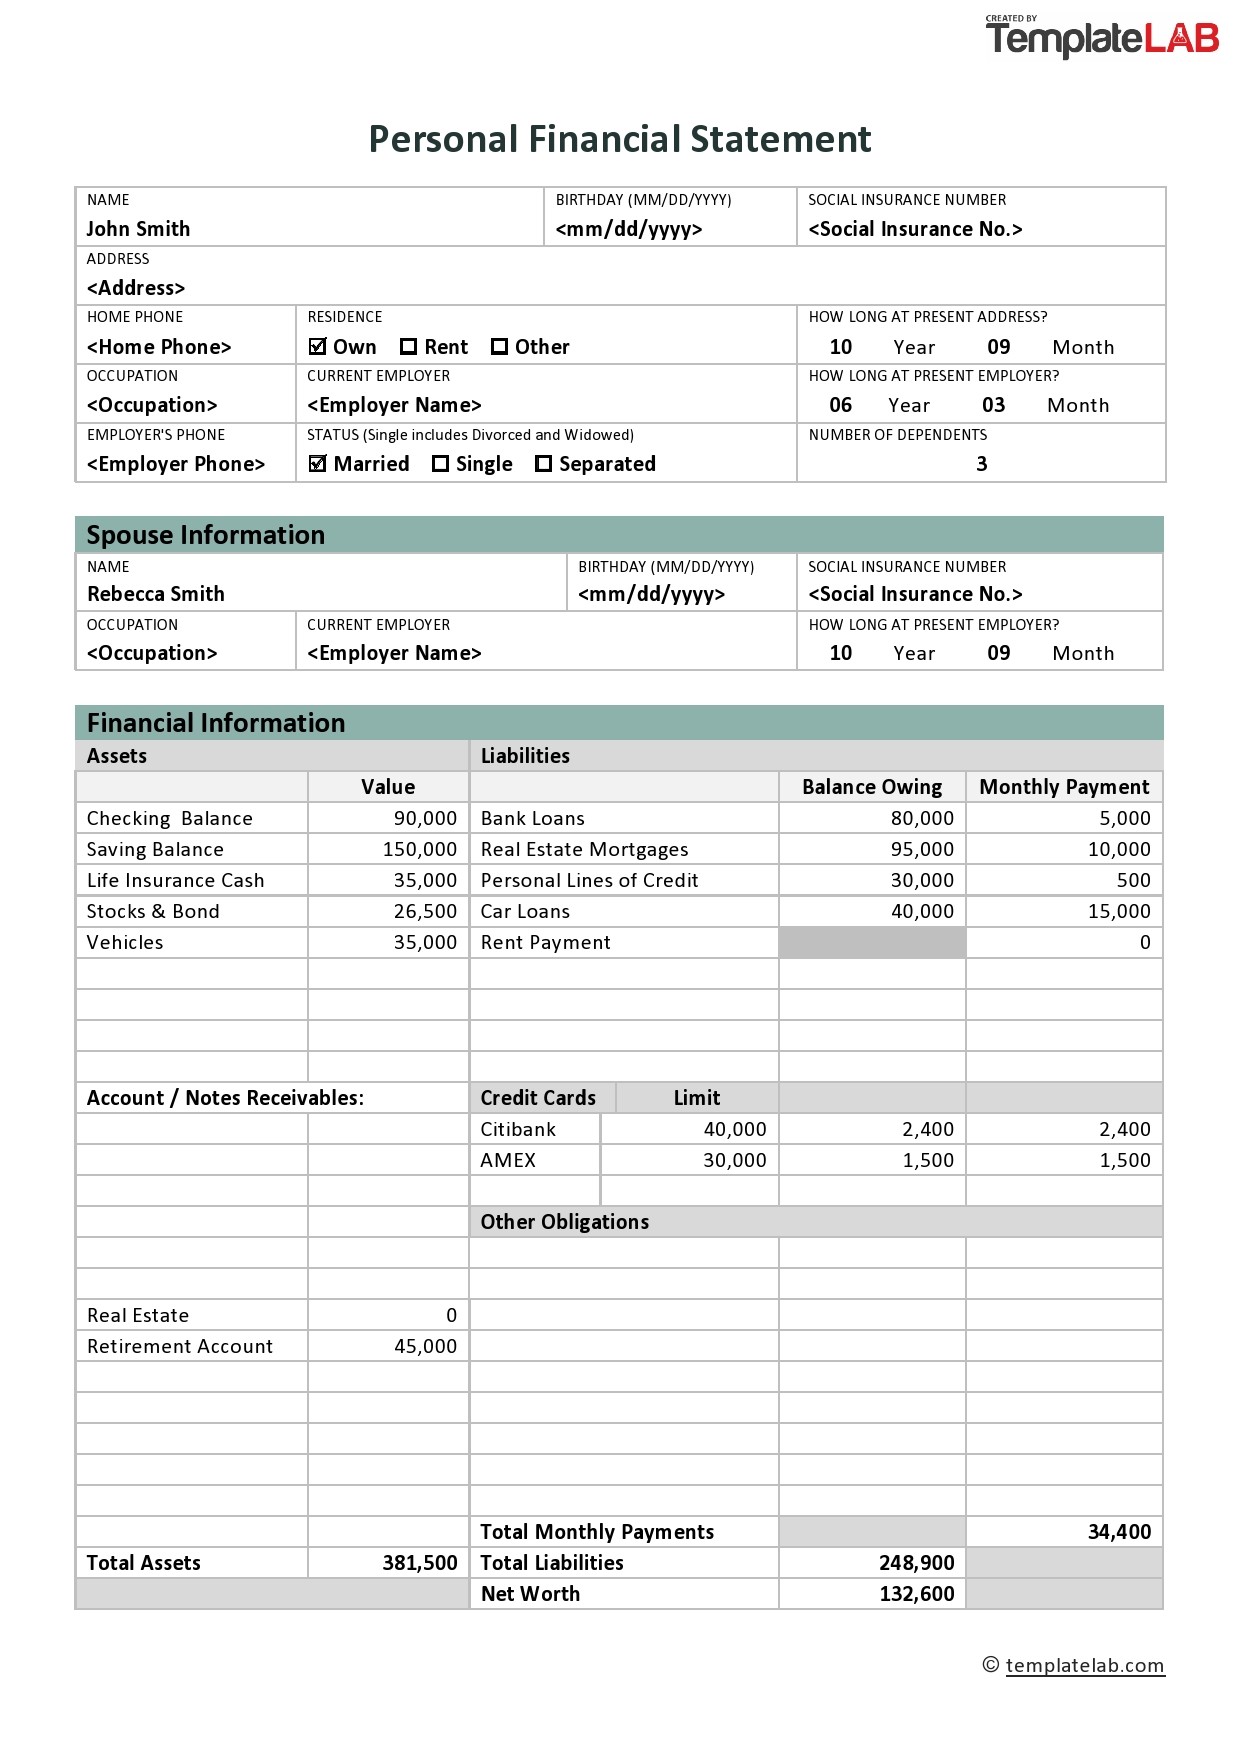
A net worth statement, a monthly budget template, a debt payoff tracker, and a cash flow log are the four pieces most people overlook. Not because they don't exist, but because most templates online skip the cash flow log entirely and pretend that tracking income against expenses once a month is enough. It isn't. Cash flow shifts week to week. If you're paid biweekly one month and monthly the next, a single snapshot tells you nothing about whether you can cover that mid-cycle grocery run without dipping into credit.The net worth statement is the part people mess up the most. I've seen thousands of dollars disappear from these forms because someone listed their car at what they "think" it's worth, not what the Kelley Blue Book says for their specific mileage and condition. Use actual market values, not guesses. Same with your mortgage balance — use the current principal remaining from your lender's portal, not the original loan amount. I had a client once who was convinced he was nearly house-poor until he ran his net worth statement correctly, and it turned out he had over $140,000 in equity he'd been ignoring for three years. He paid off two credit cards the next month.
The Actual Process, Step by Step
Download a blank version of each form first. Don't fill it out inside a pre-formatted template from some website. Open the blank version in a spreadsheet program and build your own structure. You'll save about two hours per month in the long run, and more importantly, you'll actually understand what each line item means instead of blindly moving numbers around.Start with the net worth statement. List every asset at current market value. Cash, checking, savings, retirement accounts, investments, real estate at Zillow's estimate or your assessor's value — whichever is lower, just be consistent. Then list every liability. Credit card balances, student loans, auto loans, mortgage principal, personal loans. Subtract liabilities from assets. That number is your starting point. Re-do this every quarter, not every month. Monthly changes in retirement account values from market swings will make you crazy. Quarterly smooths that out. Next, the budget. Track actual spending for one full month before you try to create a realistic budget. I've watched too many people build budgets based on memory, and memory is unreliable. Your "usual" grocery bill is probably 20 to 30 percent higher than you remember. Write down every single purchase, including the dollar coffee. One month of actual data will change your budget more than a year of guessing. For the debt payoff tracker, use the avalanche method unless you have a specific psychological reason to use snowball. Avalanche means listing debts from highest interest rate to lowest and attacking the highest one first. It saves you the most money over time. The snowball method — smallest balance first — works for motivation but costs you money. I worked with someone who had $18,000 in debt across four cards. She switched from snowball to avalanche and cut her total interest payment by $2,300 over the life of the debt. She didn't even notice the difference in monthly effort. Just a different order of attack.
Get the Full Details
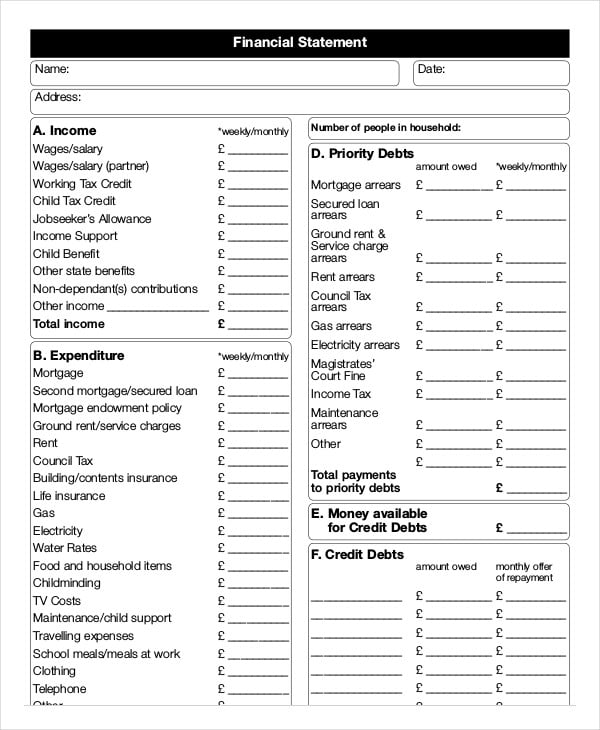
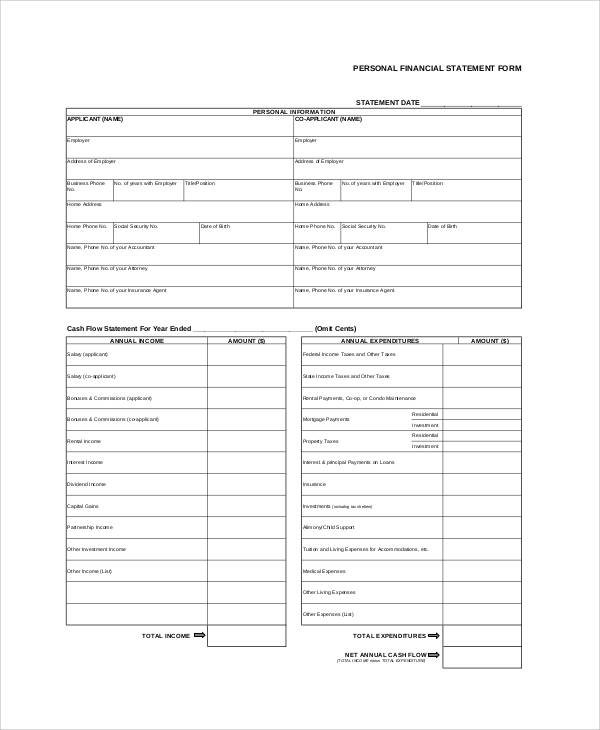
The cash flow log is the one nobody builds. Put your income dates and amounts in a column. Put every recurring expense in another. Then calculate the gap between them for each pay period. Most people discover they're negative in their second pay period and don't know why until they look at the log. The fix is usually something small — a subscription you forgot about, a monthly fee that hits twice, or a spending category you never tracked. Once you see the gap, you can adjust. Sometimes the adjustment is just changing when bills hit. Sometimes it's a real conversation about spending.
Where People Get Stuck With Personal Financial Forms Free Printable
The biggest problem isn't finding the forms. It's keeping them updated. The average person fills something out once, feels good for three weeks, and then abandons it. The forms don't help unless they're living documents. I recommend setting a recurring calendar event for the last Sunday of each month. Fifteen minutes. Update the numbers. That's it. If it takes longer than fifteen minutes, your template is too complicated. Simplify it.Another issue: people use forms designed for salaried employees when they're self-employed or variable-income. A W-2 format budget doesn't work if your income fluctuates between $2,000 and $6,000 a month. Use a category-based system instead. Bucket your income by month and assign it to categories. Carry over any surplus to the next month. This is how contractors and freelancers actually survive without blowing up their finances in lean months. Printed forms have a specific limitation. If you print them and write on them by hand, you can't easily recalculate totals or swap numbers around when you make a mistake. If you're going to print, print a blank copy and fill it digitally first, then print the final version for your records. Or just keep it digital. The only reason to print is if you want a physical paper trail for your accountant or loan application. Otherwise, a spreadsheet on your computer is faster and less error-prone. There's also the issue of data security. Some of the free form sites ask you to create an account, enter your bank login, and they auto-import transactions. Don't do this. You're handing your financial data to a company whose primary business model is advertising, not financial advice. There are plenty of reputable spreadsheet templates that exist without requiring an account. Use those instead.
When Free Printables Don't Cut It
If you have multiple income streams, significant rental properties, stock options, or a complex tax situation, free printable forms will only take you so far. They're fine for basic budgeting and net worth tracking. They're not designed for tax planning or investment allocation. At that level, you need a certified financial planner or a CPA who understands your specific situation. The forms are a starting point, not a replacement for professional advice. Knowing the difference saves you from making expensive assumptions based on a PDF.