Why most people build their financial statement wrong
A personal financial statement is a snapshot of your net worth at a single point in time. It lists everything you own, subtracts everything you owe, and leaves you with a single number. Sounds simple enough. The problem is that anyone who has been through a loan application, divorce proceeding, or audit has probably seen how badly this can go wrong when it is done carelessly. I spent years helping people get loan packages approved, and more often than not the statement itself wasn't the issue. It was the supporting documentation. One borrower had a rental property held in an LLC. He listed it under assets as if it were a personal asset. The underwriter rejected the application because the LLC was a separate legal entity, and she couldn't verify his ownership stake from his personal tax returns alone. The workaround was pulling three years of K-1 schedules from the partnership tax filings to substantiate his share of the property value. Takes about twenty minutes if you know where to look, two weeks if you don't.
What a Personal Financial Statement Template actually does
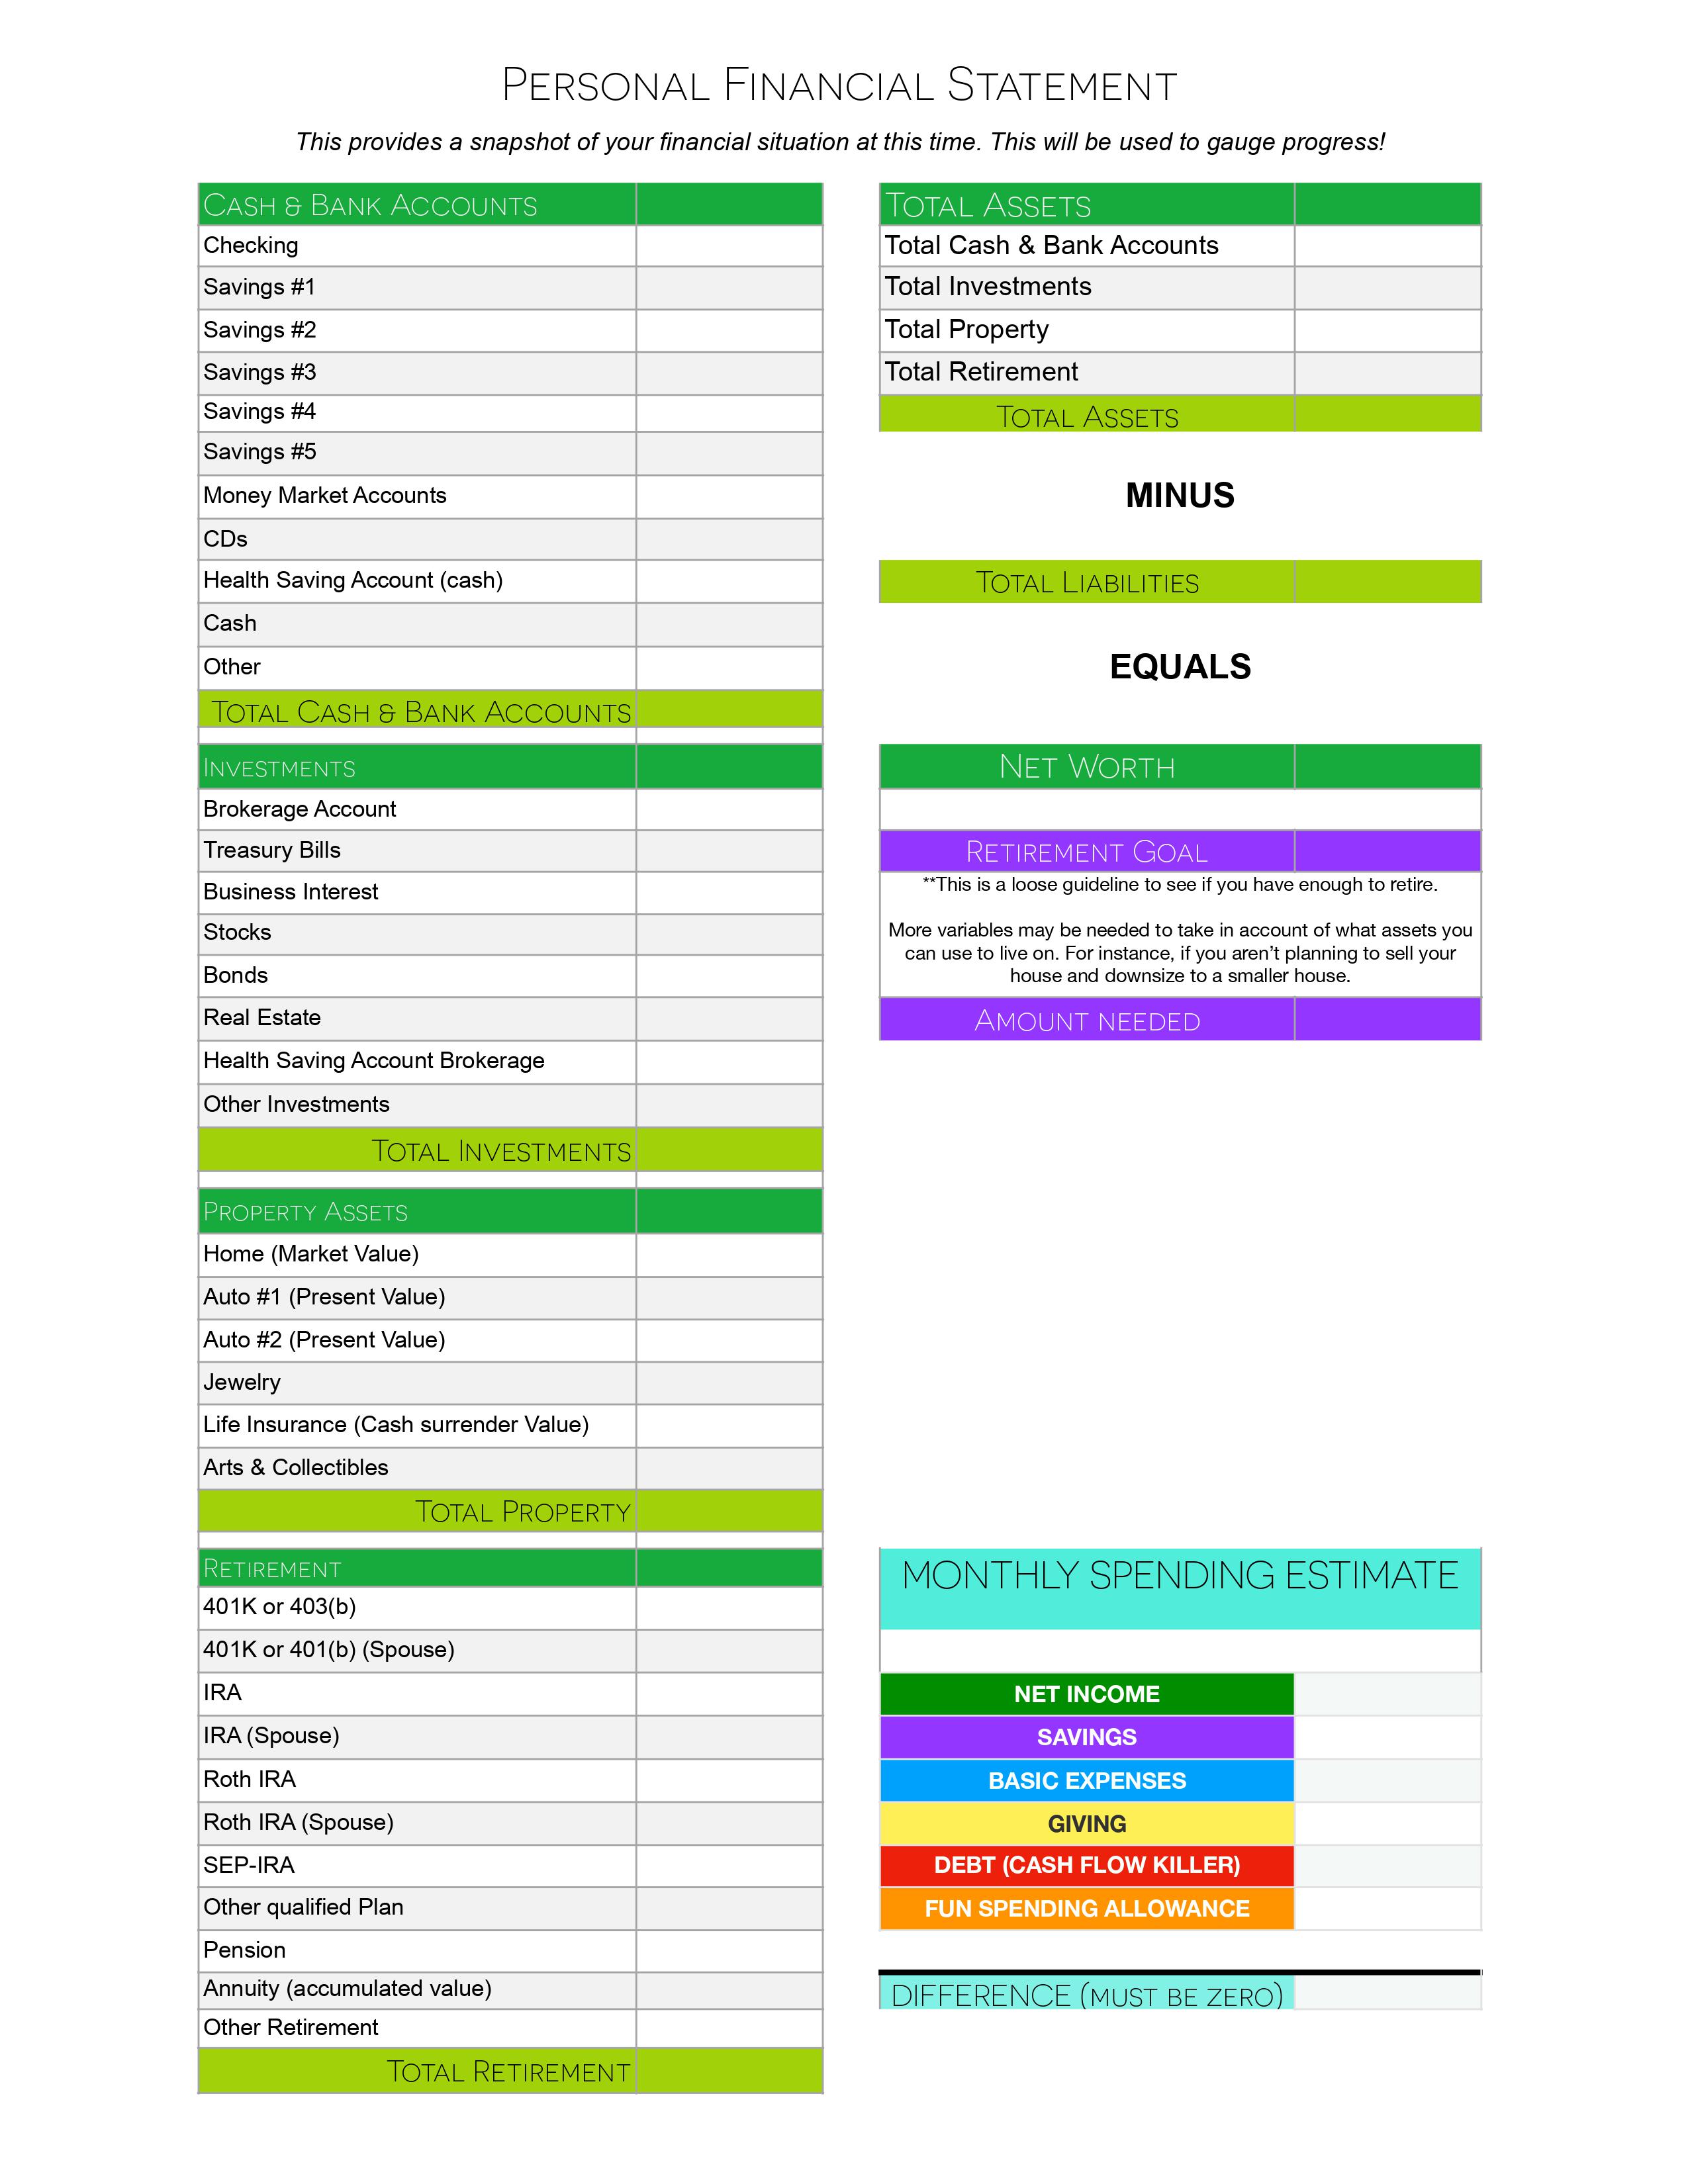
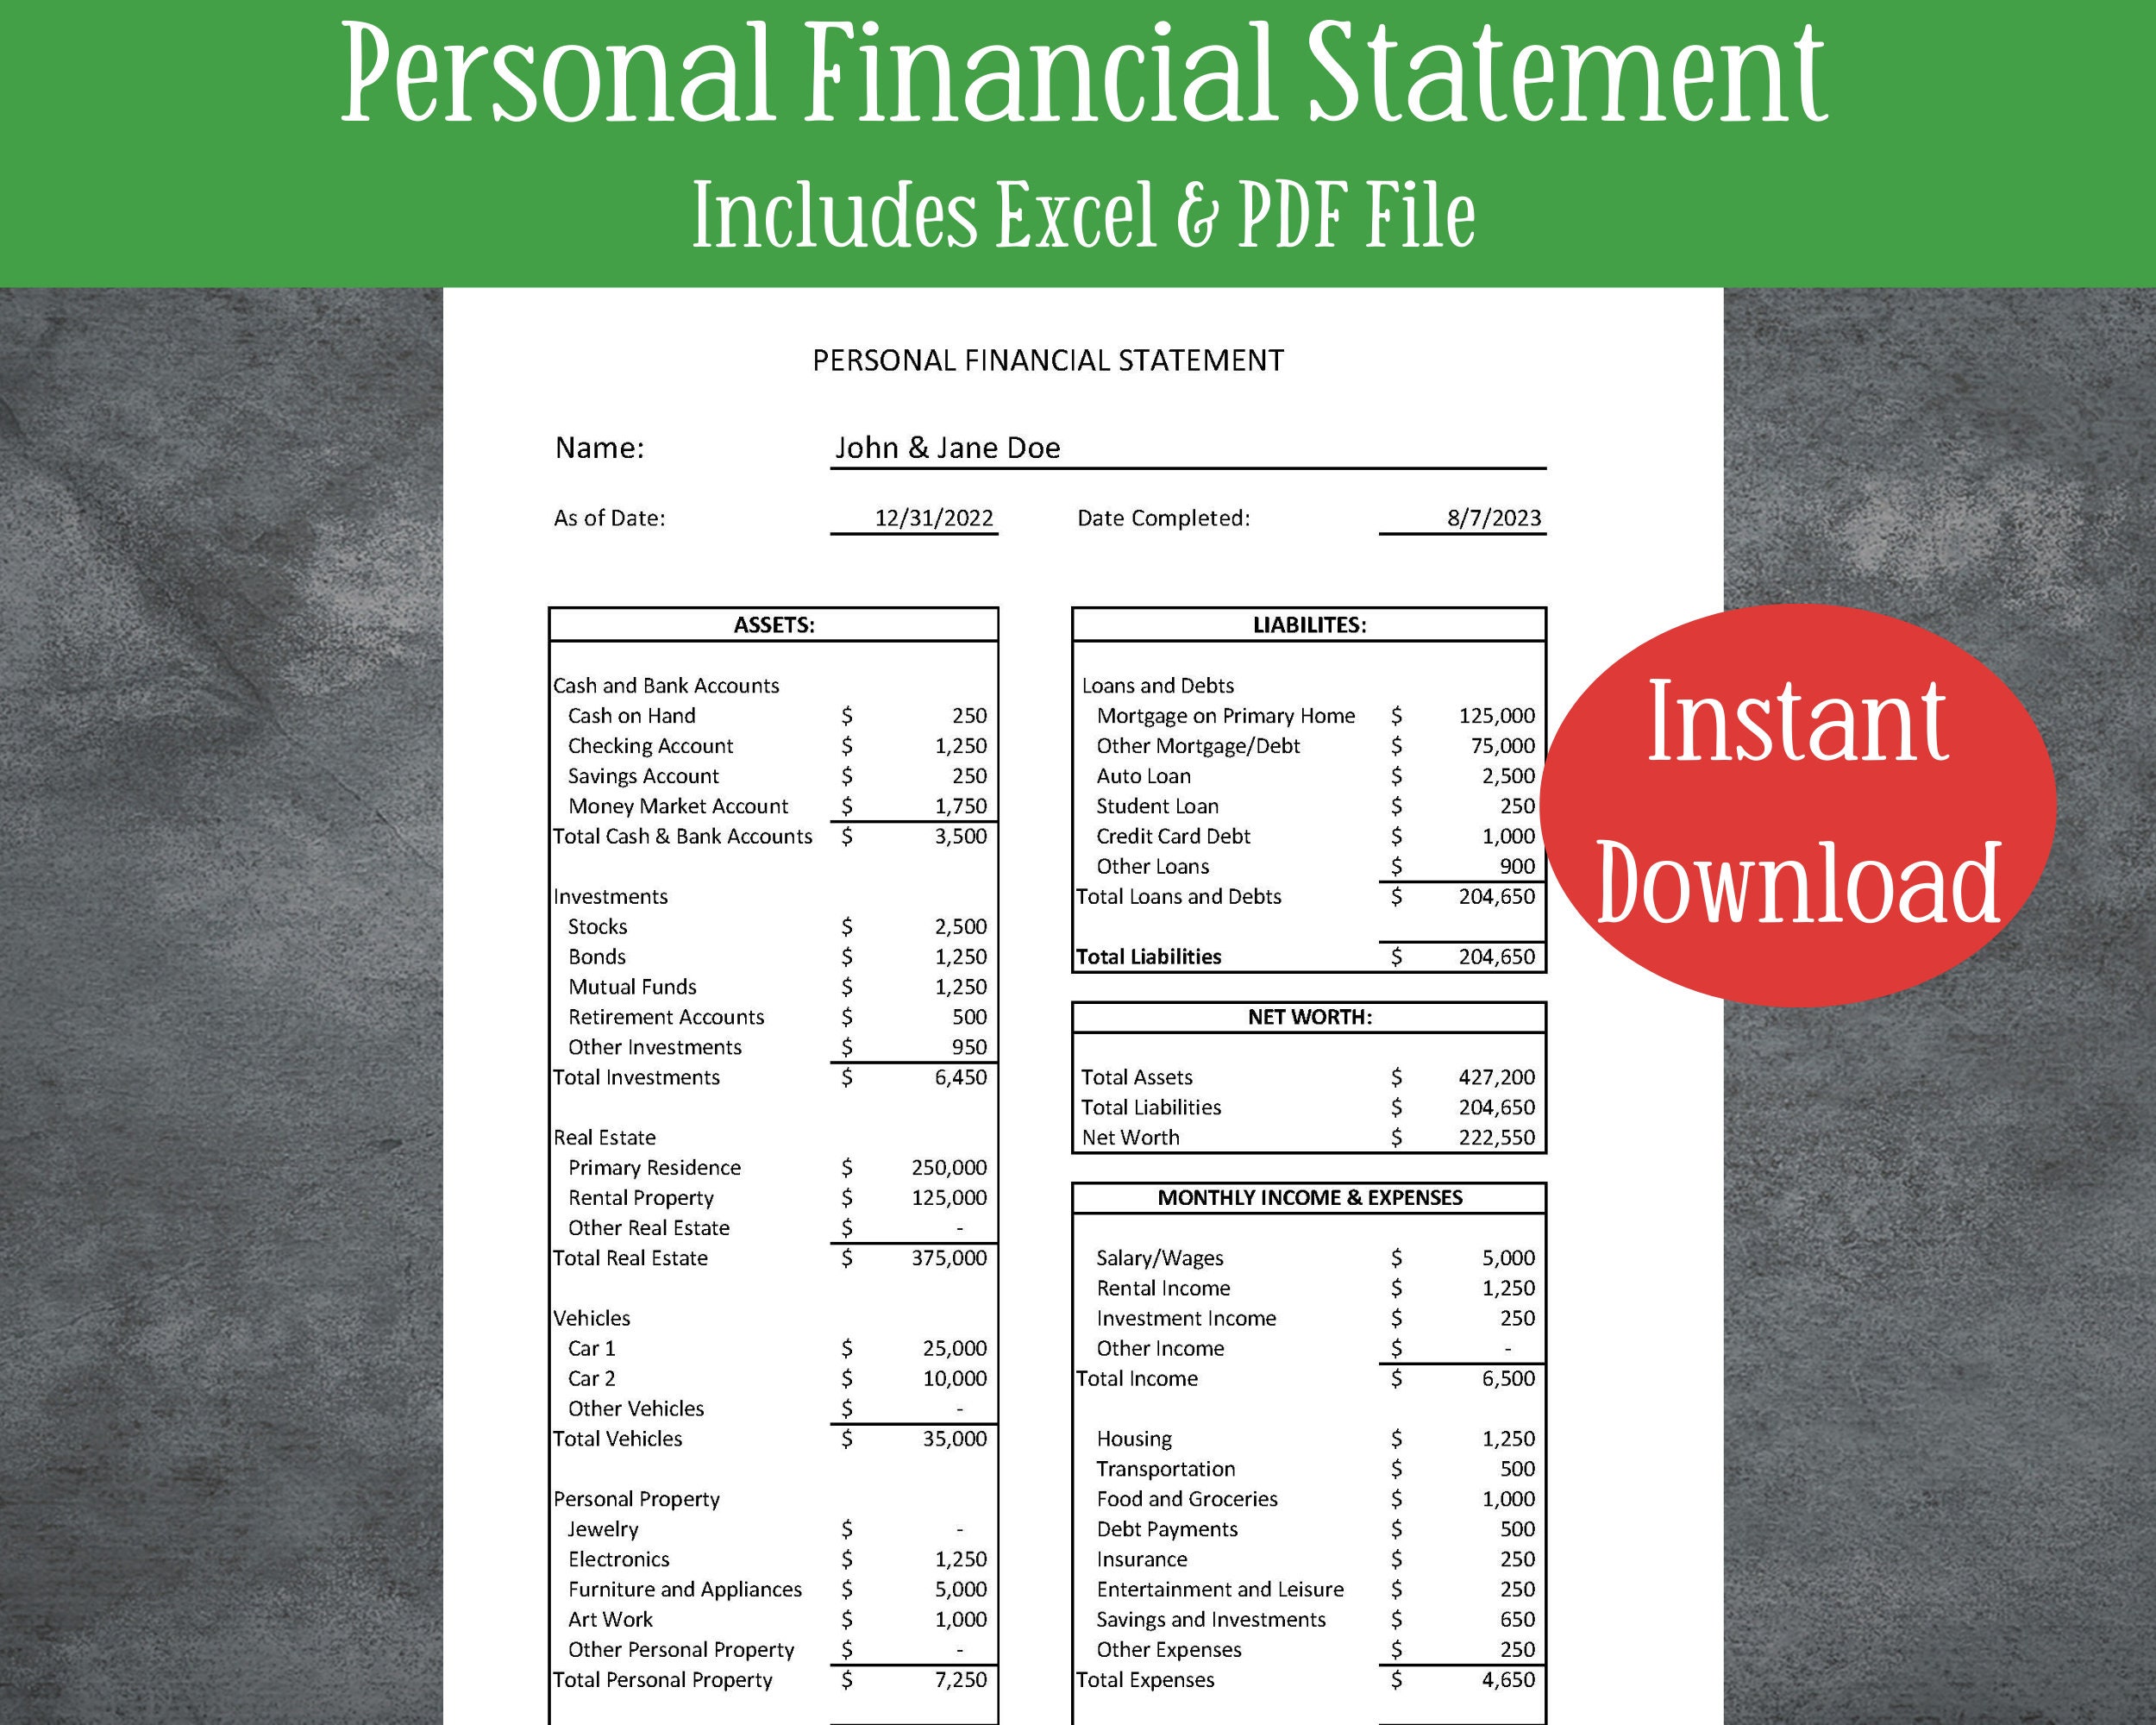
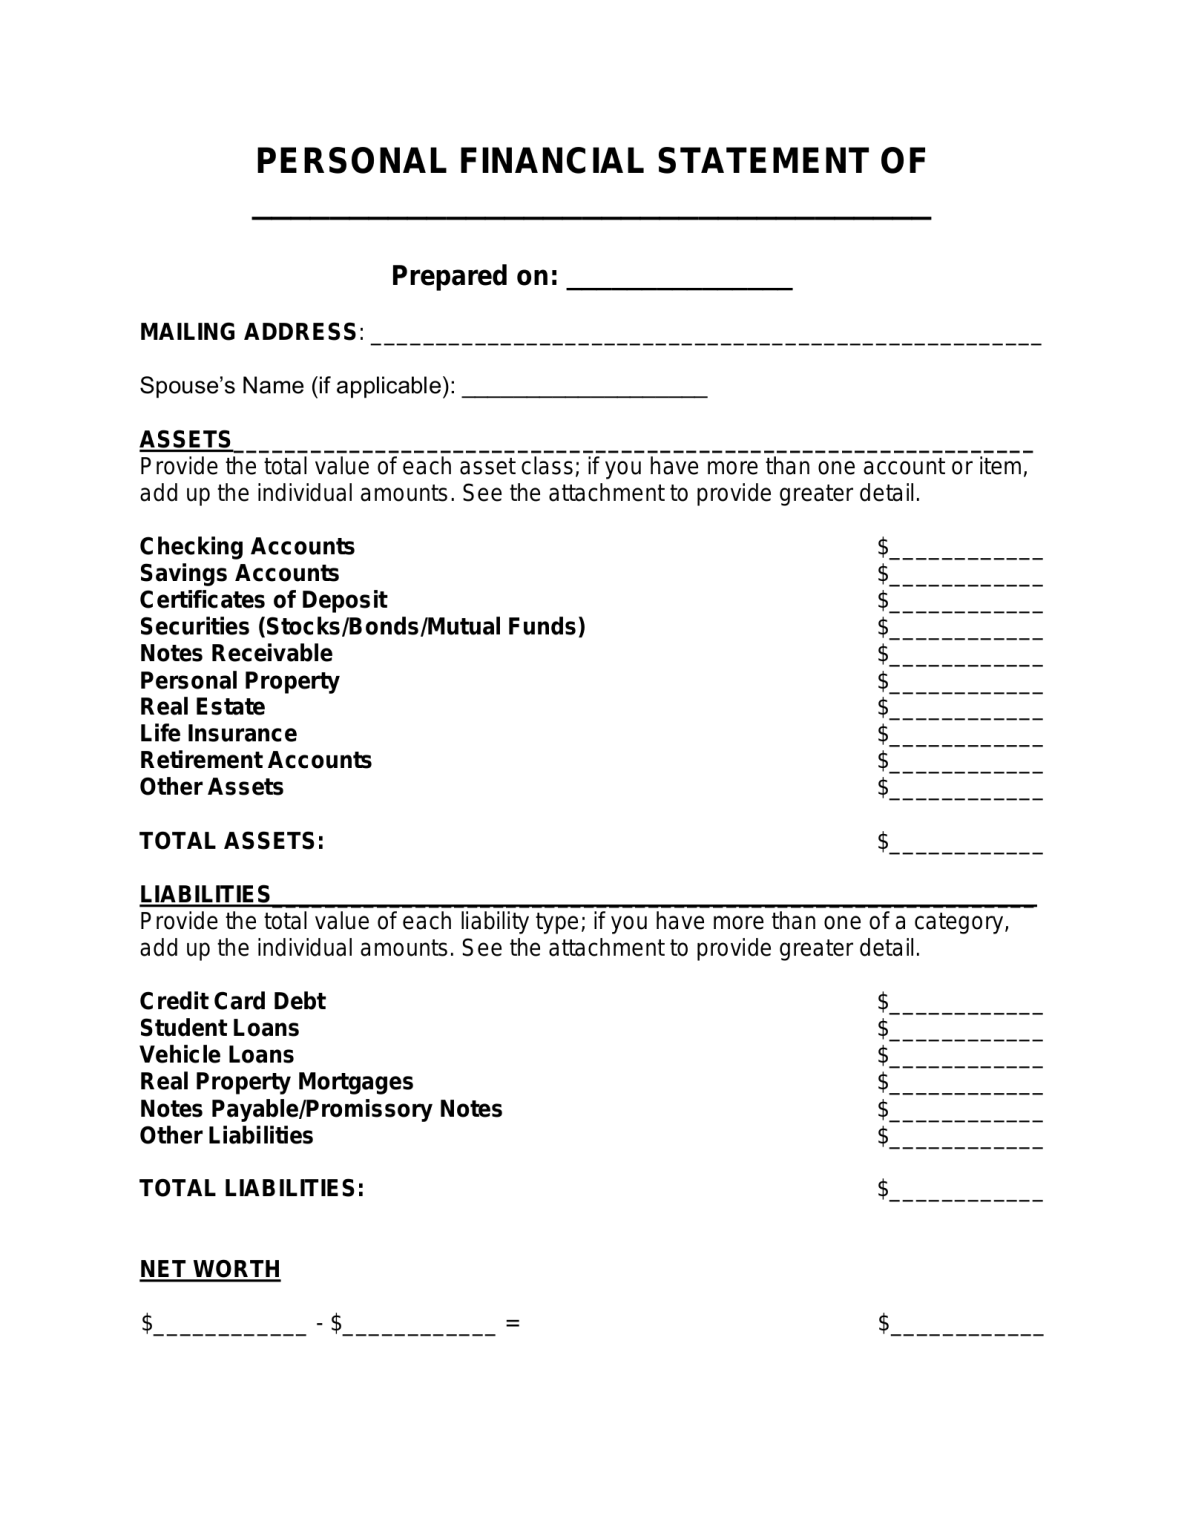
A template gives you the structure without forcing you to design a spreadsheet from scratch. It provides labeled rows for assets and liabilities, sections for cash, investments, real estate, vehicles, retirement accounts, and a liabilities section covering mortgages, credit cards, student loans, and other debt. Some also include a net worth calculation at the bottom, though a lot of people treat that as optional. It is not optional if someone is going to read this document and try to make a decision based on it. The key thing most people miss is that a personal financial statement is point-in-time, not a summary over a period. Your checking account balance on March 31st is what goes in, not your average balance for the quarter. Same with your retirement accounts. Same with the market value of your investments. You do not use what you contributed. You use what it is worth right now.
How to build it without wasting two days
Start by gathering the raw data before you open any spreadsheet. This saves you from constantly switching tabs and forgetting where you pulled a number from. Log into your bank, your brokerage, your mortgage servicer, and your credit card portals. Export whatever you can. If you are doing this for a formal purpose like a loan application, use the actual statements, not screenshots. Printouts or PDFs from the institution's official portal work best. Here is a practical order that most people should follow: Cash and equivalents. Checking, savings, money market, CDs. Use the current statement balance. If you have accounts at multiple banks, list each one separately. Do not combine them into one line unless your template is designed to roll them up.
Get the Full Details
Investments. Brokerage accounts, stocks, bonds, mutual funds, ETFs. List the current market value. Not your cost basis. Not what you paid. What it is worth on the date you are preparing the statement. Retirement accounts. 401(k), IRA, Roth IRA, pension account values. These go under assets even though you technically cannot access them without penalty in most cases. A lender will still count them, but they may apply a discount factor. For 401(k) loans, the outstanding balance is actually a liability to you, so don't forget to include it under debt. Real estate. Primary residence, vacation homes, rental properties. Use current estimated market value, not your purchase price and not what you think it sold for last year. If you are preparing this for a formal process, a drive-by appraisal or automated valuation model (AVM) is usually acceptable. Full appraisals are rarely required unless the lender specifically asks.
Vehicles and personal property. Cars, boats, motorcycles. Use current fair market value from Kelley Blue Book or similar. This is where people lose credibility fast. Putting $40,000 on a ten-year-old truck because you remember paying that much new will get the statement flagged. Liabilities. Mortgages, home equity lines, car loans, student loans, credit card balances, personal loans, medical debt. List each one with the current balance owed. Use the most recent statement, not what you paid last month. Net worth. Assets minus liabilities. This is the final number everyone looks at first.
The specific template structure that actually works
Most blank templates online are too bare. They give you generic asset and liability rows but skip the categories that cause problems later. A functional template should have these sections with enough rows to accommodate a realistic portfolio: Assets section:
- Cash and cash equivalents (with sub-rows for each account)
- Investment accounts (brokerage, stocks, bonds, mutual funds, ETFs)
- Retirement accounts (401k, IRA, Roth, pension)
- Real estate (primary, secondary, investment with separate valuation columns)
- Vehicles (make, model, year, current value)
- Other personal property (jewelry, art, collectibles)
- Business ownership interest (if applicable, with valuation method noted)
- Accounts receivable / money owed to you
Liabilities section: Net worth calculation at the bottom. Include a column for the date. Every line item should be tied to a specific date. If you are updating this quarterly, that means you change the date header and update each value. This is also why you should keep source documentation attached or cross-referenced.
A case where the standard template fails and what to do instead
I worked with someone who owned a small business that generated roughly sixty percent of his income. The standard Personal Financial Statement Template had no proper way to handle this. He was tempted to just list the business as an asset at book value. That was wrong on two levels. First, book value is not market value. Second, lenders and courts typically do not accept unverified business valuations from the business owner alone. The workaround was creating an addendum. I had him prepare the standard PFS without the business asset line, then attach a separate business financial summary including a balance sheet, profit and loss statement, and a third-party valuation or CPA certification if available. On the main statement, he listed the business as an ownership interest with a noted valuation method. This way the document stayed clean and the supporting evidence was organized in one place instead of buried in footnotes.
Common mistakes that waste time and credibility
Using old balances. This is the single most common error. Someone pulls their mortgage balance from last January, their credit card balance from six months ago, and their investment value from tax documents filed in April. If the date on your statement doesn't match the statement date, every number under it is suspect. Listing gross value instead of equity. Your house is worth $400,000, but you owe $280,000 on the mortgage. The asset value is $400,000. The liability is $280,000. Do not net them together on the asset side. Keep them separate. It makes verification easier and prevents confusion when the reviewer checks your debt-to-income ratio. Omitting debt. People forget small balances. A $500 medical bill from two years ago. A $3,000 personal loan from a relative. An old cell phone contract that rolled into a personal line of credit. Omissions show up during verification and they look worse than honest inclusion.

Inflating personal property. This is where people damage their credibility the most. There is no independent verification for your collection of vintage guitars or mid-century furniture. If the number is aggressive, the whole document gets questioned. Use conservative estimates and be prepared to justify them if asked.
When a template is not enough
For basic personal tracking, a spreadsheet template works fine. If you are submitting this for a mortgage over half a million dollars, business acquisition, or legal proceeding, a spreadsheet is insufficient on its own. You need supporting documents that match every line item. Bank statements, brokerage confirmations, mortgage payoff letters, vehicle valuation printouts, and in some cases CPA or attorney certifications. A template can save you about an hour compared to building the structure from scratch. But the real time investment is gathering and verifying the data underneath it. Plan for two to four hours for a straightforward financial situation. Complex situations with multiple properties, business interests, or international accounts can take significantly longer.
Where to find a working template
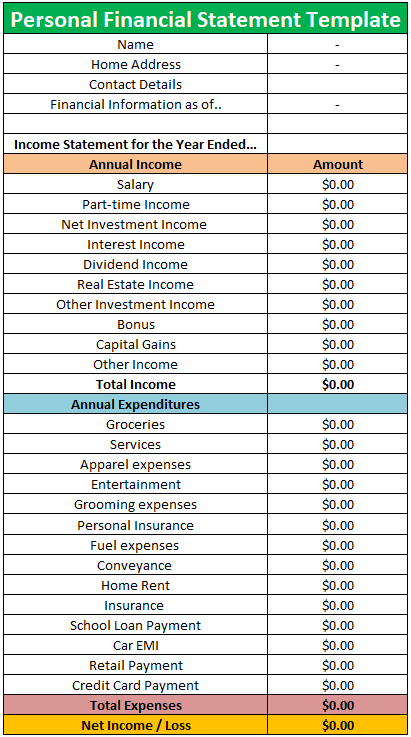
Many banking institutions provide a PFS template in their loan application packets. These are usually the most reliable because they match what the underwriter is expecting. The Federal Reserve also publishes a standard personal financial statement form (Form FR 2052) that is widely accepted in financial circles, though it is designed primarily for institutional use. For personal purposes, a well-structured Excel or Google Sheets template from a reputable financial planning source will work adequately. The specific file format matters less than whether it includes the sections I outlined above and allows you to tie each value to a source document and date. If you need something you can download immediately, search for a PFS template that includes both an assets table and a liabilities table with separate columns for current balance and statement date. Avoid templates that only have two columns for total assets and total liabilities with no breakdown. Those force you to add rows later and usually result in messy, unprofessional documents.
A note on maintenance
Update your personal financial statement at least quarterly if you are actively managing wealth or preparing for a major financial decision. The annual review minimum is what most people do, but by then the numbers have drifted far enough from reality that the statement loses useful information. If you are going through a divorce, applying for a loan, or planning a large purchase, update it within seventy-two hours of any significant transaction. Outdated PFS documents cause more problems than helpful ones. The whole process is tedious but straightforward. The template gives you the skeleton. The discipline is in keeping the data current and verifiable. Everything else is just filling in the rows.