Why Most People Fail at Getting Licensed for Personal Lines
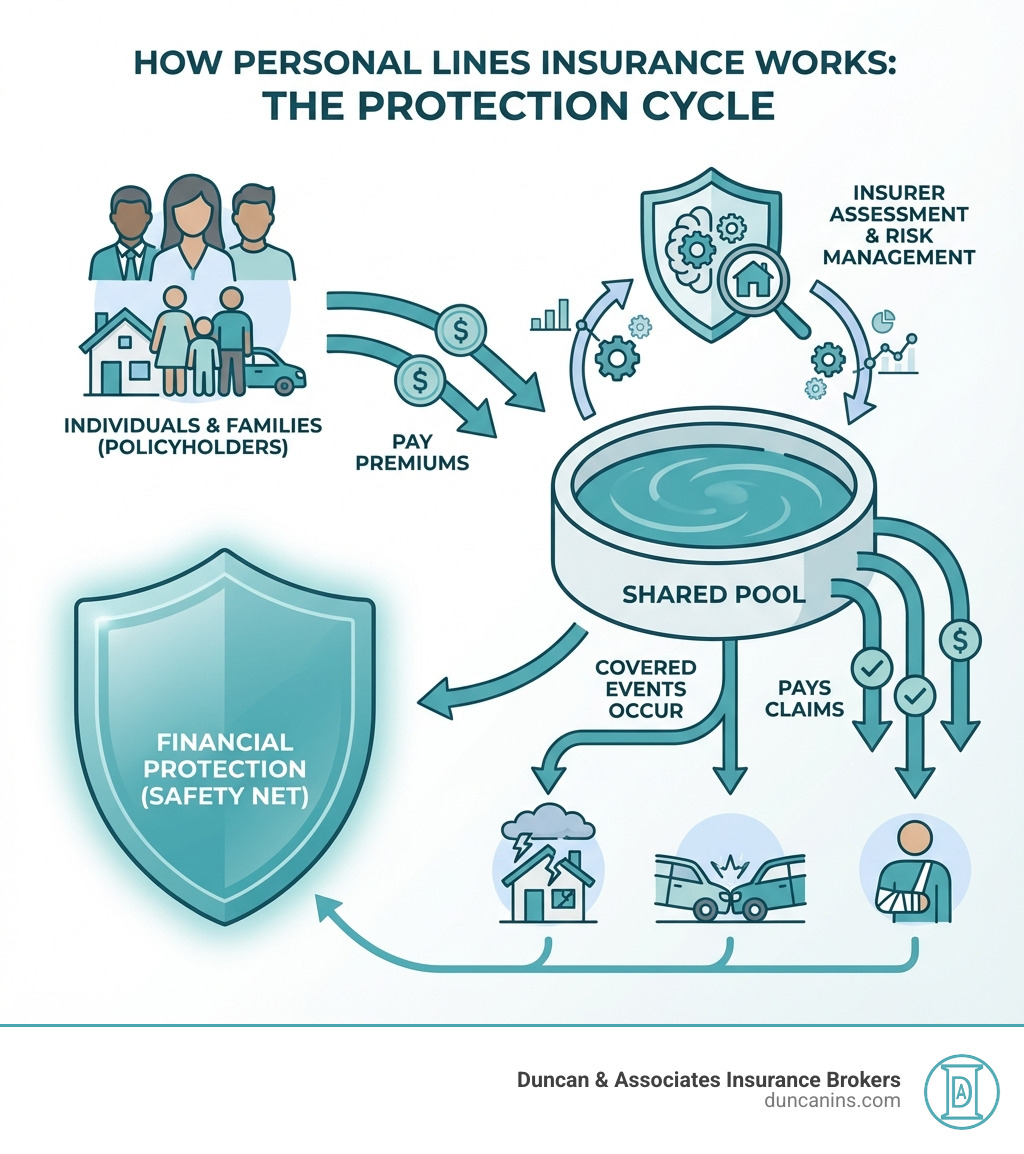
The first thing I need to say is that pre-license education is not where most people get stuck. The exam is where they get stuck. I have watched dozens of agents spend six months going through a course and then fail the state exam twice because they treated it like a compliance checkbox instead of actual preparation. Personal Lines Insurance Training covers homeowners, auto, umbrella, flood, and a handful of specialty products that most people don't think about until they need them. The curriculum varies by state, which is the first thing you need to understand before you pick a provider. Florida requires different hours than Texas. New York has its own written exam that nobody prepares for properly. California added a cyber liability section last year and most study guides still ignore it.
Choosing the Right Personal Lines Insurance Training Path
I've gone through this enough times to know what actually moves the needle. Here is the practical breakdown. You need to figure out your state's requirements first. Most states require between 20 and 40 hours of pre-license education. Some require a specific brand-approved course. Ohio lets you take anything from an approved provider. Illinois is stricter about in-person classroom hours. Check your state DOI website before you spend a single dollar on a course. I wasted about two hundred dollars once taking a course that wasn't accepted because I didn't verify approval first. For the actual training, you have three main options. In-person classroom courses, live online courses with a real instructor, and self-paced online. The self-paced ones are cheaper, usually between eighty and two hundred dollars. Live online tends to run a little more but the interaction matters more than people realize. I recommend live online over self-paced if you can swing it. The reason is simple. When you hit a question about dwelling coverage options and you have no one to ask, you either spend twenty minutes scrolling through a textbook or you ask someone who has done this before and get the answer in thirty seconds.
Most major providers like pre-license hours toward your continuing education later. That is a small thing but it adds up. AmeriCorrespondingly, several carriers offer paid training programs for new agents if you sign a contract with them. You give them exclusivity or a minimum production requirement and they fund your license prep. This is worth looking into if you already know which carrier you want to work with.
Get the Full Details
What the Actual Exam Tests
The licensing exam for personal lines is mostly multiple choice. You are looking at roughly 75 to 100 questions depending on the state. Passing score is usually around 70 to 75 percent. The questions are notoriously dry and a lot of them are wordy scenario-based items that make you read three paragraphs to answer a question that really just asks one simple thing. The biggest topics are property coverage forms HO-1 through HO-8, auto liability and physical damage coverage,-uninsured motorist rules, and standard policy exclusions. Then there are the trickier areas that most candidates barely touch. Replacement cost versus actual cash value calculations. Deductible applications when there are multiple losses in one policy period. Subrogation rights and how they work across different policy types. Misrepresentation clauses and when they void a policy. Here is a specific example from my own experience that most people don't learn in their course. I had a claim come in where a homeowner filed under their HO-3 for water damage from a burst pipe. The adjuster denied it citing the mold exclusion. The agent on the other side pushed back hard. The issue was that the original damage was covered but the resulting mold was excluded under standard HO-3 language unless the insured took reasonable steps to mitigate. The workaround I used was pulling the actual policy declarations page and endorsement schedule, confirming the insured had a water backup endorsement, and showing the adjuster that the mitigation efforts documented in the adjuster's own report met the policy's reasonable care requirement. The claim was eventually approved for both the water damage and the mold remediation. That level of policy-level thinking is not tested on the exam but it is what the job actually requires. A good training program will at least hint at this. Most won't.
Study Strategy That Actually Works
Most people study wrong. They read the material passively and then take a practice test. That is not studying. That is confirmation bias. You need active recall. Here is what I tell people. Take a practice test before you even open the book. You will score terrible. That is the point. It shows you exactly what you don't know. Then you study only the things you missed. Do not read chapters you already understand. Read every chapter in the textbook, make summary notes in your own words, and then take another practice test under timed conditions. Repeat until you are consistently scoring 80 percent or higher on practice exams. The number 80 is not arbitrary. If you score 80 on practice tests and the passing grade is 70, you have enough buffer for the actual exam day anxiety and tricky wording. I also recommend writing out the coverage forms from memory. HO-3, HO-6, DP-1, DP-2, DP-3. Write what each covers, what each excludes, and the key differences between them. I did this once for the auto section and drew out the entire liability coverage triangle with bodily injury per person, bodily injury per accident, and property damage per accident. Doing it by hand forces you to actually know the structure instead of recognizing terms when you see them on a multiple choice test.
Common Pitfalls That Cost People Retakes
The most common mistake is underestimating the calculation questions. You will need to do basic math. Premium splits between multiple drivers. Deductible applications. Coinsurance penalties on commercial floater policies even in personal lines exams. Loss payoff calculations with actual cash value depreciation. These are not intuition questions. You need to practice the actual arithmetic. Another pitfall is not understanding policy endorsements. The base HO-3 is one thing. But an HO-3 with a scheduled personal property endorsement, a water backup endorsement, and a personal injury liability endorsement is functionally a different product. Exams test these combinations. If your training course skips endorsements, you are walking into the exam blind on a significant portion of the questions. Time management during the exam is also a real issue. The questions are long. Some candidates run out of time because they read every word of every scenario. You need to read the question first, then the scenario. Most of the scenario text is noise designed to slow you down.
What Happens After You Pass
Getting the license is only the beginning. Most new agents struggle in their first six months because the licensing exam does not prepare them for selling. There is a massive gap between knowing what an HO-3 is and explaining to a homeowner why they need it and how much it will cost them. The best thing you can do after passing is get mentored or shadowed by someone who has closed real policies. Watch how they present coverage options. Listen to how they handle objections. The exam teaches you to pick the right answer. The job requires you to explain why that answer matters to a person who does not care about insurance until something goes wrong. State continuing education requirements typically run 24 hours every two years with ethics and fraud components. Some states require specific personal lines CE credits. Keep track of your deadlines. Missing CE makes your license inactive and you cannot sell while inactive. That is an easy thing to mess up when you are focused on production.
Where to Find Approved Courses
Search your state Department of Insurance website for pre-license education providers. Most states maintain a public list. Thoroughly verified providers include pre-license divisions from major carriers, independent agencies that run their own training programs, and national online providers like ASPP, prepic, and Kaplan. Prices vary widely. Don't just pick the cheapest one. Check reviews from actual test-takers in your state. A cheap course that doesn't align with your state exam format will cost you more in retake fees than a decent course ever would. Some states now offer expedited or hybrid pathways. Arizona and Utah have shortened the pre-license hour requirements recently. If you are licensed in one state and want to cross-license, look into reciprocal agreements before redoing the full education. Some states accept your existing license with just a law course or a short addendum module. The training process is straightforward if you treat it seriously. Pick the right course for your state, study actively, practice the math, understand endorsements, and then focus on bridging the gap between exam knowledge and actual client conversations. The hardest part is not the exam. It is staying licensed and building enough book of business to make the effort worthwhile.