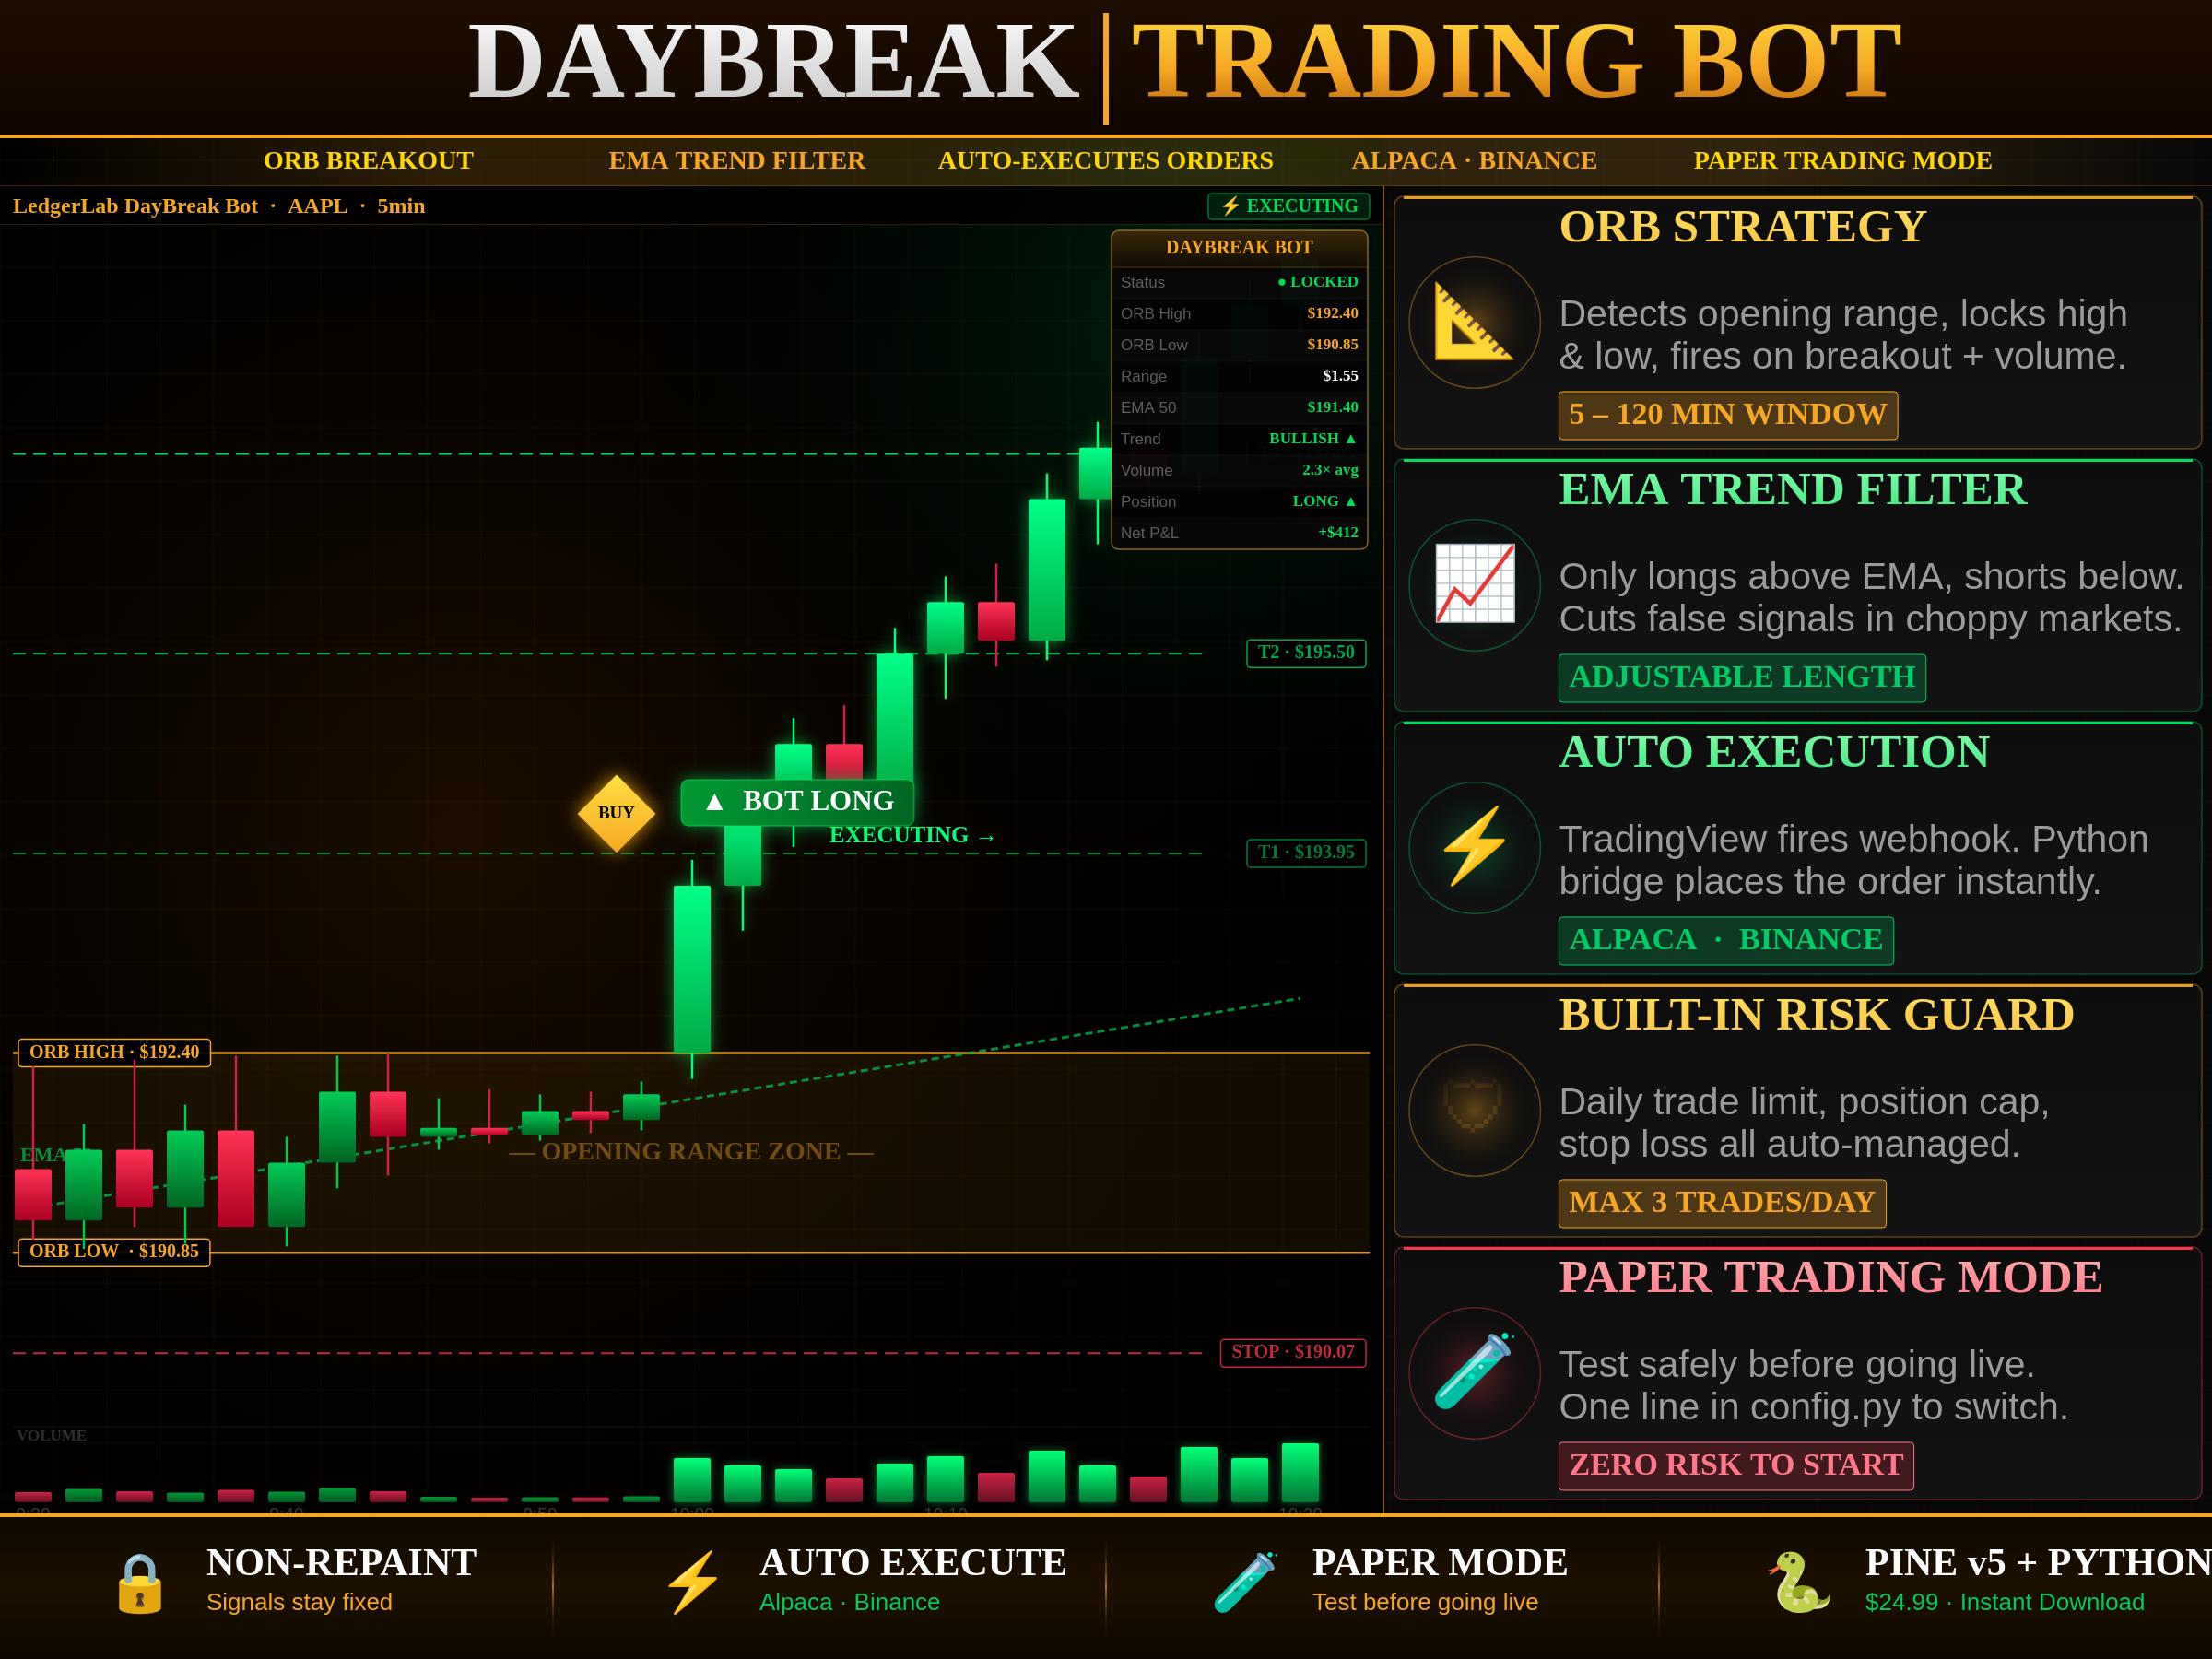
Getting a Pine Script Trading Bot to Actually Work
Most people building automated trading systems on TradingView hit the same wall within the first few days. They write a strategy, backtest it, see 400% returns, and then try to connect it to a broker and watch it lose money on live trades. The gap between backtest and reality isn't a mystery. It's usually one of three things: repainting, lookahead bias, or the strategy doing something on bar close that you didn't realize it was doing. I spent about six months trying to get a Pine Script Trading Bot to behave consistently across different timeframes. The first version I built looked like a money printer in the strategy tester. It used a combination of RSI and a custom moving average crossover. Clean entries. Tight exits. Beautiful equity curve. When I ran it on a demo account through a webhook connection to my broker, the first week wiped out 18% of the account. The problem was the lookahead bias from using request.security on a lower timeframe without setting the lookahead parameter correctly. The script was effectively seeing future bars and making decisions based on data that wouldn't have been available at the time of the trade.The fix was straightforward but not obvious if you've never dealt with it before. You have to set lookahead=barmerge.lookahead_off on every single request.security call, and you also need to pass gaps=barmerge.gaps_off if you're accessing data from bars that might not exist yet. Without those two parameters, your bot is always going to be lying to itself in the backtest. Most examples you find online skip this entirely because the people writing them never tested their strategies against live execution. Pine Script is a data visualization and analysis language first, and a strategy engine second. It runs inside TradingView's environment, which means it has access to all the chart data but no direct path to your brokerage account. If you want actual trade execution, you need a bridge. Webhooks are the most common approach. You set up a webhook endpoint on a server, your Pine Script sends a POST request when a signal fires, and that server places the order through your broker's API. This adds latency, complexity, and a new failure point that doesn't exist in the backtest. The backtest engine does a few things that will trip you up if you're not paying attention. Strategy exits on bar close by default. If your entry condition triggers during the bar, your strategy won't enter until the next bar opens. This is actually a feature, not a bug - it prevents you from entering on incomplete data. But it also means your backtest fills are always one bar behind your signals. On a 1-minute chart, that's negligible. On a 1-second chart, it's catastrophic. There's a calc_on_every_tick parameter you can set to true, but it changes how the backtest calculates your entries and exits, and it makes the backtest significantly slower without fixing the fundamental execution gap.
Another thing that catches people off guard is how Pine Script handles partial fills and position sizing. When you use strategy.position_size, it tracks your position in contracts or lots, not dollar value. If you're trading a volatile asset and your stop distance varies between signals, your actual risk per trade will vary too. A common workaround is to calculate your position size based on a fixed dollar risk and then convert that to contracts using the current stop distance. You do this with a simple formula: position_size = (account_balance * risk_percentage) / stop_distance_in_points. Put that in a function and call it before every strategy.entry, and your risk stays consistent across all signals. I ran into a specific problem with a bot I was running on the 5-minute timeframe that would sometimes generate two entries on the same bar. The entry condition was based on a crossover of two EMA periods, but because I was also checking for a volume filter that reset every bar, the conditions would align in a way that triggered strategy.entry twice before the first order had time to fill. The workaround was adding a if strategy.position_size == 0 guard before every entry call. Simple, but easy to forget when you're juggling multiple entry conditions.Building the Bot Without Breaking It
Start with a strategy, not an indicator. People often build indicators first, test them visually, and then convert them to strategies. The problem is that indicators run on every tick and can produce signals that change after the bar closes. Strategies with calc_on_bar_close=true (the default) only evaluate conditions at the end of each bar, which is what you want for backtesting. When you convert an indicator to a strategy, you need to account for the fact that your signal generation window just shrank significantly. What looked like 20 good trades on an indicator might be 6 when the strategy evaluates at bar close. When you're ready for live execution, the webhook approach requires a few components. You need a VPS or cloud server running continuously, a webhook receiver script, and your broker's API credentials. The Pine Script side just needs a strategy.order() call wrapped in an input.bool toggle so you can turn signals on and off without redeploying. Use request.send() to send the webhook. Here's the pattern: if strategy.position_size == 0 and buy_signal
request.send(webhook_url, message=str({"action":"buy","symbol":syminfo.ticker,"price":close}))
Backtest thoroughly before connecting anything to a broker. Run the strategy on at least 3 years of data across 2-3 different markets. If it only works on one market or one time period, it's overfit. The backtest should show consistent performance across different market conditions, not just a flat line of wins during a bull market. Track your max drawdown, your Sharpe ratio, and your profit factor. If any of those look suspiciously good compared to similar published strategies, assume you're overfit until proven otherwise. The biggest limitation of Pine Script Trading Bot is that you can't combine conditions across multiple timeframes cleanly. request.security() works, but it introduces gaps and lookahead issues that are hard to debug. If your strategy needs a 4-hour trend filter and a 15-minute entry signal, you'll spend more time fighting the function than building the actual logic. In those cases, it's often better to build the strategy entirely in Pine Script using a single timeframe and approximate the higher timeframe data with built-in functions like timeframe.change() or to move the entire strategy to Python with ccxt and Binance/Kraken/other broker APIs.
Get the Full Details