Why I switched from spreadsheets to a planner and what actually happened
I spent years running my personal finances through Google Sheets. Rows of categories, conditional formatting, pivot tables for the annual review. It looked impressive and it broke constantly. Then I discovered the Planner For Finance Minimalist approach and basically stopped maintaining anything that resembled a financial dashboard. The core idea is stupidly simple. Pick one page per month. Write down your fixed income, your fixed expenses, and one line for everything else. That's it. No sub-categories, no rolling averages, no automated calculations. The whole system fits on three pages of a physical notebook and takes roughly ten minutes each month to set up. The real shift isn't the tool. It's the psychological friction. When you're filling out a paper planner, you actually notice every dollar. A spreadsheet lets you hide numbers behind formulas and glance at a green cell. A planner forces you to write the number by hand. I noticed my coffee spending jumped 40 percent in three months just because I had to physically write each transaction instead of typing it into a cell that rounded things to two decimal places without blinking.
Setting Up a Planner For Finance Minimalist System
Start with whatever you have. A regular A5 notebook, a dot grid journal, even the back of an envelope if you don't want to buy anything. The method matters more than the product. Here's the structure I use and have used for about two years now. At the top of the page, write your total monthly net income. One number. Below that, list your fixed expenses in this order: rent or mortgage, utilities, insurance, debt payments, subscriptions you can't easily cancel. These are the numbers you already know. They're the anchor. Under the fixed section, draw a horizontal line and write "variable" below it. Leave at least half the page empty for this section. This is where people usually mess up because they try to create sub-categories for groceries, dining, entertainment, transportation. Don't. One line per week for variable spending is enough. Four lines for the month. Write the total for each week as you go.
At the bottom, calculate your remaining balance. Income minus fixed minus what you've spent so far. That number tells you everything you need to know. If it's negative, you already know you overspent. If it's a positive number that feels uncomfortable, you also know that immediately without digging through fourteen columns of data. There's a reason this works that nobody talks about much. Most finance planners over-categorize because they're trying to solve a problem that doesn't exist for most people. You don't need to know whether your grocery spending went up because of produce or meat. You need to know whether your total variable spending is within a range that lets you hit your savings goal. Categories create the illusion of control while adding hours of maintenance work. The minimalist planner strips that away completely. I ran into a specific edge case about eight months in that almost made me abandon the system entirely. I had a client pay me on delayed terms, which meant my income for that month came in halfway through instead of on the first. My planner showed a negative balance for the first two weeks even though I was fine financially. The system felt like it was lying to me. What I did was add a separate line at the very top called "pending income" and only moved it to the income total once the money actually cleared. This kept the planner honest without adding any real complexity. The pending line stays blank until the cash hits the account, then it gets written in and the rest of the math adjusts automatically.
Get the Full Details
Another thing that surprised me is how limited this method actually is. The planner for finance minimalist approach will fail you in a few specific situations. If you have more than five fixed expenses, the page gets cramped and you lose the visual clarity that makes the system useful. If you're tracking investments, crypto, or multiple income streams, the single-page model doesn't scale. If you need detailed records for tax purposes, a notebook won't replace organized digital receipts and statements. In those cases, a spreadsheet or dedicated app like YNAB or Monarch Money is genuinely better. This method is designed for simple personal budgets, not financial complexity. The monthly review is where most people either commit to this or quit. Every month, look at the last week's remaining balance against the same month from the previous year. Not against a budget target. Against reality. If your remaining balance is going up quarter by quarter, you're improving even if you don't know exactly where the money went. That's the point. Knowing direction matters more than knowing details. One more practical note about the physical side of things. Buy a pen you actually enjoy writing with. This sounds ridiculous but it matters more than you'd expect. If writing in your planner feels like a chore, you'll skip weeks and then abandon the whole system. A decent gel pen or a fountain pen you like makes the ten-minute monthly setup something you do without resistance. I keep the planner on my desk, not hidden in a drawer, so I see it every day and the numbers stay present rather than becoming an abstract monthly task.
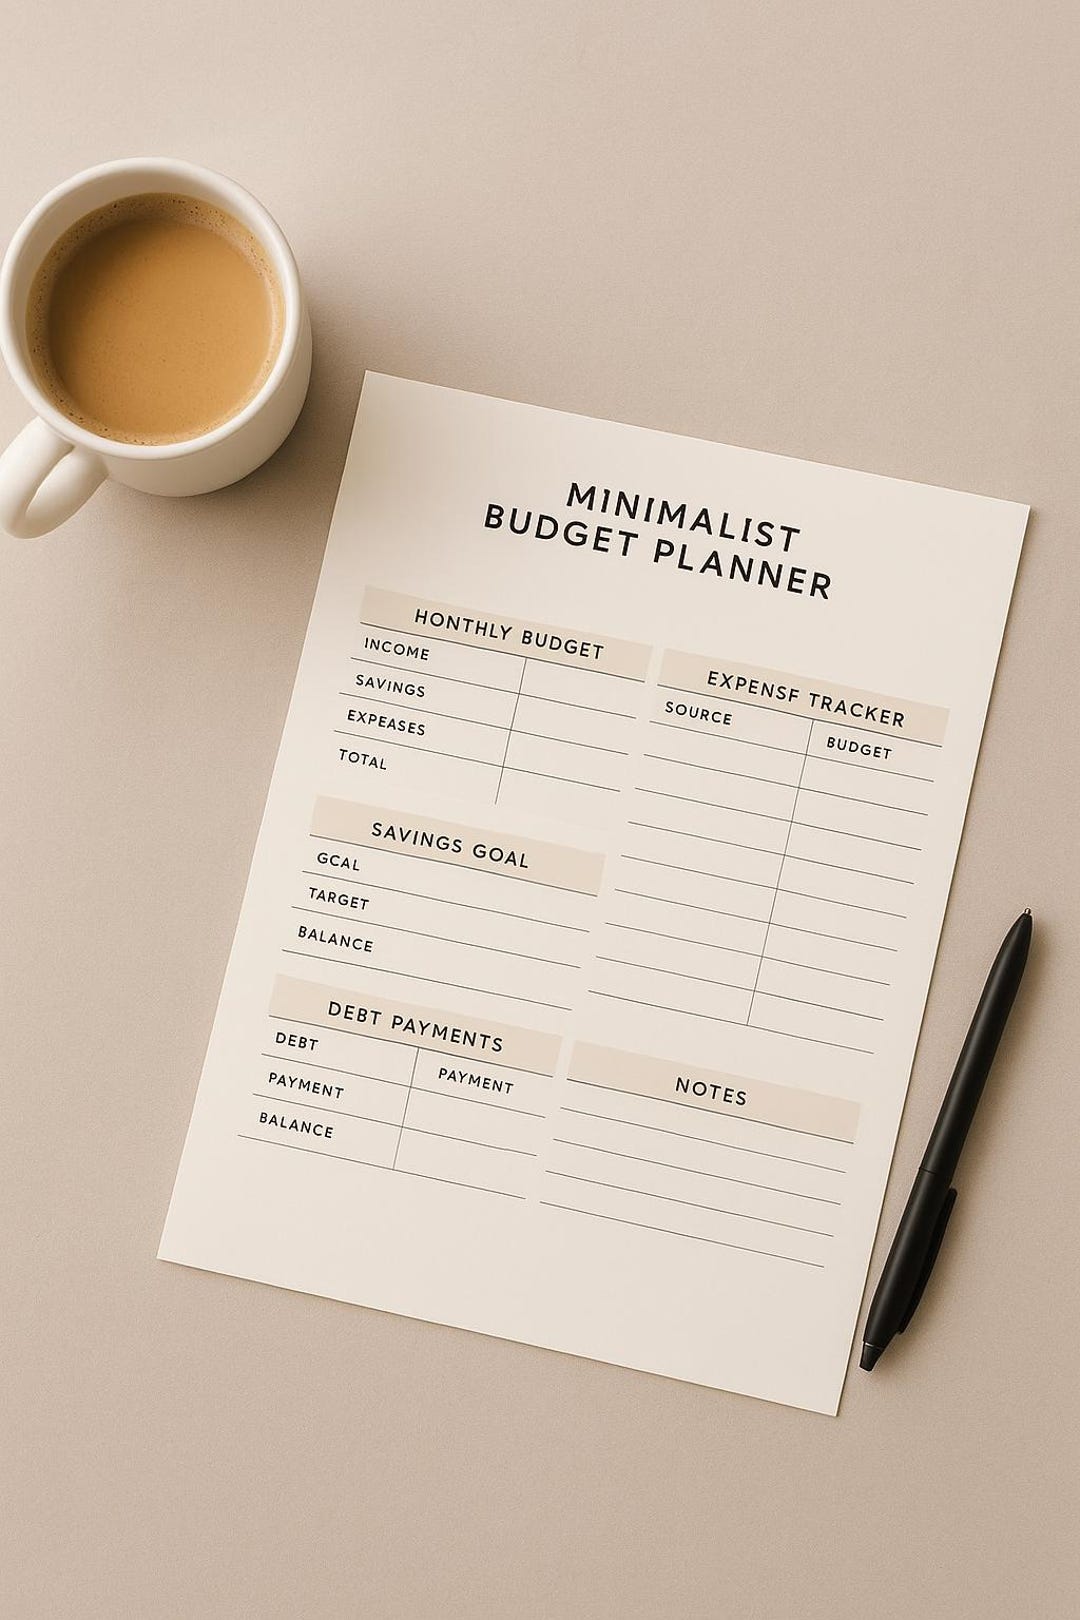
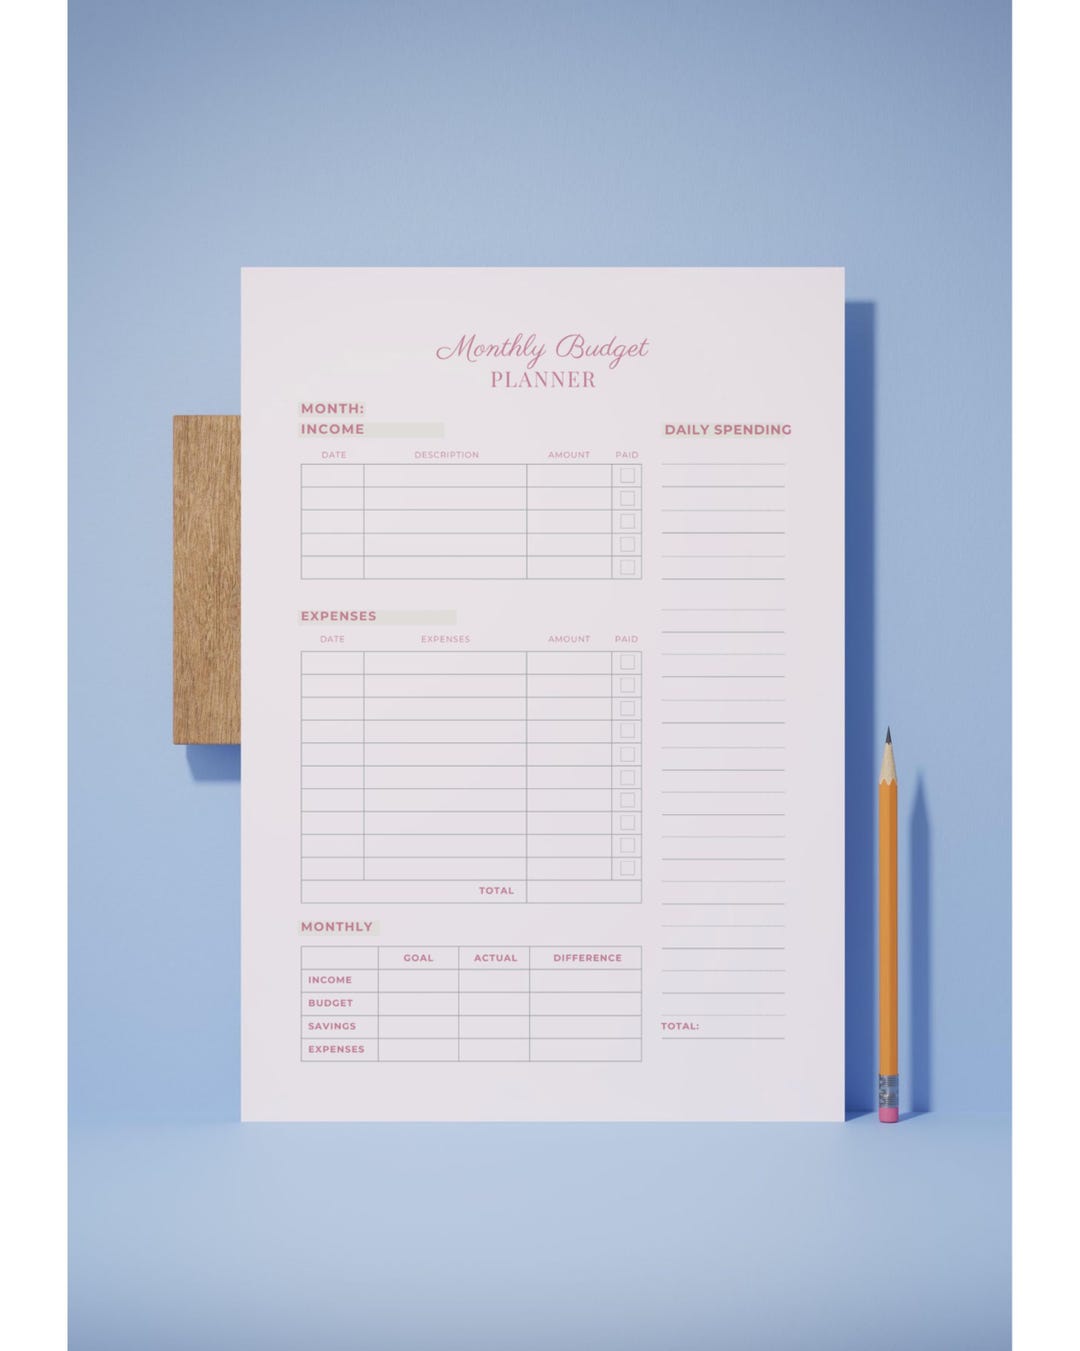
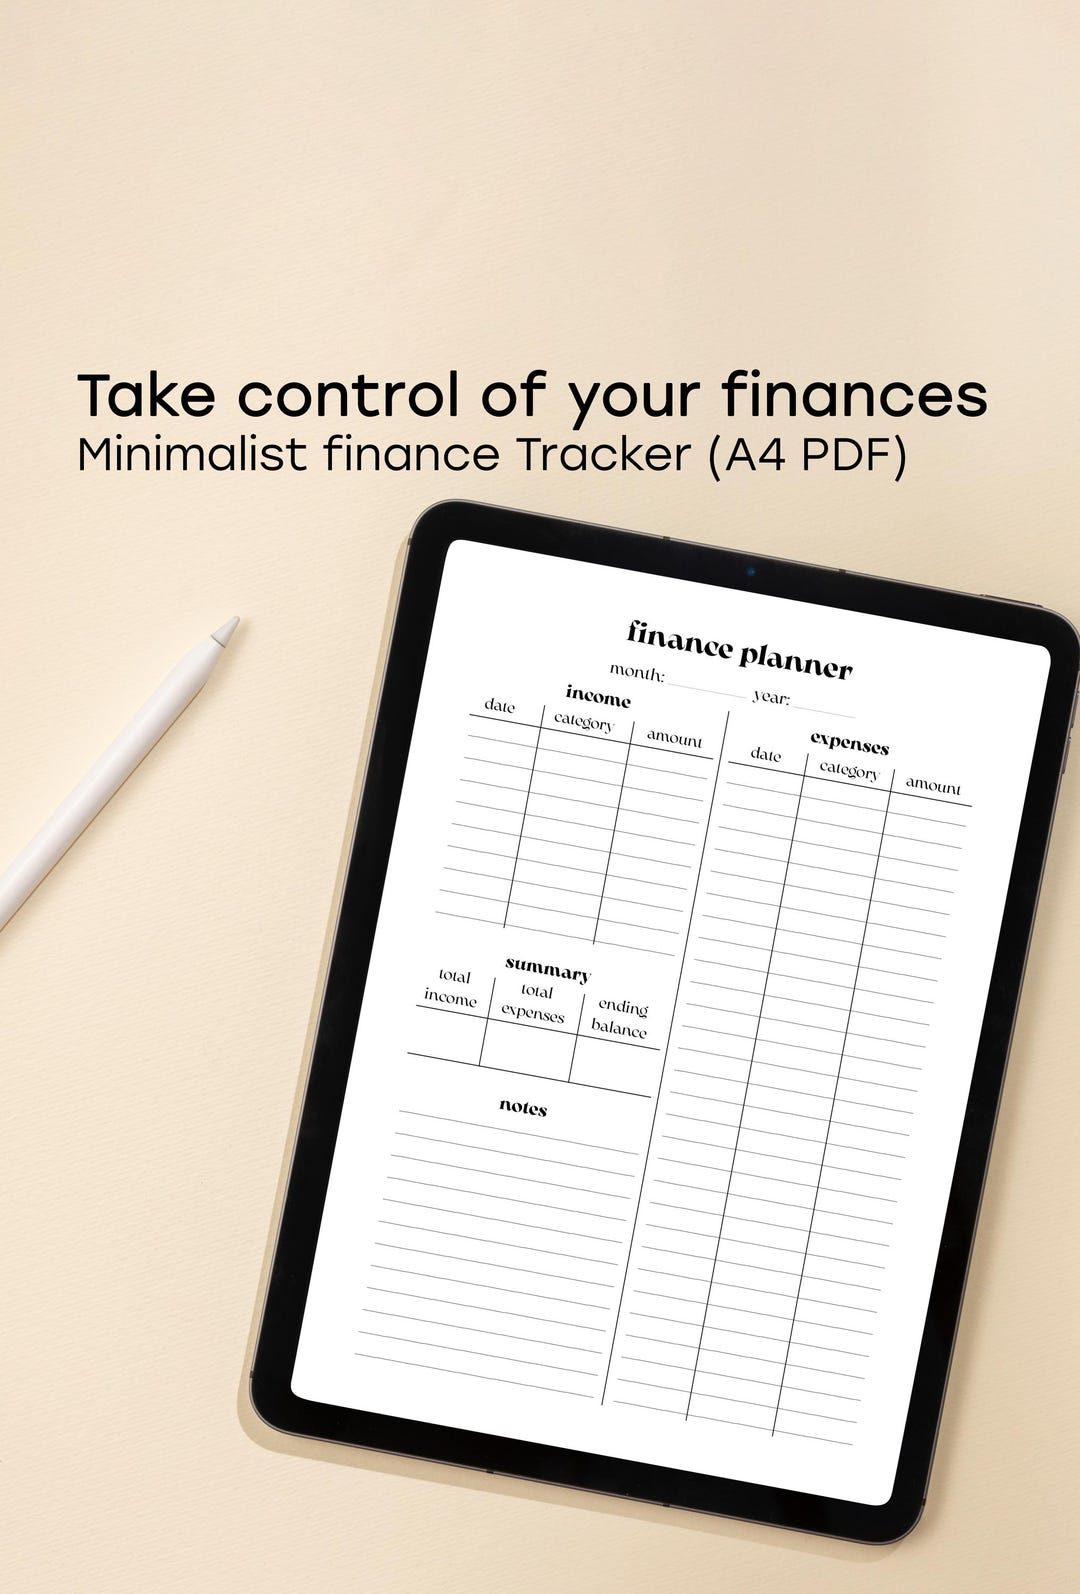
If you want to download a template to start with, there are free printable versions of this layout available on a few personal finance blogs. Search for "minimalist monthly finance planner PDF" and you'll find several. Most are basic grids with the income, fixed, and variable sections already laid out. Some include the pending income line I mentioned, most don't. The template is only a starting point. The system works because you use it, not because the page looks clean.
What I wish I'd known before starting
The biggest mistake beginners make is treating the first month like a test run instead of the actual system. Fill out the planner for finance minimalist exactly the same way every single month. Don't add categories when you feel like you're missing information. Don't switch to digital mid-month because paper feels inconvenient. The method earns its simplicity through consistency, and consistency requires discipline in the first thirty days more than anything else. The other thing is that you'll feel blind at first. Removing detail feels like removing safety. Give it six weeks before judging whether it works. Most people report that around week four or five, they start feeling the budget in their head without looking at the page. The numbers become intuitive. That's when the system actually pays off, and it pays off in hours of time you stop spending on financial maintenance rather than in dramatic improvements to your net worth. Though the net worth effect is real too, it's just a side benefit of not constantly underestimating where your money goes.