Working with Polaris Preferred Solution Variable Annuity
Most people asking about this product are trying to figure out whether it fits a client's portfolio or whether their current implementation is set up correctly. The reality is it's a variable annuity product from Polaris Insurance Services, designed for institutional and high-net-worth distribution channels, and it comes with a layer of complexity that doesn't show up in the marketing brochure. I've sat through enough case files and application processes to know where things typically go sideways.Polaris Preferred Solution Variable Annuity: What It Actually Is
The Polaris Preferred Solution Variable Annuity is a deferred variable annuity with a suite of optional benefit riders available for purchase. It's sold through independent agents, general agents, and some wirehouse channels. The underlying investment options typically consist of a selection of sub-accounts tied to mutual fund-style portfolios. You choose how the premiums get allocated among those sub-accounts, and the account value fluctuates accordingly. That part is straightforward. The complexity shows up in the rider elections, the surrender charge schedule, and the tax treatment depending on how the product is funded and distributed. I've seen producers skip reading the surrender charge table and then get surprised when a client needs liquidity in year three and takes a hit they didn't expect. Don't be that producer. The product is registered with the NAIC and issued by Polaris Life Insurance Company. It goes through the standard ISO and state-specific filing process, which means the exact terms can vary slightly by state of residence. Always verify the prospectus and disclosure documents for the specific state you're working in.
Setting Up a New Policy Correctly
I'll walk through what actually matters when you're putting a Polaris Preferred Solution Variable Annuity in place, starting from the point where a client has already decided to proceed. The first thing most people get wrong is the premium payment method. You can fund it with a single premium or flexible premiums, but the tax implications and the surrender charge structure change depending on which path you choose. A single premium transaction gets the surrender charge applied to the entire amount upfront and it tapers over time, usually seven to ten years depending on the contract terms. With flexible premiums, each premium payment can be subject to its own surrender charge period, which compounds the problem if the client keeps injecting capital. I've seen clients who were adding money every year and were effectively locked in permanently because they never let the first wave of premiums sunset their surrender charges. Before you even touch the application, nail down the beneficiary designations and the distribution election. Polaris allows for lifetime income benefits through certain riders, and the election of how those benefits trigger matters more than most producers realize. If the client wants the guaranteed minimum withdrawal benefit, for example, the benefit base is calculated differently depending on whether they elect a percentage of the account value or a percentage of the premium payments. I had a client once where the agent didn't understand this distinction and the numbers on the illustration looked completely different from what the client actually ended up with. It took about forty-five minutes of pulling the actual contract language to sort out, and the client was not happy.
Rider Selection That Doesn't Waste Money
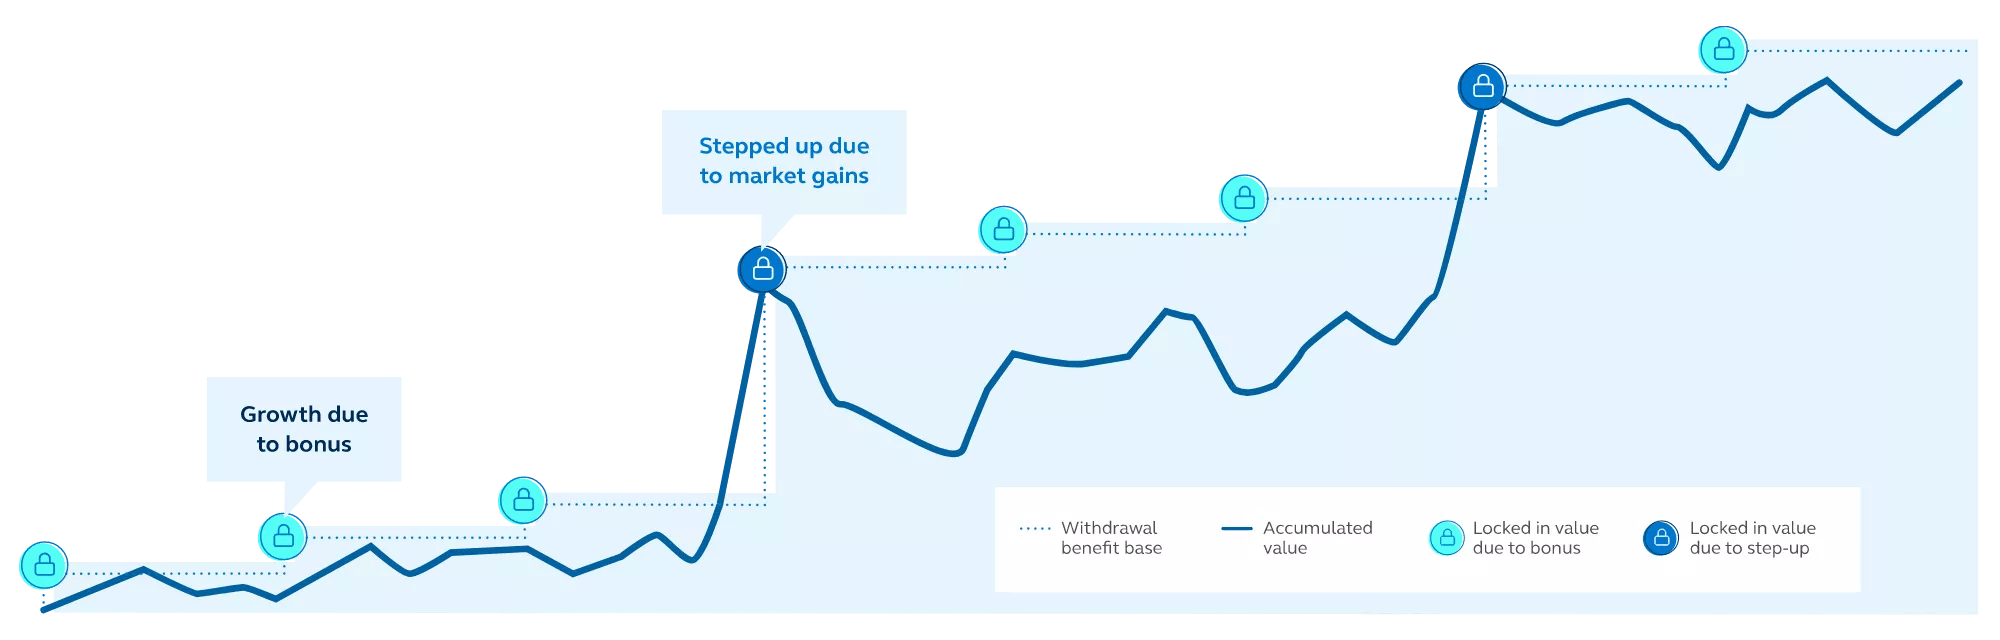
This is where I see the most avoidable mistakes. The rider options on Polaris Preferred Solution Variable Annuity include GMWB, GMDB, and sometimes GMMB depending on the filing. Each rider comes with a fee, usually expressed as a basis point charge against the account value on an annual basis. The fees are modest in isolation but they add up, and more importantly they erode the compounding that makes variable annuities worthwhile in the first place. Here's a counter-intuitive point that most people miss: the GMDB rider on Polaris Preferred Solution tends to have more value in later years of the surrender charge period when the account value has declined from market downturns. If your client has a high risk tolerance and a long time horizon, the GMDB may be redundant coverage because the death benefit typically already exceeds the account value in most market scenarios without the rider. I've recommended dropping it in those cases and reallocating that basis point cost into a more suitable investment in a taxable account. The math usually works out in favor of the client over a fifteen to twenty year period. The GMWB rider is the one that actually makes sense for certain clients. Specifically, clients who are approaching or in retirement and want a known stream of income that won't go down when the market goes down. The catch is that the benefit base growth during the accumulation phase varies by rider election, and if you elect the step-up feature, the fees are higher. I always run the numbers both ways with the client before they commit. A typical comparison might show that the no-step-up version of the rider costs roughly half the basis points but provides a noticeably lower lifetime income potential. Which one is better depends entirely on the client's age, health, and other sources of guaranteed income.
Get the Full Details

Common Pitfalls When Processing These Contracts
One thing that comes up regularly is the assignment of ownership. If the policy is being assigned to an irrevocable trust or if there's a change of ownership involved, the processing timeline extends significantly. Polaris typically requires additional documentation and underwriting review in these cases. I've had situations where the client needed the policy transferred within sixty days for estate planning purposes and it took ninety-five days to complete because nobody flagged the ownership change in the initial application. Build in extra time if there's any ownership complexity. Another issue is the interaction between the annuity and other products in the client's portfolio. I had a client who was heavily invested in a taxable bond fund and then bought a Polaris variable annuity with a similar fixed-income sub-account allocation. The problem wasn't the annuity itself. The problem was that they were double-taxing the same income stream conceptually, paying ordinary income tax on the annuity distributions while also dealing with the bond fund's taxable interest. It wasn't a terrible decision overall, but it was worth discussing before the money moved. Sometimes just identifying the overlap is enough for the client to reconsider the allocation. The most painful issue I've encountered involves the annuitization election. Once a client annuitizes and starts taking lifetime income payments, the contract is essentially locked. There's no going back. I've seen this happen when a client thought they were setting up a withdrawal strategy that mimicked income but was actually structured as annuitization. Make absolutely sure the client understands what they're committing to before you submit that election. If there's any doubt, keep the policy in the accumulation phase and revisit the decision later. It costs nothing to wait.
Where This Product Falls Short
The Polaris Preferred Solution Variable Annuity is a solid product for the right client, but it's not a universal solution. The sub-account selection is narrower than what you'd find on some competing platforms, which matters if the client has strong preferences for specific investment styles or sectors. The expense ratios on the sub-accounts can run above market average for comparable mutual fund allocations, and over a twenty-year period that difference is significant. I typically compare the total cost of ownership including rider fees against a taxable brokerage account with a similar asset allocation. More often than not, the taxable account wins on pure investment returns, though it loses on the tax-deferred compounding and the income guarantee features that the annuity provides. The product also has a surrender charge that's non-trivial for early withdrawals. If there's even a moderate chance the client will need access to the funds within the first five to seven years, a variable annuity is the wrong vehicle regardless of how compelling the income rider sounds. I've had to unwind a few of these situations where the client had an emergency and the surrender charge plus the ordinary income tax on gains made the withdrawal far more costly than a similarly structured taxable investment would have been. The liquidity profile of variable annuities is something producers should address head-on, not quietly skip over. If the client's primary goal is tax deferral on a large lump sum with no need for income guarantees or death benefit enhancements, a taxable bond fund or a municipal bond ladder might serve them better with lower costs and full liquidity. The annuity structure is the tool you reach for when the income guarantee or the estate planning component is genuinely needed, not as a default allocation for every large sum of money that comes across your desk.
Polaris Preferred Solution Variable Annuity Implementation Checklist
When you're working through a new policy, run through these items before submitting the application. First, confirm the client's state of residence and verify that the product is approved for sale in that state. Second, document the client's liquidity needs and the time horizon for the funds being placed in the annuity. Third, compare the rider fees against the specific benefits they provide for this client's situation. Fourth, establish the beneficiary designations clearly and confirm they align with any estate planning documents. Fifth, run an illustration showing multiple market scenarios, not just the base case. Sixth, ensure the client understands the surrender charge schedule and the tax consequences of withdrawal before the contract is signed. If any of these steps feel rushed, slow down. The processing time is measured in days or weeks, and a mistake made at this stage is expensive to correct later.