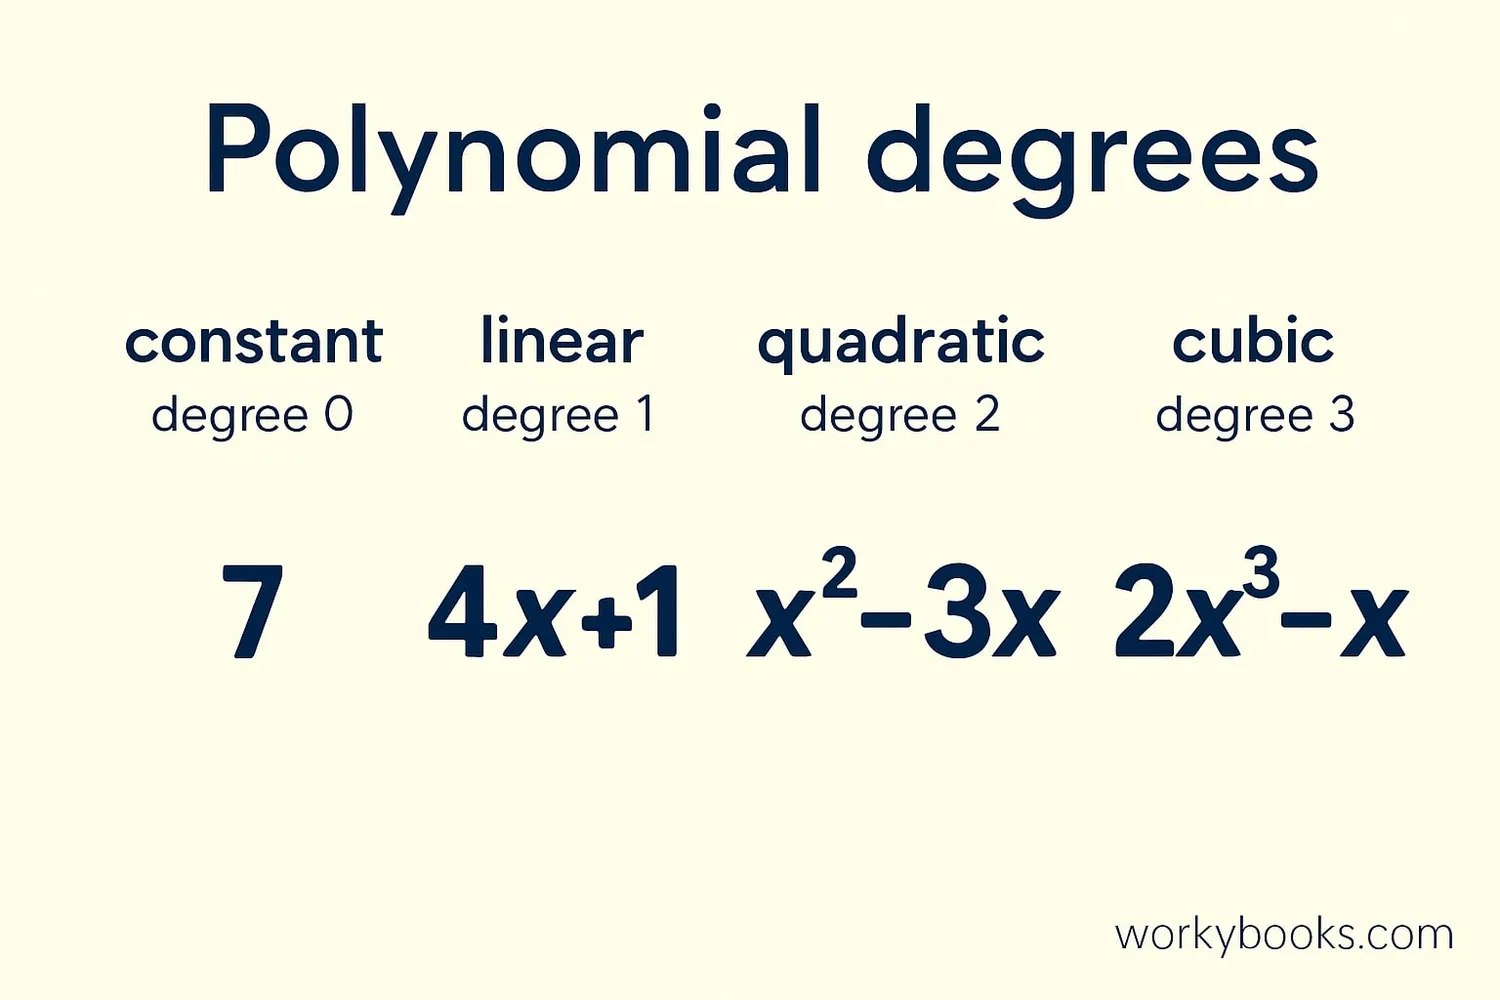
Polynomial Definition In Geometry: A Practical Look
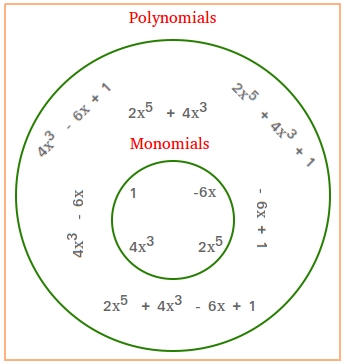
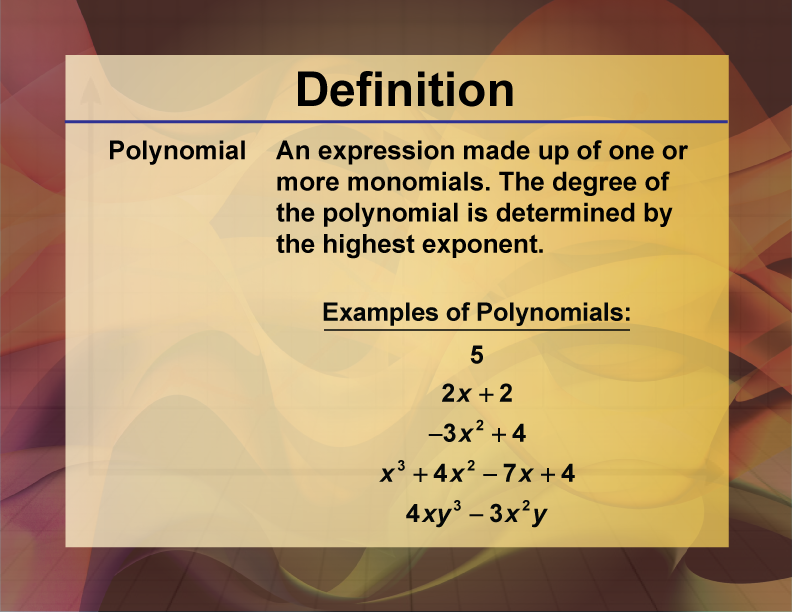
Polynomials show up everywhere in computational geometry, and not in the way most people expect. When someone asks for the Polynomial Definition In Geometry, they're usually trying to understand how curves and surfaces get represented numerically, but the gap between the textbook definition and what you actually implement is wide enough to get people into trouble. A polynomial in geometry is a finite sum of terms, each consisting of a coefficient multiplied by one or more variables raised to non-negative integer exponents. That's the dry textbook version. What matters in practice is that any polynomial curve or surface can be written as a linear combination of monomial basis functions. In 2D, a single-variable polynomial looks like f(x) = a + ax + ax² + ... + ax. In parametric geometry, you typically use two such polynomials—one for the x-coordinate and one for the y-coordinate, both parameterized by some independent variable t.
The Polynomial Definition In Geometry Explained Through Computation
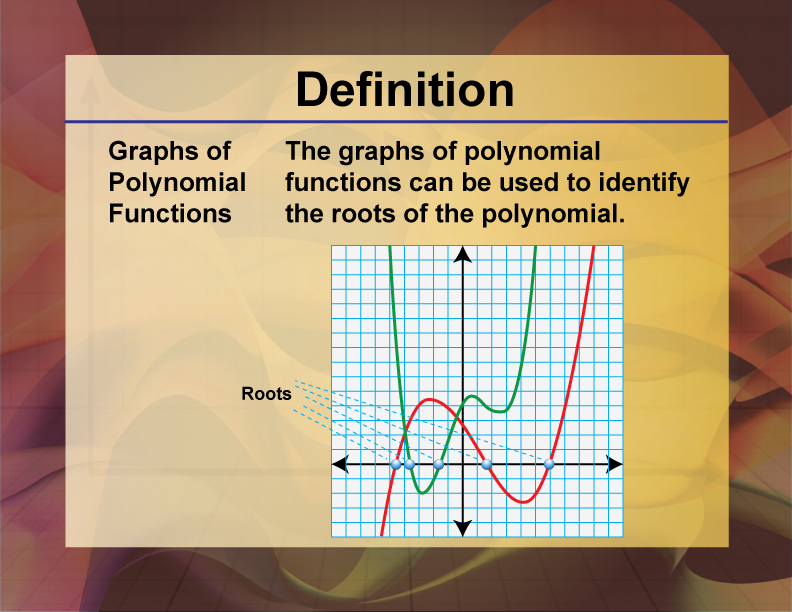
Let me explain this from the ground up because the conceptual leap from algebra to geometric representation trips people up constantly. In analytic geometry, you might describe a line with y = mx + b, which is technically a first-degree polynomial. A parabola is y = ax² + bx + c, a second-degree polynomial. But the moment you move into computer-aided design or computational geometry workflows, the polynomial definition in geometry stops being about explicit functions and starts being about parametric forms. Take a cubic Bezier curve, for instance. It's a polynomial curve of degree three defined parametrically: P(t) = (1-t)³P + 3(1-t)²tP + 3(1-t)t²P + t³P. Expand that out, and you'll find both the x and y components are cubic polynomials in t. The polynomial definition in geometry is really about recognizing that most useful curves in this space are implicitly polynomial, even when they're dressed up in Bernstein basis form or B-spline notation. I ran into this directly when I was working on a mesh generation pipeline a few years back. The task was to approximate a freeform NURBS surface with a single polynomial patch for a rendering engine that didn't support NURBS natively. Converting from B-spline basis to monomial basis is mechanically straightforward but numerically dangerous if you're not careful. I used a straightforward conversion matrix, plugged in the control points, and got a polynomial representation that looked correct on paper. When I rendered it, the surface exhibited wild oscillations near the boundaries. This is exactly the kind of numerical instability that comes from using a high-degree monomial basis—Runge's phenomenon isn't just a textbook curiosity, it shows up in production code.
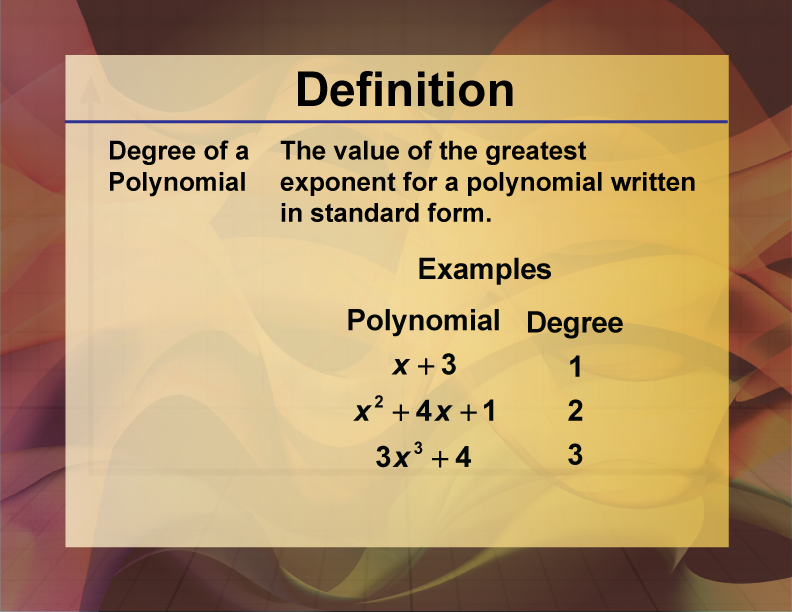
The workaround I ended up using was to switch to a Chebyshev polynomial basis instead of the standard monomial basis. Chebyshev polynomials are orthogonal on the interval [-1, 1] with respect to a specific weight function, and they distribute their mass much more evenly across the domain. In practice, this means a degree-10 Chebyshev expansion gives you significantly better numerical stability than a degree-10 monomial expansion for the same accuracy target. The conversion itself is clean—you express each Chebyshev polynomial in terms of powers of x using the recurrence relation T(x) = 1, T(x) = x, and T(x) = 2xT(x) - T(x)—and then solve a small linear system to match your original coefficients. One thing beginners consistently miss is that the degree of a parametric polynomial curve isn't always the same as the degree you'd infer from looking at it visually. If your parametric equations are x(t) = t³ and y(t) = t, the curve is actually a parabola (y = x²), which is degree two geometrically but degree six parametrically. This distinction matters enormously when you're doing operations like curve intersection or subdivision. Using the parametric degree as a proxy for geometric complexity will give you completely wrong complexity bounds on algorithms that depend on it. Another nuance that doesn't get enough attention: polynomial curves can self-intersect, have cusps, or contain isolated components even when the parameterization is smooth. A classic example is the folium of Descartes, which has a rational polynomial parameterization with a self-intersection at the origin. If you're building a geometry kernel or a collision detection system, you need to detect these pathological cases explicitly rather than assuming that a polynomial parameterization produces a well-behaved geometric object.
Get the Full Details
The main bottleneck with polynomial representations in geometry is degree. As the polynomial degree increases, the condition number of the associated linear systems grows exponentially in the monomial basis. This isn't a theoretical concern—it's why production geometry libraries almost universally avoid explicit monomial representations above degree four or five. B-splines and NURBS exist precisely to sidestep this problem while still being polynomial piecewise. If you need higher-degree flexibility, use a piecewise polynomial approach rather than a single high-degree polynomial. I've seen people attempt to fit degree-20 monomial polynomials to scattered geometric data points and then wonder why the results were garbage. A piecewise cubic with ten segments gives you far more control and better numerical behavior for essentially the same amount of computation. For practical implementation, if you need to convert between polynomial representations, the key tool is the change-of-basis matrix. Given two polynomial bases (monomial, Bernstein, Chebyshev, Legendre, etc.), there exists a unique invertible matrix that converts coefficient vectors from one basis to the other. Computing this matrix requires knowing how to express each basis polynomial from the source set in terms of the target set, which is a purely algebraic operation. Once you have the matrix, multiplication gives you the conversion in O(n²) time for degree-n polynomials. The real cost isn't the conversion itself but the numerical conditioning, which deteriorates rapidly as n grows beyond about 15 in double precision unless you're working with an orthogonal basis. If you need a starting point for working with polynomial curves and surfaces, the fundamental building block is understanding the relationship between the algebraic form and the geometric form. Every polynomial curve in geometry can be converted to the other representation, but doing so carelessly introduces numerical error that compounds through downstream operations. Keep your polynomial degrees as low as possible, prefer piecewise constructions over global high-degree polynomials, and always verify the geometric properties of your result rather than trusting the parameterization at face value.