How to Actually Build a Portfolio That Doesn't Fall Apart
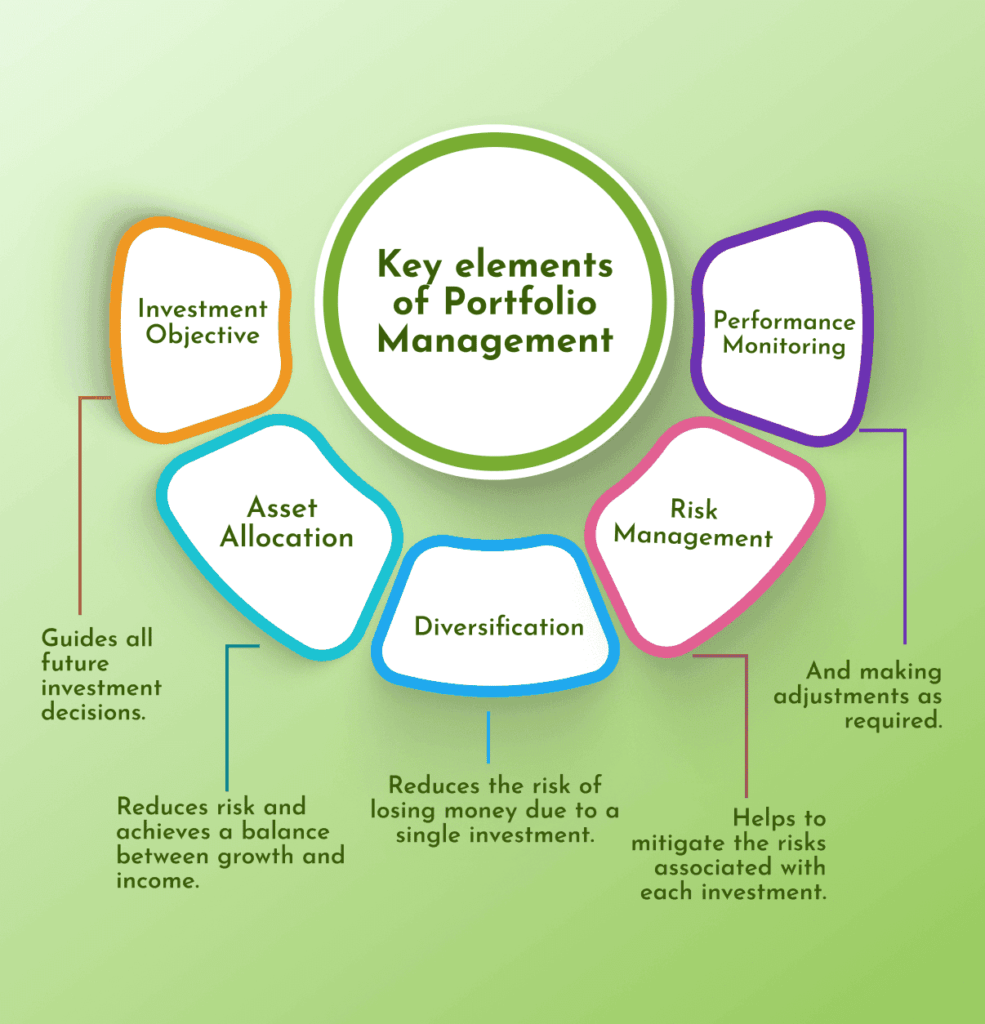
Most people approach portfolio construction by picking stocks they like and arranging them into a basket. That is a fine hobby. It is not a strategy. A real portfolio management process starts with something most retail investors skip entirely, which is deciding what return you actually need relative to the risk you are willing to absorb on days when everything looks like it is on fire. I once managed a small fund for a client who wanted aggressive growth but refused to let his portfolio drop more than 8% from peak at any point. Those two objectives are mutually exclusive in anything beyond the most boring market regimes. The stock he picked last year was down 41% year to date. He wanted to add more because it was "on sale." I ran the numbers and showed him that continuing to buy would require him to accept a potential drawdown of over 60% to hit his return target. He stopped buying. He also stopped taking my advice about the other ten positions, but at least he didn't blow up further. That is the kind of conversation you have to have.
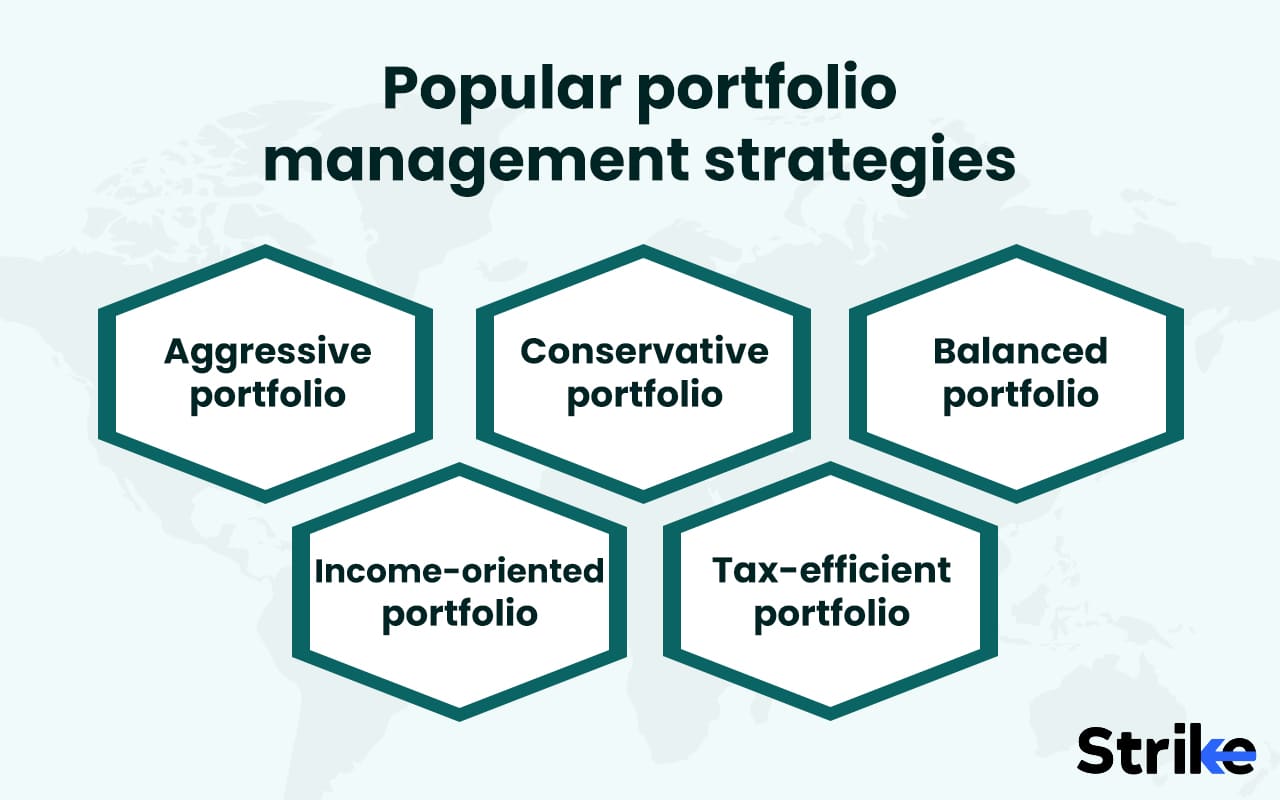
Core Portfolio Management Strategies to Consider
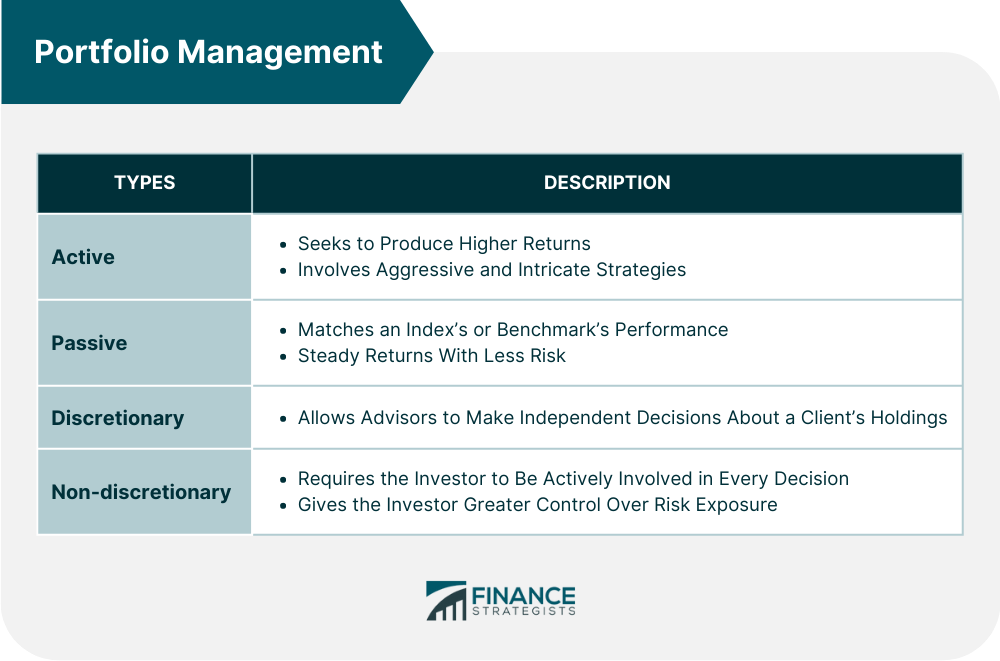
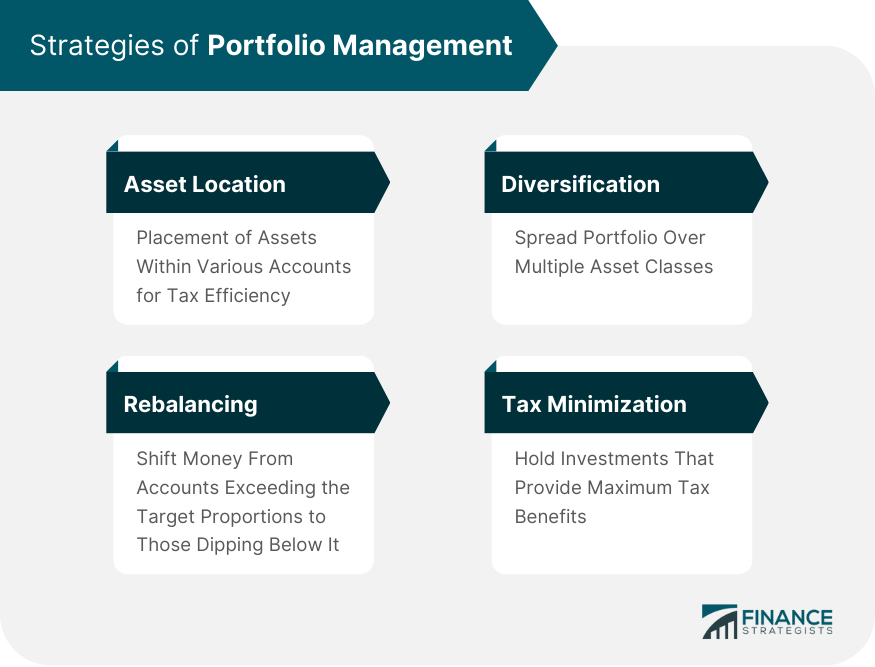
The foundational strategies fall into a handful of buckets, and each one has a real cost that most people gloss over. Strategic asset allocation means you decide on long-term target weights for major asset classes and you rebalance back to those weights on a schedule. It is the bread-and-butter approach. The assumption behind it is that markets revert to a mean over long periods and that your edge comes from discipline rather than timing. Rebalancing works well when markets oscillate. It does not work well during sustained trends in one direction, because you will consistently be selling winners and buying losers. A portfolio that is 60% equities and 40% bonds will underperform a 80/20 split during a multi-year bull market. You have to decide whether that tracking error bothers you. For most institutional mandates it does not, because the mandate is about delivering a risk-adjusted outcome, not about maximizing returns. Tactical asset allocation is where you deviate from the strategic weights based on short-term outlooks. You might increase equity exposure before a recession or tilt toward value when the yield curve is inverted. This is harder to do well than it sounds. The window where you are actually right about the macro is narrow, and transaction costs plus taxes erode the benefit fast. I see too many advisors calling tactical shifts every three months and then wondering why their clients underperform a bare buy-and-hold index by 1.5 to 2 percentage points annually after costs.
Smart beta or factor-based strategies isolate exposures like value, momentum, quality, low volatility, or size. The academic literature backs many of these, and the evidence is stronger for momentum and value than it is for the others. The problem is that factor premia are not steady. Value can underperform for a decade. Momentum can blow up in a flash crash. Low volatility portfolios can look great until rate hikes hit and everything reprices at once. If you are using factor tilts, you need to understand that you are accepting periods of painful underperformance in exchange for long-term premia. Most people quit too early. Risk parity allocates based on risk contribution rather than capital. The idea is that if bonds are less volatile than stocks, you can leverage the bond portion so that both asset classes contribute equally to portfolio risk. It sounds clever. In practice it requires borrowing, which introduces roll risk and convexity risk when rates move. During the 2022 bear market in both stocks and bonds, a traditional risk parity portfolio got hammered because the leverage made the bond leg hurt just as much as the equity leg. It is a legitimate strategy in a low-volatility, low-rate environment. It is not a magic bullet. Dynamic hedging and tail-risk hedging involve buying puts or using options overlays to protect against severe drawdowns. The cost is real. A one-year S&P 500 put option typically costs between 2% and 4% of notional value depending on implied volatility. Over a ten-year period, that expense significantly drags on returns unless a crash actually occurs. I had a client who ran this for two years and lost about 12% on the hedge premiums alone. Then the market dropped 20% in a month and the hedge paid for everything and then some. It is insurance. You pay for it until you need it. Some people never need it. Others wish they had bought more.
Get the Full Details

Core-satellite is one of the more practical approaches I have seen actually work. You put the bulk of the portfolio into low-cost index funds or ETFs to capture market returns, and you allocate a smaller portion to active bets where you think you have real edge. A typical split might be 80% core and 20% satellite. The satellite can include individual stocks, sector funds, or thematic plays. The key is keeping the satellite small enough that your active bets cannot destroy the portfolio but large enough that they matter if you are right. This is also the framework where most people fail, because they gradually let the satellite grow until it is 50% of the portfolio and they have recreated a bet with extra steps. When I run a portfolio review now, I start by asking what the liquidity needs are over the next three years. That question alone eliminates about half the strategies people think they want. If someone needs money in eighteen months, they are not running a risk parity fund. They are running a savings account with delusions of grandeur. You do not put short-term capital into illiquid strategies or leveraged ones. The math does not care about your conviction. One thing that trips up almost everyone is correlation breakdown during stress events. In normal markets, stocks and bonds often move inversely. In 2022 they both sold off simultaneously. In March 2020 everything correlated to one. The lesson is that diversification is not a permanent state you achieve by owning five assets. It is a fragile condition that requires constant monitoring. If you are using historical correlations to size positions, you are implicitly assuming the future will look like the past. That assumption has failed repeatedly over the last twenty years.
Transaction costs are another silent killer. Turnover above 30% per year eats roughly 0.5% to 1% annually when you factor in bid-ask spreads, market impact, and slippage. Rebalancing a six-asset portfolio quarterly instead of annually can add 0.2% to 0.3% in costs without any meaningful improvement in risk-adjusted returns. I shift my rebalancing from calendar-based to threshold-based when possible. If an asset class drifts more than 5% from its target weight, I rebalance. Otherwise I leave it alone. This cut my annual turnover from 28% down to about 11% on a sample portfolio I manage for personal accounts. There is no single best portfolio management strategy. The right approach depends on your time horizon, your tax situation, your liquidity constraints, and your tolerance for periods where you look stupid while the strategy is working against you. The worst thing you can do is copy someone else's allocation without understanding why it was built that way. I have seen too many people run a 60/40 portfolio because their financial advisor recommended it, without realizing that the advisor's model assumed a 7% equity return and a 4% bond return, neither of which is realistic in the current environment. Adjusting expected inputs changes the optimal allocation substantially. Running stale assumptions through a modern optimizer gives you a false sense of precision. If you are starting from scratch, pick a strategic allocation that matches your actual goals, keep costs under 0.20% annually on the core holdings, rebalance on thresholds rather than calendars, and accept that you will have stretches where your strategy underperforms while you stay disciplined. The alternative is spending three hours every month tweaking positions based on headlines, which has a very high correlation with mediocre long-term outcomes.