What Actually Happens When You Generate a Post Closing Trial Balance
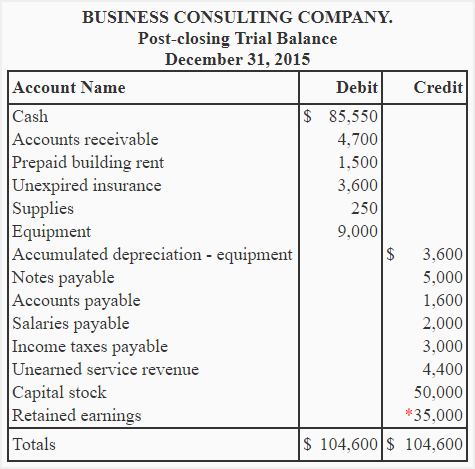
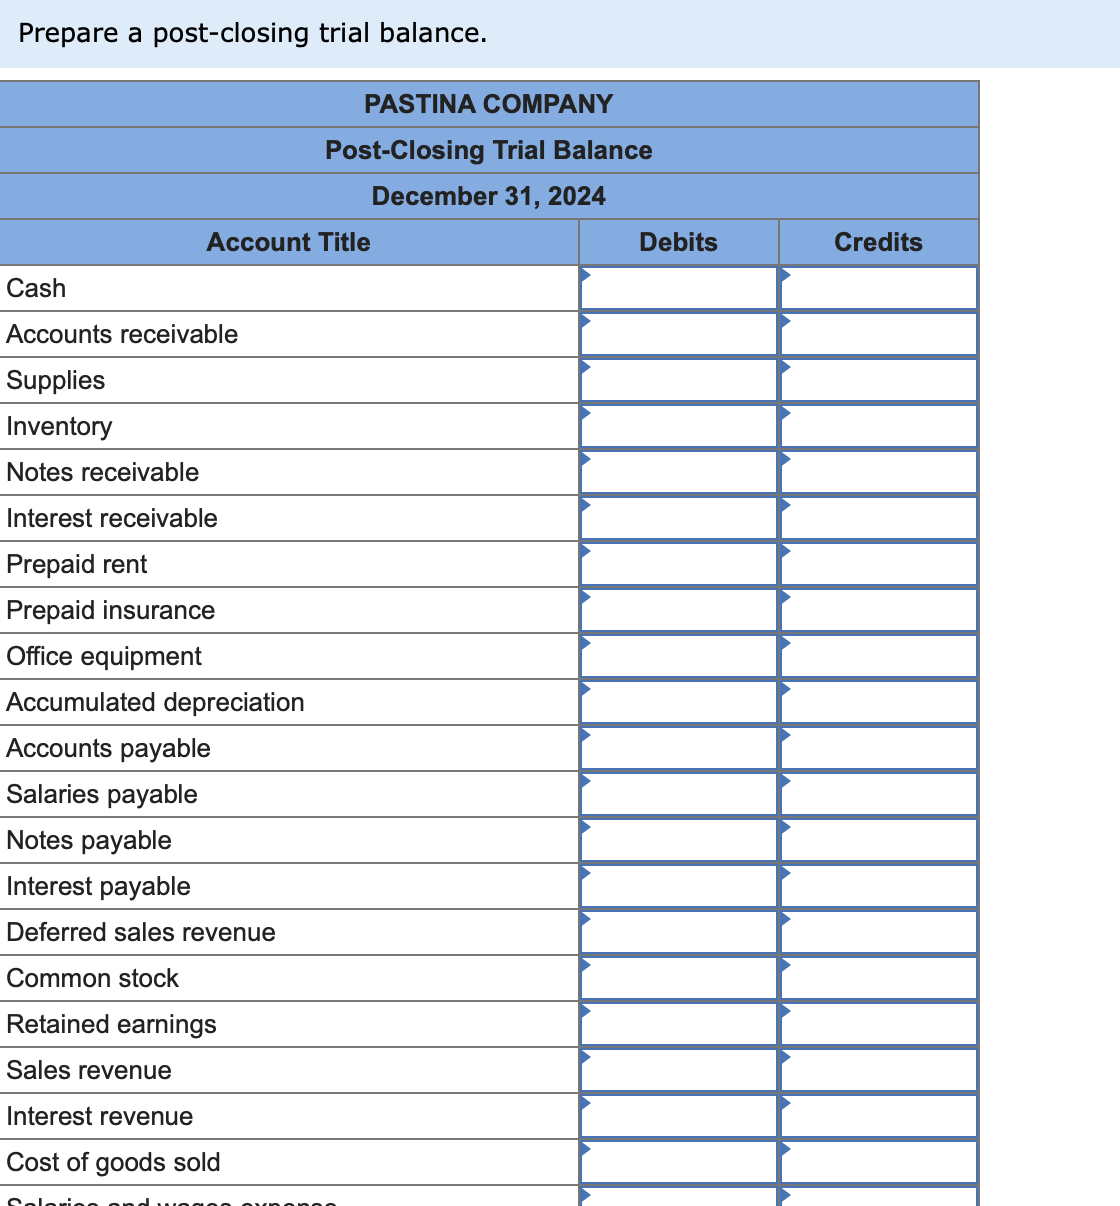
The post closing trial balance is the final verification step before a new accounting period opens. It lists only permanent accounts—assets, liabilities, and equity—and confirms that debits equal credits after all closing entries have been posted. Revenue, expense, and dividend accounts should show zero balances at this point. That's the textbook definition. Here's what it actually looks like when you're staring at it at 11pm on the last business day of the quarter. In most accounting software, you'll find this under reports or period-end procedures. QuickBooks has it as a "Post Closing Trial Balance" report. NetSuite generates one through the general ledger reports section. Xero pulls it from the accounting reports menu. If you're doing this manually in Excel, you filter your trial balance to show only accounts with ending balances that aren't zero after closing entries, then re-sort by account type. I've seen people skip this step because the regular trial balance already balanced. Don't do that. The regular trial balance includes temporary accounts, which means you're not verifying that your closing entries actually worked. Here's the thing nobody tells you about closing entries: they don't always post correctly the first time. A misfiled closing entry can silently corrupt your equity accounts, and you won't know until you pull the post closing trial balance and see retained earnings off by a amount that doesn't match anything obvious.
Once your closing entries are posted, run the report. Verify the columns match. If they don't, trace back through each closing entry line by line. I once spent three hours tracking down a discrepancy caused by a duplicate closing entry that had been posted twice—once manually and once through an automated process I'd set up and forgotten about. The post closing trial balance showed retained earnings overstated by exactly the amount of one closing entry's net effect. Took me a while to realize the pattern, but that's the nature of these problems. The numbers are right, just in the wrong place.
Why This Matters More Than People Think
Most accountants treat the post closing trial balance as a formality. It's not. It's your last checkpoint before any auditor, IRS agent, or lender looks at your books for the new period. If opening balances carry forward incorrectly, everything downstream is wrong. Your income statement for the new period will be contaminated by prior period errors that won't be detectable through normal reconciliation processes. Here's a practical nuance: the post closing trial balance doesn't catch everything. It won't flag unrecorded transactions, misclassified accounts, or timing differences that haven't resolved yet. It only confirms that your permanent accounts balance after closing. That's it. You still need to reconcile your balance sheet accounts separately. The trial balance is necessary but not sufficient for period-end verification. One edge case that trips people up regularly involves intercompany transactions. If you have multiple entities and one has recorded an intercompany receivable while the other hasn't recorded the payable yet, your post closing trial balance will balance—because both entries affect permanent accounts—but your consolidated financials won't reconcile. I handle this by running intercompany reconciliations before I even attempt the closing entries, and I flag any unmatched items separately rather than letting them ride into the new period.
Get the Full Details
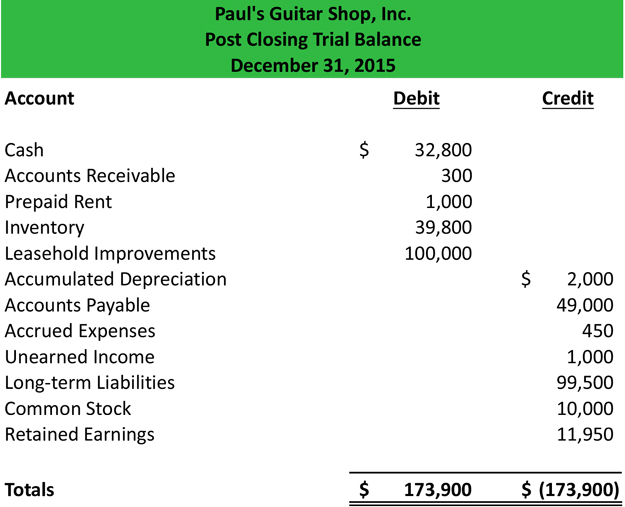
Another thing worth noting: if you use accrual accounting and have significant accrued expenses or revenues at period end, make sure those accruals are properly captured before generating the post closing trial balance. Accruals affect permanent accounts on the balance sheet, so they'll appear in the report, but if they were estimated rather than precisely calculated, you might not notice the error until you're comparing actuals to what you predicted. This is especially relevant for industries with significant revenue recognition timing differences. The post closing trial balance is where you confirm the foundation is solid before building the next period on top of it. It's boring work. It should be boring. If anything interesting shows up, that's when you have a problem.