How to Actually Use a Practice Valuation Worksheet Without Burning Three Days on It
The practice valuation worksheet is a spreadsheet-driven framework that takes your firm's financial data and runs it through standardized income, market, and asset-based approaches to land on a defensible value. It sounds straightforward. Most people treat it like it's simple, then spend a week wrestling with it because they skipped the part where you have to decide what to include and what to exclude from adjusters. I'll get into the method first since that's where people go wrong, then come back to definitions and the actual mechanics.
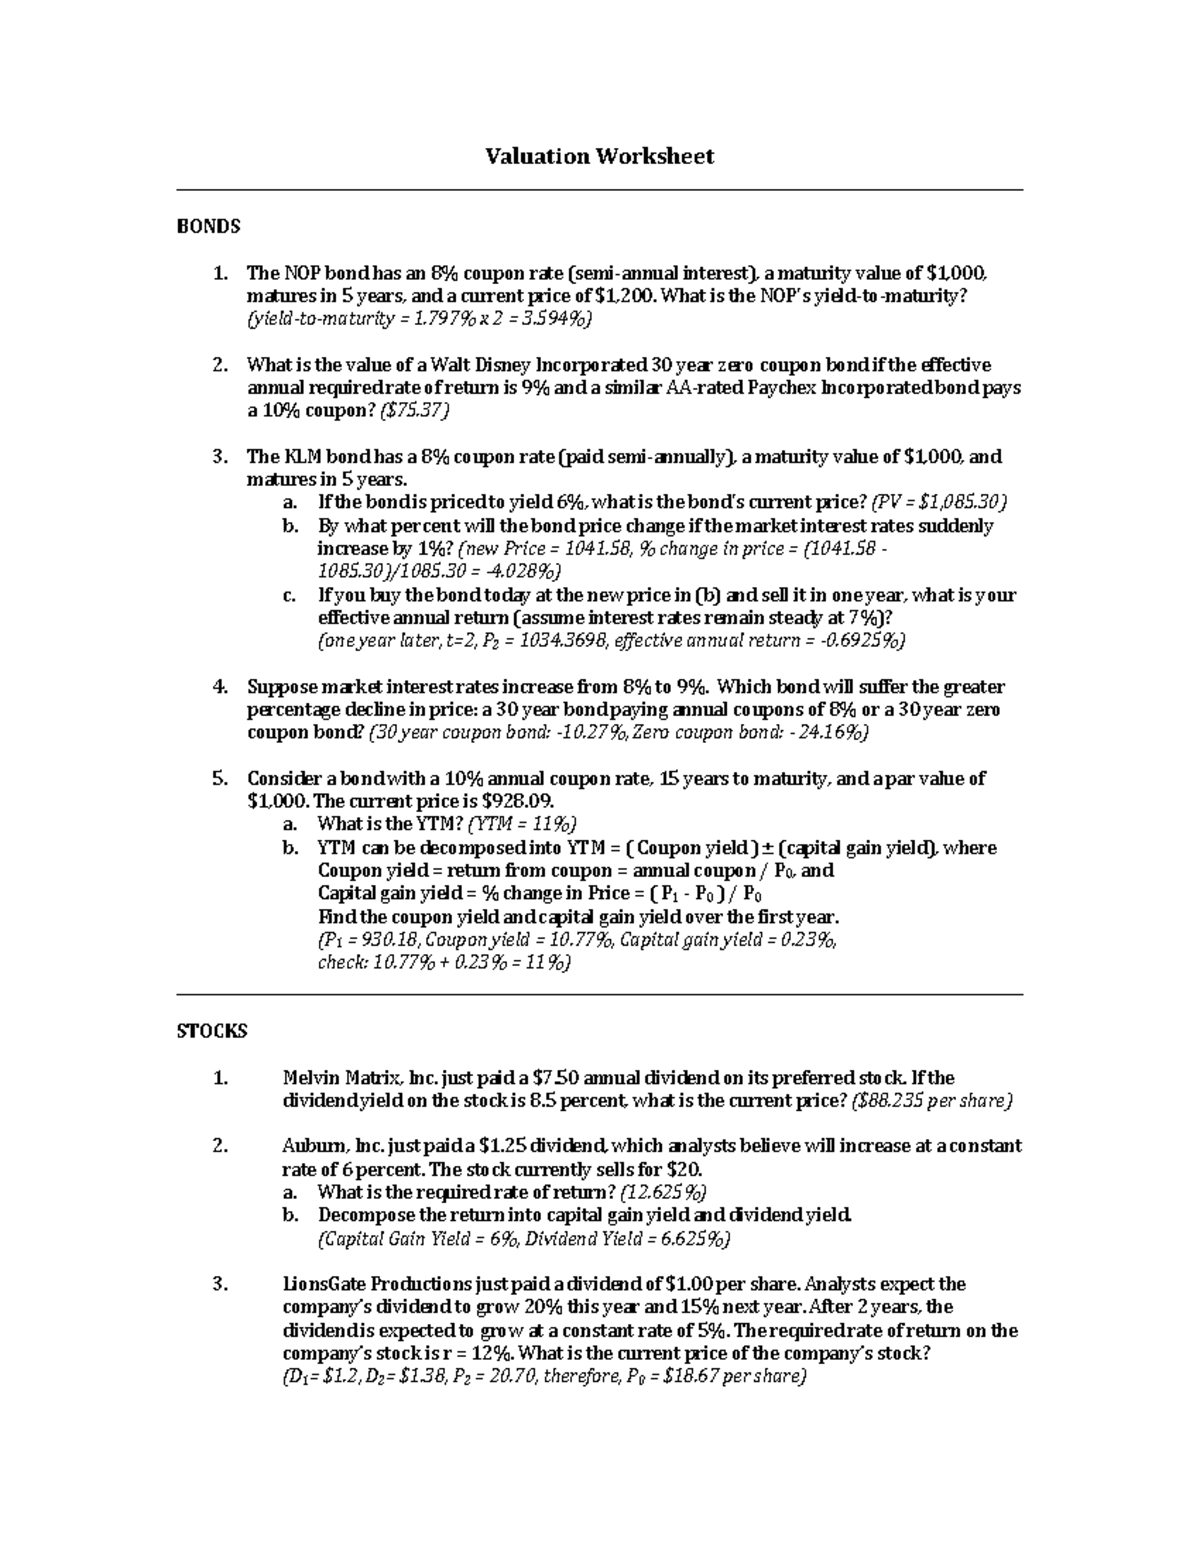
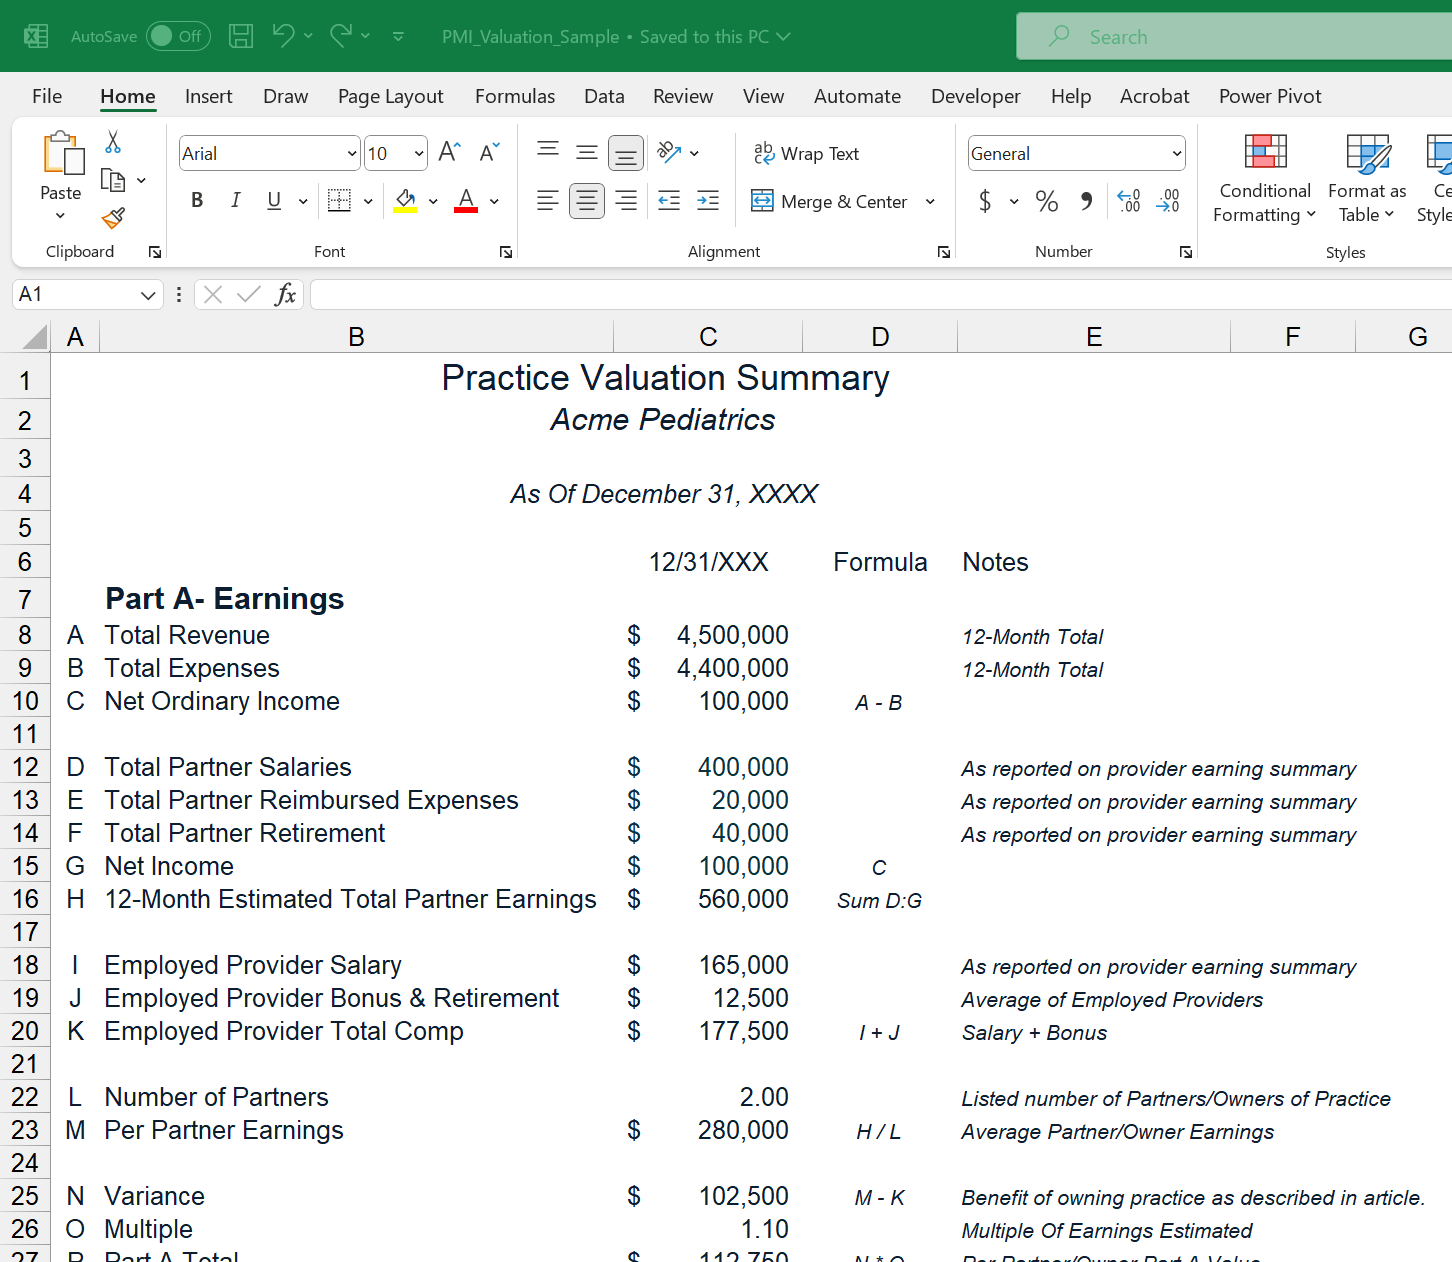
Practice Valuation Worksheet
At its core, the worksheet is a structured document that captures normalized revenue, adjusted expenses, recurring versus non-recurring line items, capital expenditure schedules, and then maps those figures to valuation multiples or discounted cash flow models. The goal is to produce a single number that holds up under scrutiny, not a number that looks good on paper. There is a difference, and it usually shows up during buyer diligence. The typical worksheet breaks down into four sections: Section one is financial normalization. You start with three to five years of income statements and balance sheets. Then you adjust for owner compensation that deviates from market rate, non-recurring expenses like a one-time lawsuit settlement or a major equipment failure replacement, and revenue that is lumpy or dependent on a single client. The point is to make the financials reflect what a reasonable buyer would actually inherit.
Section two is earnings selection. This is where beginners waste the most time. You have to pick whether you are working from Seller's Discretionary Earnings, Adjusted EBITDA, or Normalized Net Profit. The choice depends entirely on firm size and structure. A solo consultancy with $800,000 in revenue uses SDE. A multi-practice group pulling in $8 million uses EBITDA. Mixing them up produces numbers that make zero sense in either context. Section three applies valuation methodologies. The income approach uses a discounted cash flow model with a discount rate calibrated to your industry's risk profile. The market approach stacks comparable transaction multiples from recent sales in your sector. The asset-based approach sums adjusted tangible and intangible assets, which matters most for professional firms with heavy physical infrastructure or specialized equipment. Most worksheets run all three and reconcile the range. Section four documents assumptions. This is the part everyone skims. It is also the part that determines whether your number survives a buyer's review. You need written justification for every adjustment, every multiple you select, and every growth rate you assume.
Get the Full Details
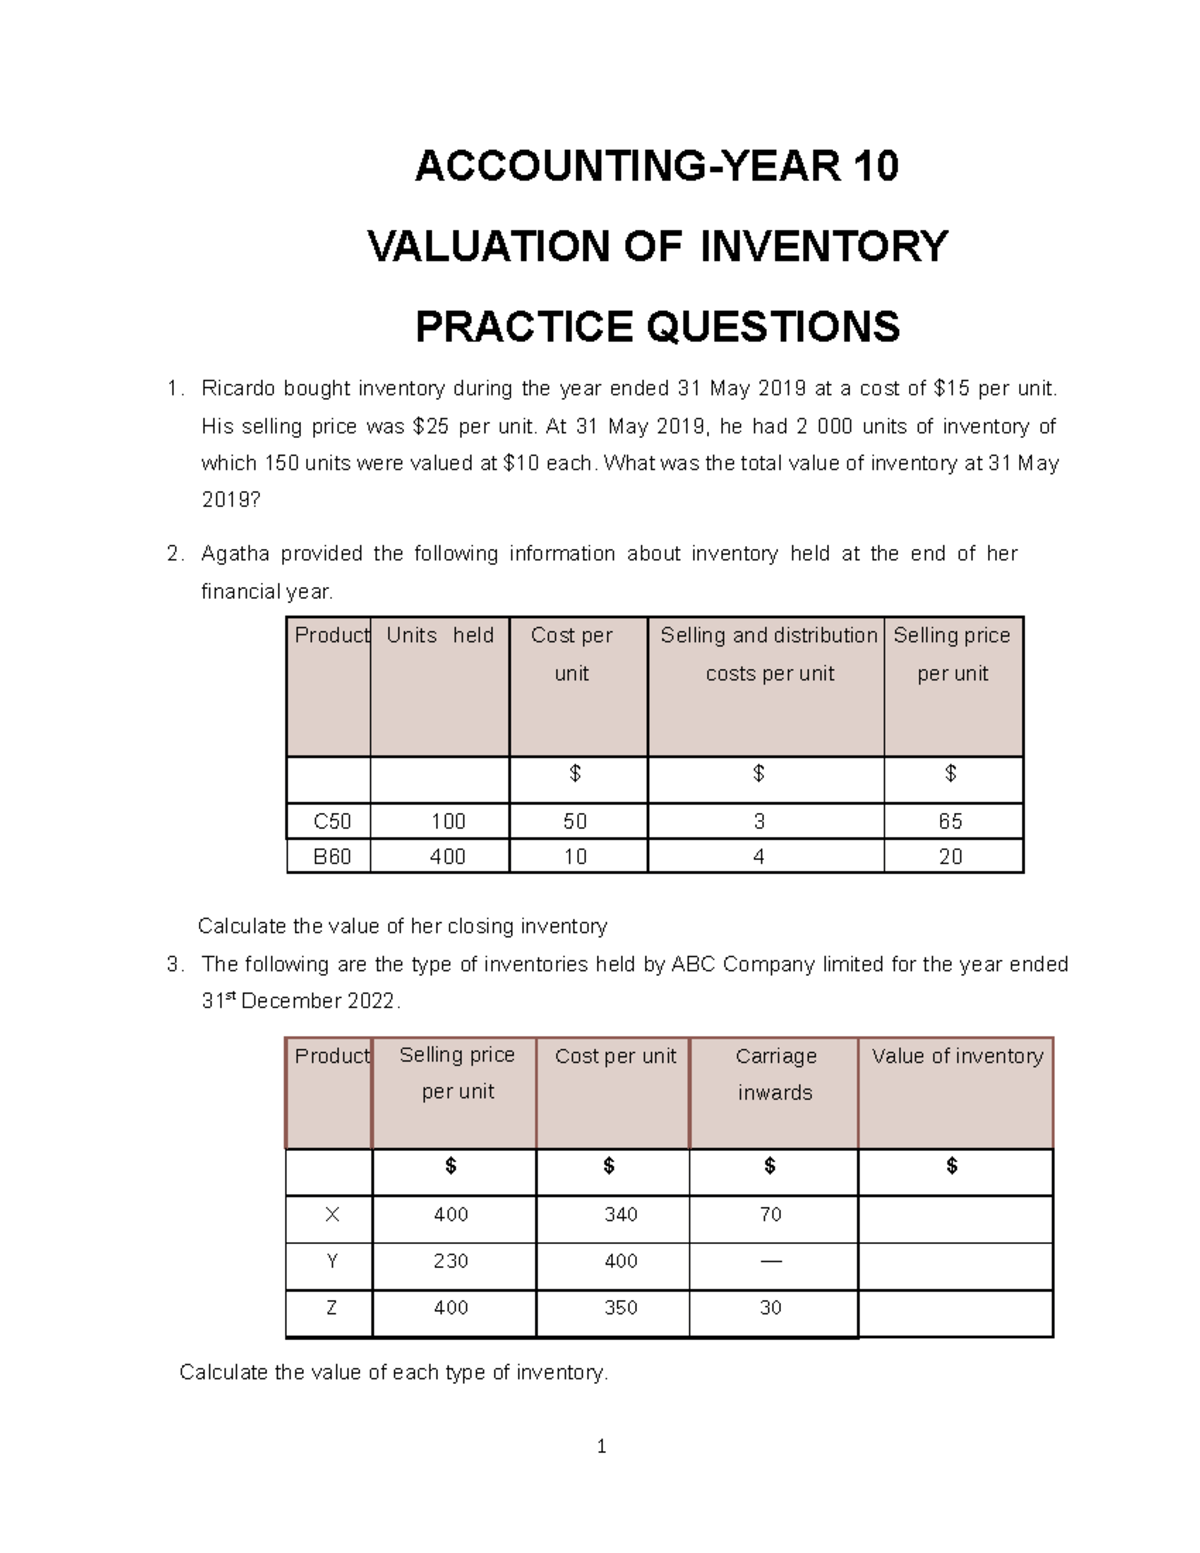
I ran into a specific problem last year with a mid-size dental practice that was trying to use a standard worksheet template for an SDE-based valuation. The issue was that the practice had recently converted from production-based compensation to a modified straight salary model for their associate dentists, which completely distorted the trailing twelve-month earnings. The template was pulling raw production figures as if they represented true economic profit. I ended up backing out the compensation shift and reconstructing three years of normalized earnings from the old budget versus actual records before the switch. It took about six hours of manual reconciliation, but it changed the value by roughly eighteen percent compared to what the unadjusted worksheet would have shown. The template alone could not handle that kind of structural change. Here is a counter-intuitive thing that does not get enough attention: in professional service firms, the highest revenue does not always correlate with the highest value multiple. I have seen large practices with $12 million in revenue trade at 2.1 times SDE while smaller firms at $2.5 million traded at 3.8 times. The difference came down to client concentration and dependency on the founder. A buyer pays for predictability, not volume. The worksheet can capture this if you feed it clean data, but if you do not include a concentration risk adjustment, the output will be misleading. Another nuance that trips people up is the treatment of goodwill and personal goodwill. In many professional practices, a significant portion of value is tied to the current owner's reputation and relationships, which is not transferable. The worksheet needs a separate line item that quantifies and then subtracts personal goodwill when calculating enterprise value. If you skip that, your final number will be artificially inflated and any buyer or lender will call it out immediately.
To build the worksheet yourself, start by gathering your last three fiscal years of tax returns, internal P&L statements, and a current balance sheet. Export them into a spreadsheet where each row is a line item and each column is a year. Do not rely on accounting software exports alone, because they often group or label items differently than what a valuation analyst expects. Reconcile the numbers to your actual general ledger first. Next, create an adjustments schedule. Go line by line through each year and flag every item that is non-recurring, above-market, or unusual. Use a color coding system so you can see patterns across years. Items that appear in every single year are probably not adjustable, even if you think they are. Only adjust the ones that are truly outliers. Then compute your normalized earnings figure. This is your starting point for the income and market approaches. The math is straightforward: normal EBITDA or SDE equals reported earnings plus all approved adjustments minus any capital expenditures that should have been booked in the period.
For the income approach, calculate a discount rate. A common starting point for small professional firms is a twelve to fourteen percent discount rate, but you should adjust upward if the business depends heavily on one or two key people or if revenue is declining. Multiply your normalized earnings by a capitalization rate derived from that discount rate minus an assumed growth rate, and you get a present value estimate. For the market approach, look up recent transaction data from sources like the International Business Brokers Association deal database or industry-specific reports from NALVA or ASA. Apply multiples from comparable sales and adjust for size and risk differences. The worksheet should have a section where you list each comparable, its stated multiple, and your adjustment factor. The asset-based approach is simpler but often overlooked. Calculate the adjusted fair market value of all tangible assets, subtract liabilities, and add a reasonable intangible asset value. This matters most for firms with significant equipment, real estate holdings, or proprietary technology that is not reflected in revenue multiples alone.
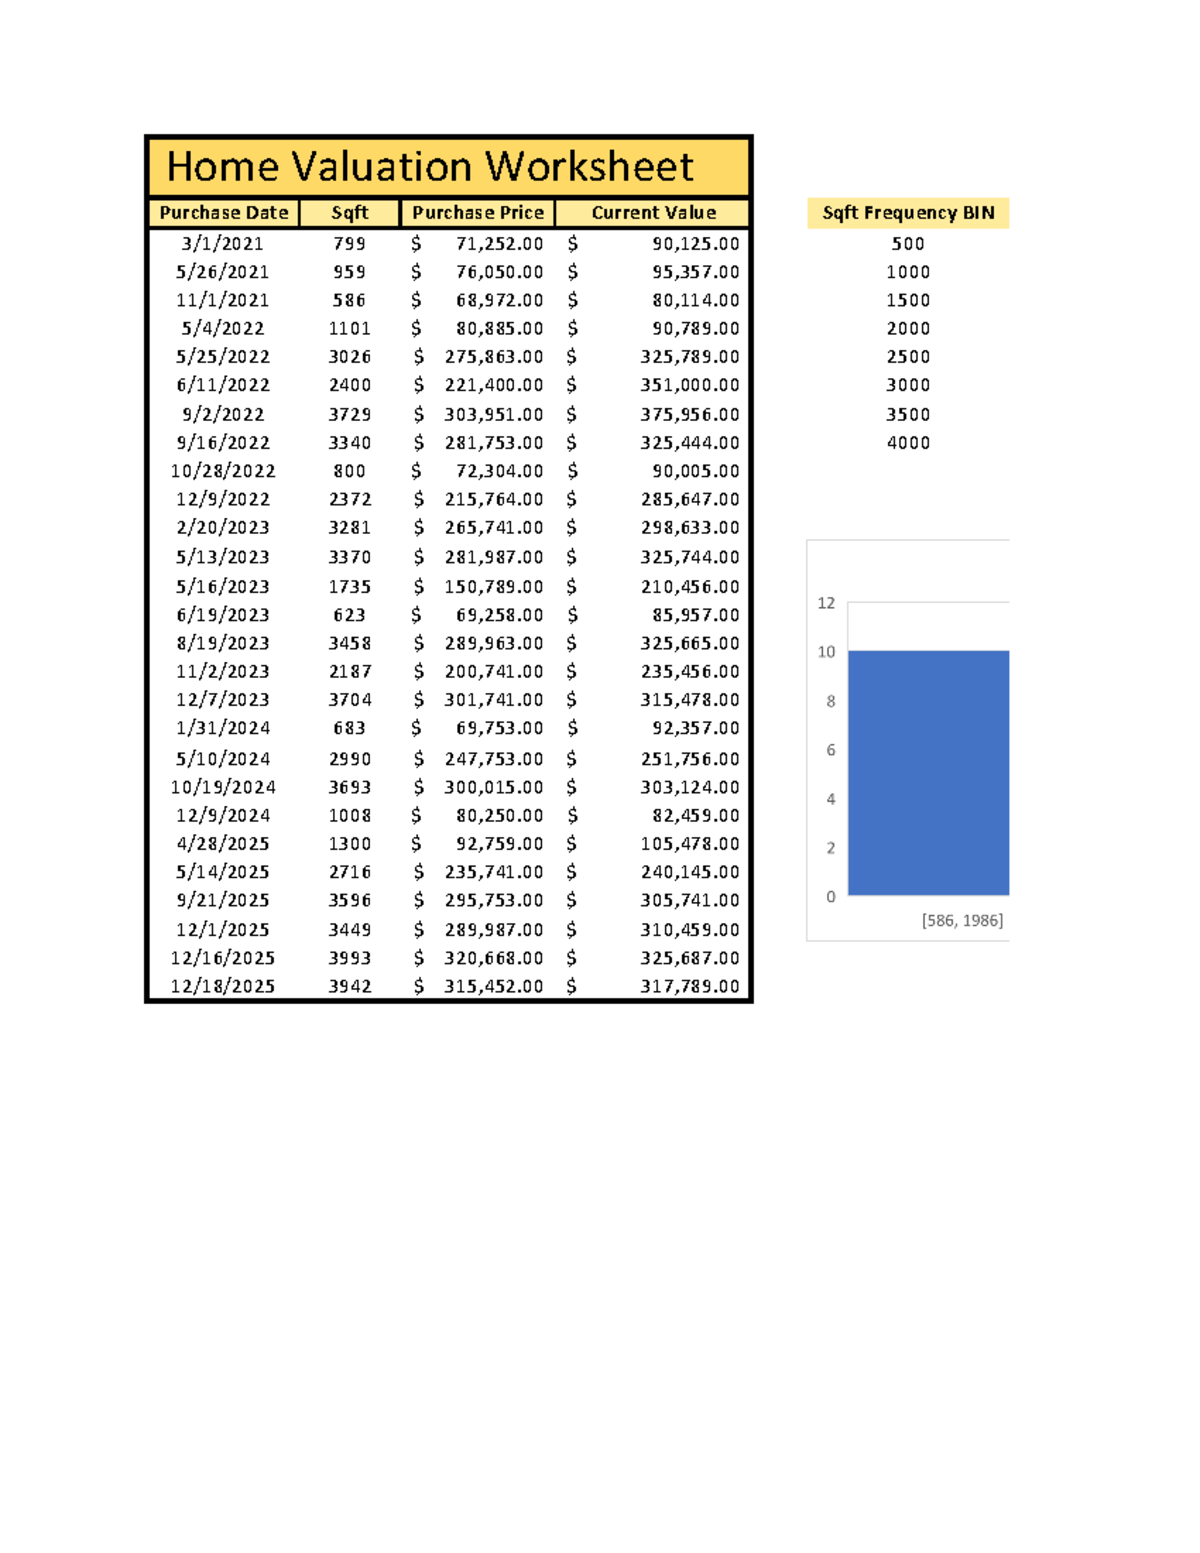
Reconcile the three approaches by looking at where they converge. If they are far apart, revisit your adjustments and assumptions. A spread wider than twenty-five percent between approaches usually means something in your data is wrong, not that the business is confusingly valuable. Here is what the worksheet cannot do well. It struggles with firms that have highly irregular revenue cycles, such as consultancies that recognize revenue at project milestones rather than monthly. It also performs poorly when there are fewer than two years of financial history, because you cannot establish a meaningful trend. In those cases, a full business appraisal with expert testimony is a better option than relying on a spreadsheet. One more limitation worth noting: the worksheet does not account for contingent liabilities unless you manually input them. Legal disputes, pending regulatory reviews, and unrecorded warranty obligations can all eat into real value, but the template will ignore them until you explicitly add them. I have seen valuations fall apart at closing because the buyer discovered a pending claim that the seller had never recorded in the worksheet adjustments.
If you want to work through this yourself, the worksheet can be built in Excel or Google Sheets. The structure is simple enough that you do not need special software. Just make sure every section is linked so that a change to one assumption automatically updates the final value range. Static spreadsheets create errors when you forget to update downstream cells. The whole process, from data gathering to a reconciled valuation range, typically takes between eight and twenty hours for a small professional practice, depending on how messy the financial records are. If your books are in order, you can do it in an afternoon with a well-built template. If they are not, expect to spend a week cleaning data before the worksheet produces anything reliable. The bottom line is that a Practice Valuation Worksheet is a tool, not an answer. It produces a defensible range when fed accurate, adjusted data and properly documented assumptions. It produces garbage when you feed it raw numbers and hope the math compensates for bad inputs. Treat it like the former, not the latter.