What Most People Get Wrong About Accounting Interviews
I watched a candidate get sent home after confidently explaining deferred tax assets using only the income tax rate. The interviewer didn't even finish the question before waving them off. This happens more than you'd think. The problem isn't that they don't know accounting. They just know the textbook version, not the version that shows up in a real interview. Preparing For An Accounting Interview doesn't mean memorizing journal entries and hoping for the best. You're being evaluated on whether you can walk into a messy situation — mismatched sub-ledgers, ambiguous transaction descriptions, a senior who expects the answer yesterday — and actually figure it out without panicking. They want to see your process, not your ability to recite ASC 606 verbatim.
The Framework Most Candidates Ignore
Here's the thing nobody tells you. Accounting interviews aren't testing whether you know the answer. They're testing whether you know how to get to the answer when the data is incomplete. I've sat on panels where we deliberately gave candidates bad trial balances, missing reconciliations, and transactions that didn't cross-reference properly. We weren't looking for the right number. We were watching how they asked questions, where they drew lines, and what they did when their first approach clearly wasn't working. You need a repeatable mental framework. When I'm prepping candidates, I drill one sequence into them: identify the reporting requirement, map the transaction to the financial statement line item, determine the measurement basis, consider the disclosure, then check for cross-foot. It sounds mechanical. It should be mechanical. Under pressure, your brain will default to whatever pattern it's practiced. Let me give you a concrete example from a real interview I consulted on recently. The firm asked a mid-level accountant to walk through how they'd handle a software licensing arrangement that included implementation services, perpetual updates, and a termination clause with a clawback provision. This is essentially a multi-element arrangement under what used to be ASC 605-25 and now falls under the core revenue recognition standard. Most candidates started talking about percentage-of-completion or straight-line amortization. Wrong direction entirely. The right move was to first separate the performance obligations, then allocate the transaction price based on standalone selling prices, then determine timing of revenue recognition for each component. The candidate who got the offer started by asking what the standalone selling price of the implementation services was. That's the moment we knew they understood the actual mechanics.
Technical Areas That Actually Come Up
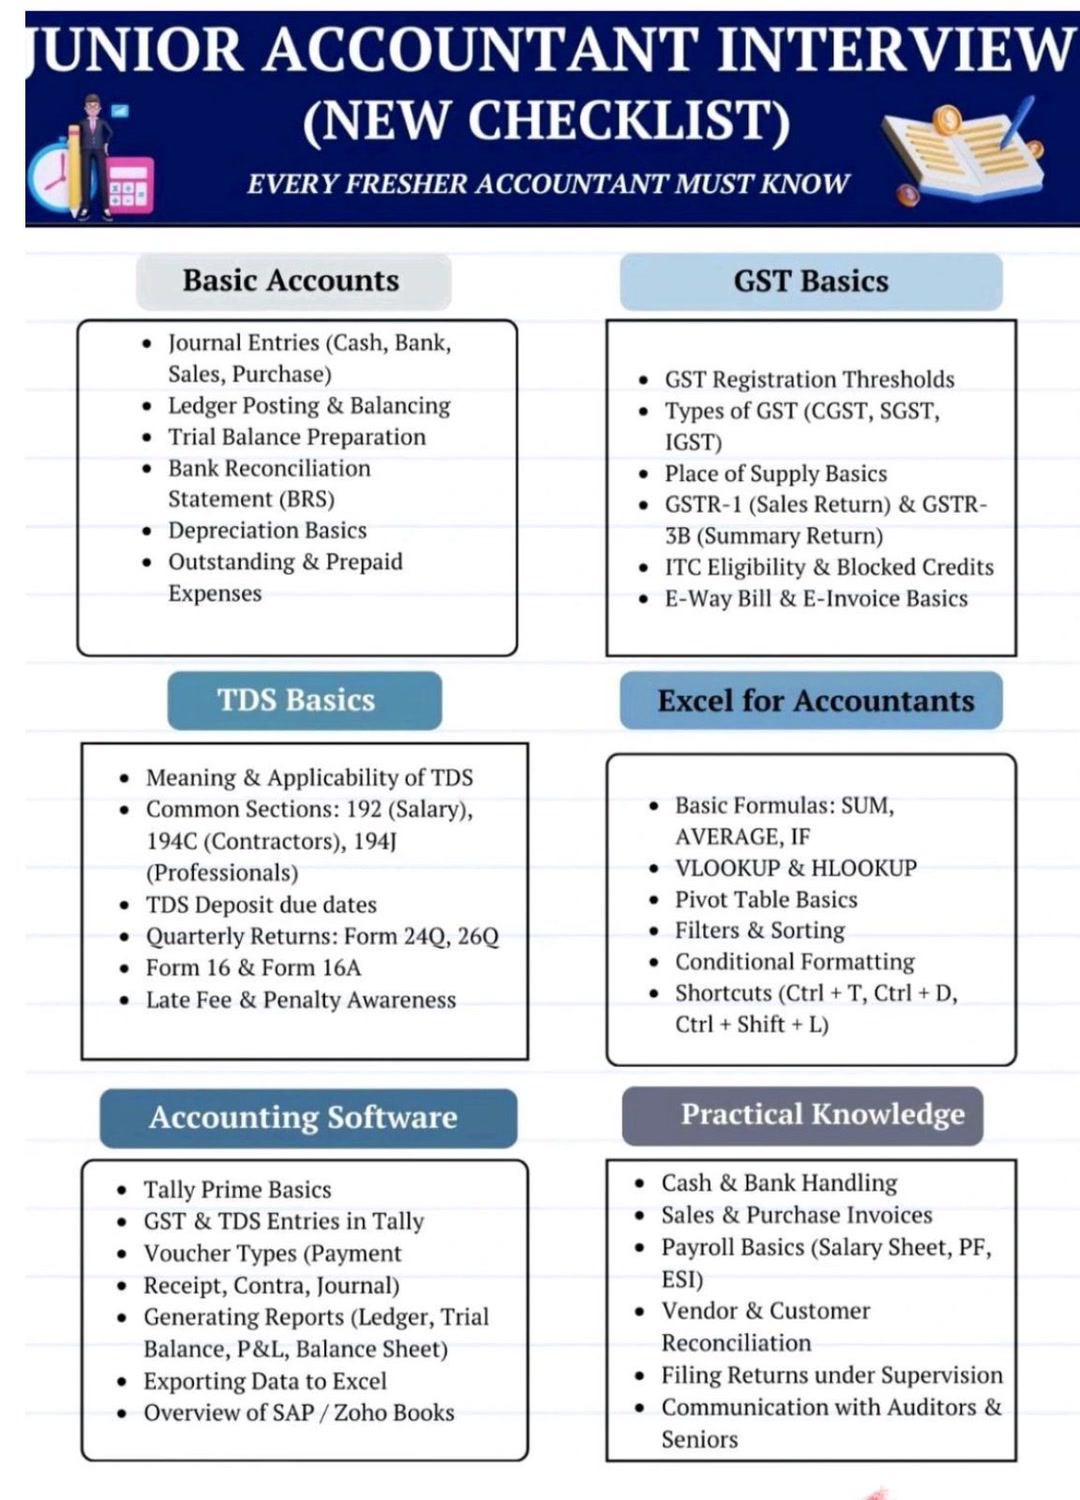
Forget the broad survey approach. Focus on what shows up repeatedly across firms and industries. Revenue recognition is the big one. Not just the five-step model — the gotchas within it. Variable consideration, constraints on variable consideration, principal versus agent assessments, identifying distinct goods and services. If you're interviewing at a tech or SaaS company, know what you're getting into with subscription models, license arrangements, and upgrade paths. Leases are another area where candidates fall apart. They'll tell you about ASC 842 and the right-of-use asset. But push them on lease versus non-lease components, how to determine the discount rate when the implicit rate isn't readily available, or how modifications work, and suddenly the textbook knowledge evaporates. I once saw someone blank on the difference between a lease term and a non-cancellable period when asked about renewal options that were reasonably certain of exercise. That's a basic distinction that takes about twenty minutes to clarify in any decent reference. Impairment testing comes up more than you'd expect, especially at companies with significant goodwill or long-lived asset bases. Know the difference between the quantitative and qualitative approaches under ASC 350-20 and ASC 360. Know when a triggering event requires action. Know what inputs go into a discounted cash flow model for a reporting unit. And importantly, know what not to do — like adjusting cash flows to include unrealized appreciation in growth assumptions without documenting the change from prior years.
Get the Full Details

Case Study Questions and How to Handle Them
Situational questions are where interviews are won or lost. You'll get something like "your month-end close is in four hours and you discover a material misstatement in accounts receivable. What do you do?" This isn't really about the accounting. It's about judgment, communication, and process. The right answer involves three moves in order: assess materiality and whether it's been communicated already, determine if restatement or adjustment is needed, and escalate to the right people with a clear recommendation. Not "I'd fix it." Not "I'd figure it out." Those are filler answers that tell the interviewer nothing about your actual decision-making framework. Here's a more specific scenario I dealt with during a consulting engagement. A candidate was asked how they'd handle a situation where a sales director wanted to recognize revenue on a contract that hadn't met the collectibility threshold. The candidate's instinct was to walk through the standard and say no. That's correct but insufficient. The person who impressed us acknowledged the technical answer but also discussed the relationship dynamics — whether there was a legitimate business reason for the pushback, what documentation existed to support or contradict the director's position, and how they'd approach the conversation with the director present rather than behind their back. Accounting isn't done in a vacuum. The interview is checking whether you remember that.
Behavioral Questions That Matter More Than You Think
Don't shortchange the behavioral portion. Firms hire people they'll work with daily for years. A candidate who can articulate a time they disagreed with a controller's interpretation, navigated a deadline conflict with another department, or caught an error in someone else's work demonstrates maturity that pure technical competence doesn't guarantee. Use the STAR method but don't make it sound like a template. I've heard candidates so polished in their delivery that it became impossible to tell if the story was real or constructed. The tell is usually in the details — the specific dollar amounts, the names of systems, the actual conversation snippets. If you're describing a reconciliation you did last March, you should be able to say whether you used SAP or QuickBooks, what the variance was approximately, and what the root cause turned out to be. Vague recollections are worse than admitting you can't remember everything precisely.
What to Prepare Before the Interview
Review the company's most recent financial statements. Not just skim them. Pull the notes. Look at the accounting policies section. See how they describe revenue recognition, inventory, leases, goodwill, debt. If they have a significant change in estimate or a new standard adoption, understand what happened and why. This gives you concrete material to reference during the interview and signals that you've done basic homework. Know the industry. An accounting interview at a healthcare company will look very different from one at a manufacturing firm or a nonprofit. Revenue cycles, regulatory considerations, critical estimates — these all shift dramatically by sector. I had a candidate apply to a hospital system without understanding how bad debt reserve estimation works in that environment. They talked about standard allowance methodologies that would be completely off-base. Industry-specific knowledge is a differentiator that most candidates don't bother with. Bring a notebook and write things down during technical questions. This is underrated. It shows you're engaging with the problem rather than just waiting for your turn to talk. It also gives you a moment to think when you're put on the spot. I've seen good candidates freeze on questions that would have been straightforward if they'd had sixty seconds to sketch out the framework on paper.
The One Thing That Separates Good From Hired
Curiosity under pressure. When you hit a gap in your knowledge, what do you do? Do you panic and guess? Do you shut down? Or do you acknowledge the gap, propose how you'd find the answer, and walk through your reasoning with what you do know? The last option is the one that consistently lands offers. I've interviewed people who correctly admitted they didn't know the specific ASC number for a particular issue but could still work through the underlying principle and reach a defensible conclusion. Those conversations tend to be longer and more interesting than the ones with people who recite standards robotically. Preparing For An Accounting Interview successfully means treating it like a real workday disguised as a conversation. The people on the other side of the table are trying to figure out whether you'll add value or create work for everyone around you. Everything you say should make that case.