Understanding Present Bias in Real-World Decision Making
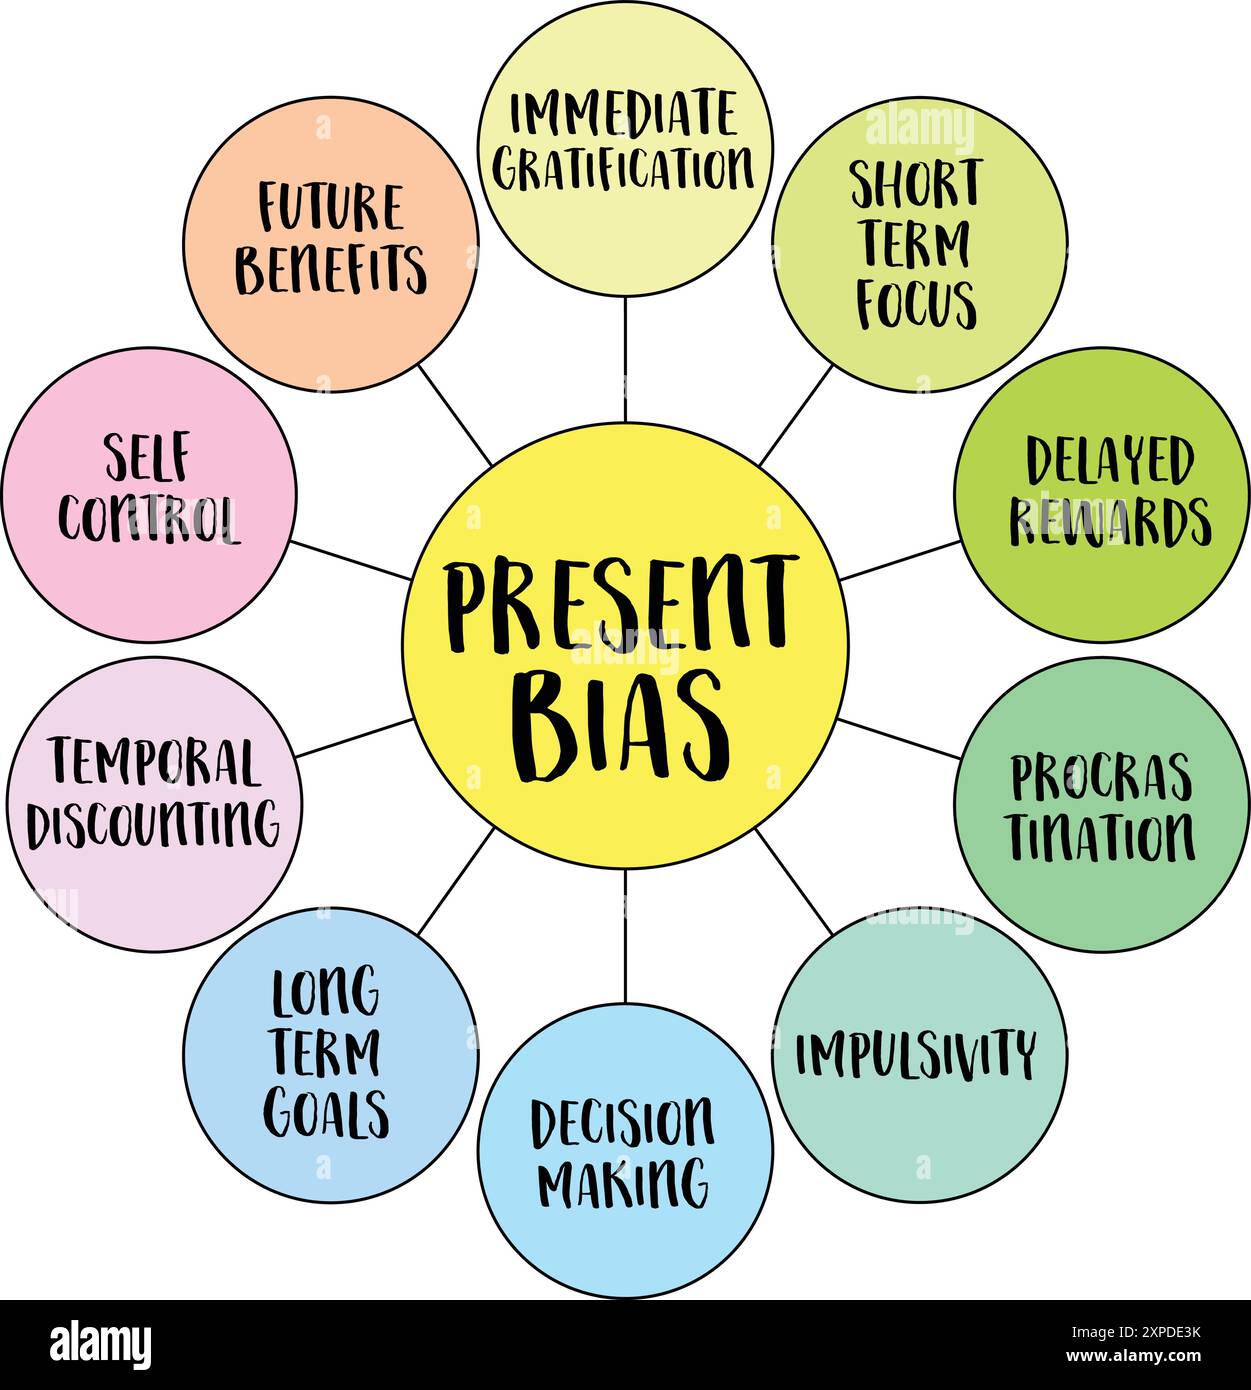
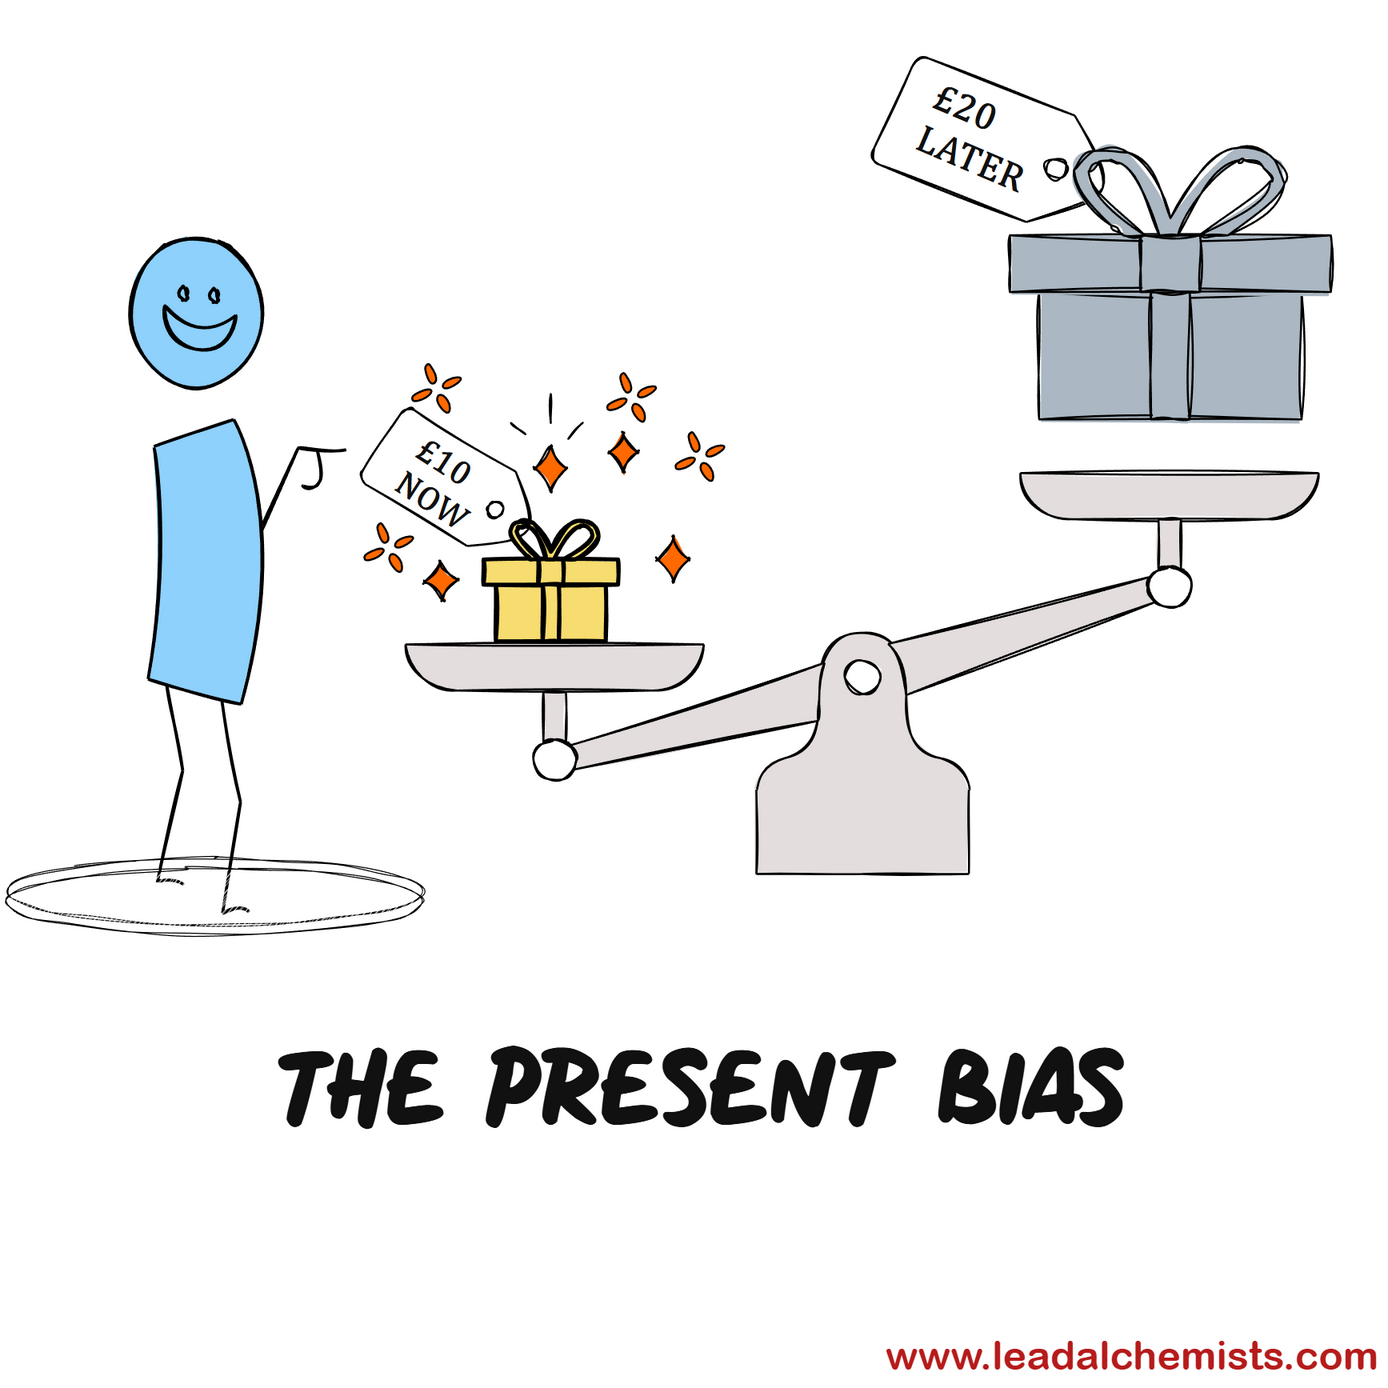
Present bias is the tendency for people to overweight immediate rewards relative to future ones. In practice, it shows up constantly in behavior that people then have to deal with. I ran into this directly when managing a team budget project. Someone had committed to a quarterly milestone three months out, then started cutting corners two weeks before delivery because the deadline felt too far away to matter. The work quality dropped noticeably. That is present bias in action, not some abstract concept from a textbook. The name itself is slightly clunky because "present present bias" repeats the word present, but that is how it appears in academic literature sometimes. The core idea stays the same: people discount future outcomes heavily. A Present Present Bias Psychology Example you will see everywhere is someone choosing a smaller payment today over a larger payment next month, even when they know the larger payment is objectively better for them. I once worked with a client who was trying to build a retirement savings plan. Every time we scheduled a review, they had already spent the surplus cash on something immediate. Not something necessary. Something immediate. They knew the math. They understood compound growth. The knowledge did not stop the behavior because the brain weights today's dollar differently than tomorrow's dollar.
Why This Happens and How to Work Around It
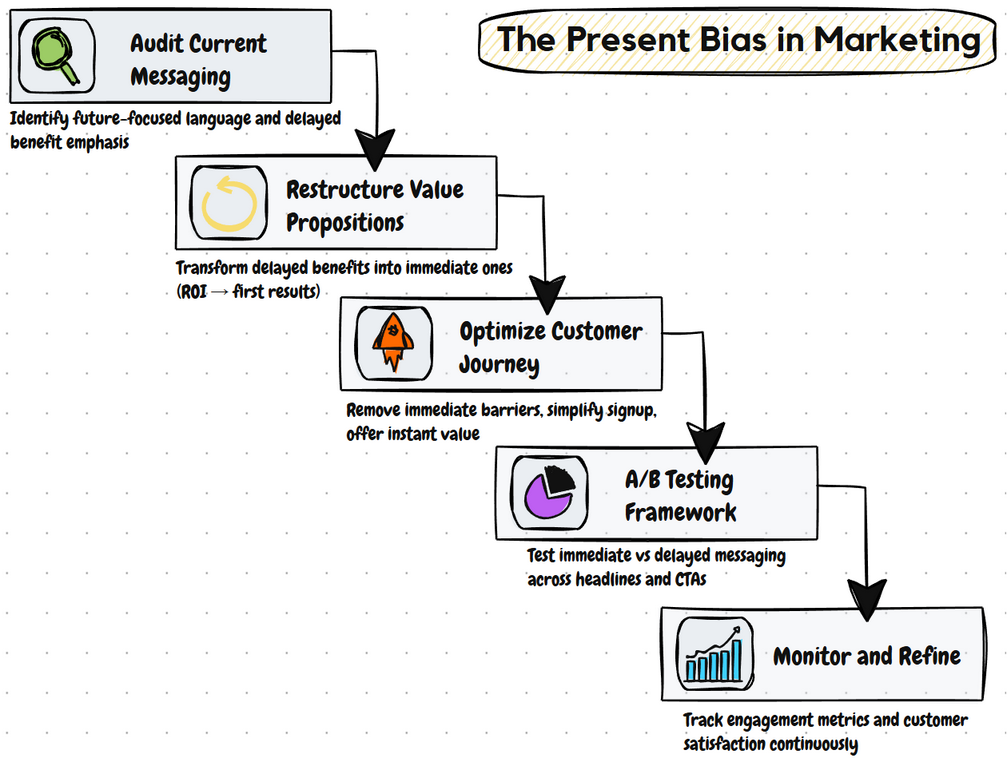
Present bias comes from how humans process time and reward. The prefrontal cortex handles long-term planning while older brain regions drive immediate impulse. When these two systems compete, the immediate reward usually wins unless you structure things differently. Here is what I learned doing this work for years: the most effective workaround is not willpower. It never is. The workaround is commitment devices and environment design. Take the retirement savings example again. The person did not need motivation. They needed to make the default option automatic so they would not have to choose at all. We set up auto-transfers on payday. The money moved before they could see it. Within six months, the habit solidified without daily decision-making. Another practical approach is breaking large future goals into smaller immediate milestones with visible rewards. I used this with a product development timeline that kept slipping. The original schedule had deliverables three months apart. Nobody felt urgency. I broke each milestone into weekly sprints with demo days. The immediate audience and the short timeframe made the work feel real. Completion rates improved significantly within two cycles.
Common Mistakes People Make With Present Bias
The biggest error is assuming that explaining the long-term benefit changes behavior. It does not. Logic does not override the immediate reward system in most cases. People understand their own bias intellectually. They still act against it. This is why solutions have to be structural, not educational. A second mistake is setting intentions without removing friction. Someone might decide to start exercising next Monday, but if they have to buy gear, find a route, and fit it into their schedule, they will likely do nothing. The barrier is too small to notice but real enough to block action. I solved this for a team by having them pick the gym on Friday and pack their bag before leaving work. The decision was made when motivation was high and the execution was removed from the willpower equation entirely.
Get the Full Details
When This Framework Fails Completely
Present bias interventions do not work in every situation. If someone is under extreme financial stress or dealing with addiction, standard commitment devices are not enough. A person drowning in debt will still spend available cash on immediate relief because the pain is too pressing to ignore long-term consequences. In those cases, professional support and systemic changes are required, not just behavioral hacks. Also, over-relying on external structure can weaken intrinsic motivation over time. I noticed this with a client who had automated savings but never engaged with their financial goals actively. When we paused the automation for a month due to a banking issue, they reverted to old spending patterns quickly. The habit had been external all along. Building actual financial literacy alongside the automation would have made the system more resilient.
Tools and Resources Worth Looking At
If you want to dive deeper, Richard Thaler and Shlomo Benartzi's work on save more tomorrow is a solid starting point. Their program automatically increases savings rates with each raise, which leverages present bias rather than fighting it. Another useful resource is the behavioral insights team reports from the UK government, which have practical case studies on applying these concepts in policy and business. I also recommend tracking your own decisions for two weeks. Note every time you choose an immediate reward over a delayed one. Write down what triggered the choice and what the long-term cost was. You will start seeing patterns quickly. This is not a perfect method but it builds awareness, and awareness is the first step toward changing behavior. The bottom line is that present bias is predictable and manageable if you accept that rational planning alone will not fix it. Structure your environment, use commitment devices, and remove the need for daily willpower. It is simpler than most people think but harder to implement consistently.