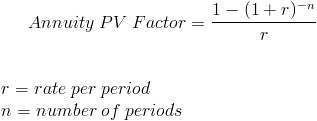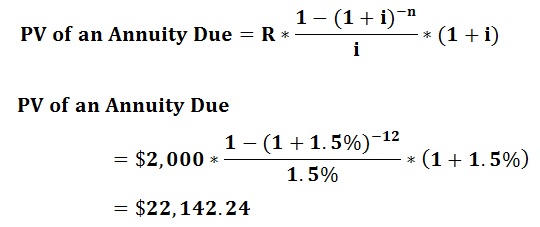
Working With Annuity Calculations in Practice
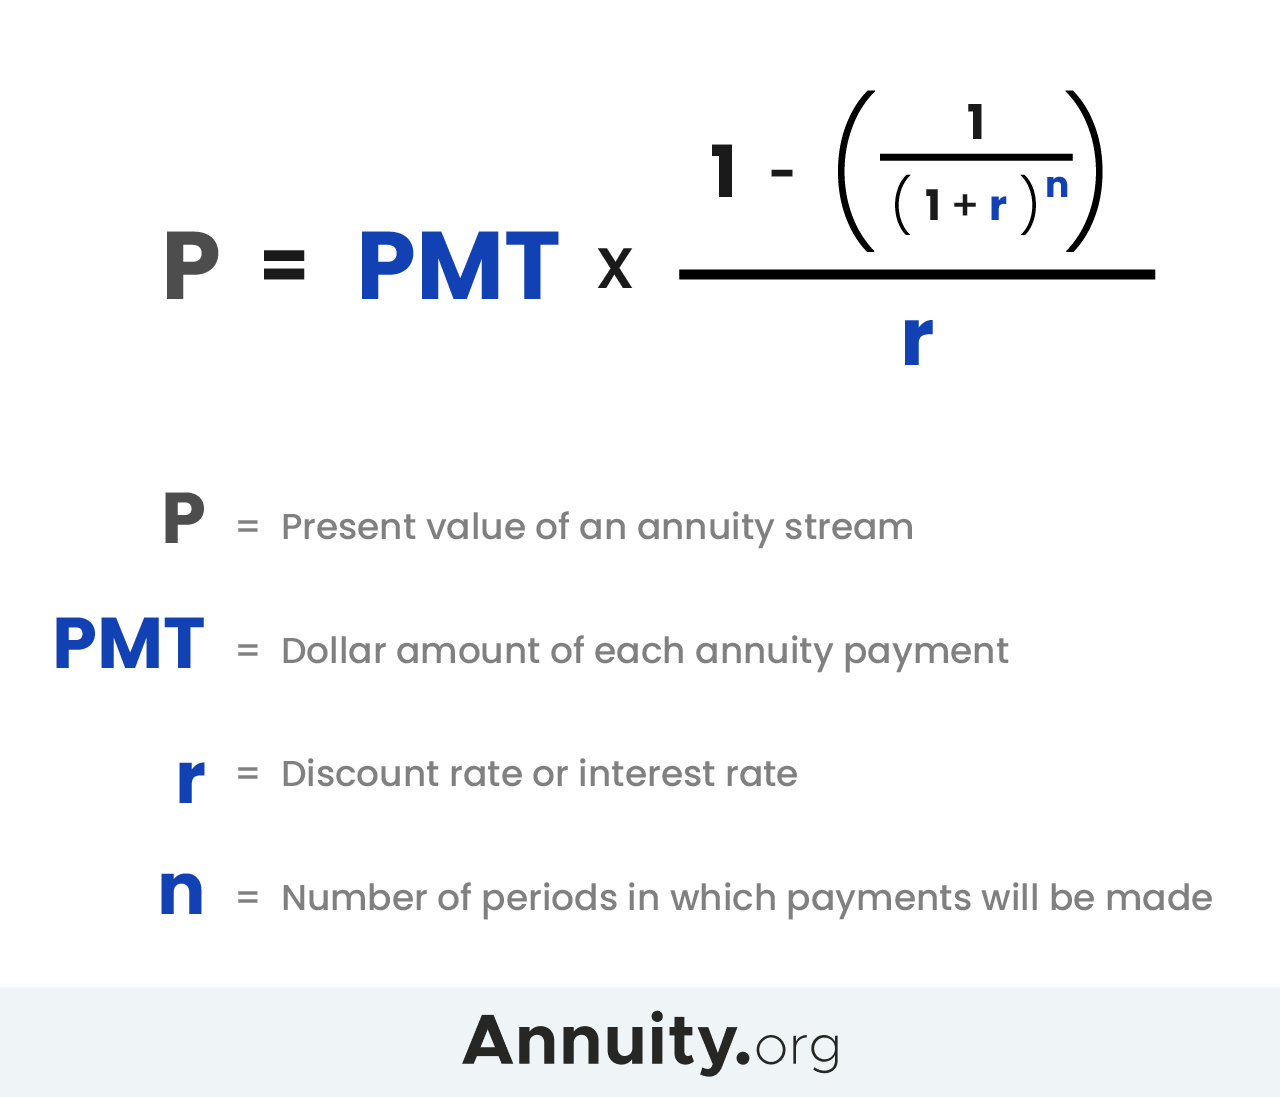
The Present Value Annuity Formula is PV = PMT × [(1 - (1 + r)^-n) / r]. That's the textbook version. In the real world, annuities show up in loan amortization schedules, lease valuations, structured settlement negotiations, and pension funding calculations. If you're doing this work regularly, you'll find that the formula itself is the easy part. The hard part is making sure your inputs actually reflect reality. I remember working on a municipal bond refunding case a few years back. The deal involved a $12 million bond issue with semi-annual payments at 4.2% coupon over 20 years. The model looked clean on paper. Then I cross-checked it against the actual payment schedule from the trustee and found a discrepancy of about $38,000. The problem wasn't the formula. It was that the bond had a make-whole call provision triggered mid-period, which changed the effective timing of the final cash flows. The standard Present Value Annuity Formula assumes equal periodic payments through maturity with no early termination events. Once a make-whole clause kicks in, you can't just plug in the original term and rate. You have to recalculate the remaining cash flow schedule based on the actual call date and the make-whole yield, then run the annuity formula on that adjusted stream. Took me about forty minutes to rebuild the schedule properly. Would have saved us a material misstatement if I'd caught it earlier.
Present Value Annuity Formula
Here's what the formula actually says in plain terms. You're calculating what a series of equal future payments is worth today, given a specific discount rate. The PMT is your periodic payment amount. The r is your discount rate per period. The n is the total number of periods. The expression (1 + r)^-n is just another way of writing the present value factor for a single future payment, and the bracketed portion compounds that across all periods. The most common mistake beginners make is mismatching the period units between the payment frequency and the discount rate. If your annuity pays quarterly but you plug in an annual rate without converting it, your result will be wrong. A 6% annual rate becomes 1.5% per quarter. The number of periods becomes 4 times the number of years. This is where most of the errors I see in practice come from. People copy the annual rate directly into the formula and wonder why the output doesn't match their spreadsheet. Another thing that catches people off guard is the behavior when the discount rate approaches zero. As r gets smaller, the formula's denominator shrinks and the value approaches n × PMT, which makes intuitive sense. But numerically, when r is very small, floating-point precision can introduce rounding errors in certain spreadsheet implementations. I've seen Excel cells return values that differed from the exact mathematical result by a few cents on annuities spanning 30+ years with payments in the low hundreds. For most practical purposes this doesn't matter. When it does, you can use the Taylor series approximation for the exponential term or switch to a financial calculator that handles high-precision decimal arithmetic.
There's also the question of whether you're dealing with an ordinary annuity or an annuity due. The formula I wrote above is for an ordinary annuity, where payments occur at the end of each period. If payments are at the beginning of the period, you multiply the entire result by (1 + r). This adjustment is often forgotten in lease valuation work where rent is typically paid in advance. Missing this factor shifts your valuation by one full period of discounting, which on a multi-year lease can be substantial. I also want to flag a scenario where the Present Value Annuity Formula simply doesn't apply. Variable annuities, or annuities where the payment amount changes each period, require a different approach. You'd need to discount each cash flow individually or break the stream into segments of constant payments and sum their present values. I worked on a structured settlement that had escalating payments tied to CPI adjustments. The annuity formula would have been wrong by over $200,000 on a $2 million settlement. The workaround was straightforward but tedious: I built a year-by-year schedule with the projected CPI-adjusted payments and discounted each one individually using the appropriate spot rate for that maturity.
Get the Full Details

Practical Implementation Notes
If you're building this into a spreadsheet, the built-in PV function handles the annuity calculation for you. The syntax is PV(rate, nper, pmt, [fv], [type]). Setting type to 0 gives you ordinary annuity and 1 gives you annuity due. The function has the same period-mismatch vulnerability I mentioned above, so double-check your rate and period inputs before trusting the output. For someone doing this manually, I'd suggest writing out the cash flow timeline first, even for simple cases. It takes maybe two extra minutes but it prevents the kind of errors that slip through when you're focused only on plugging numbers into the formula. I keep a template with columns for period number, payment amount, discount factor, and present value contribution. When things get complicated — and they always do — that template saves you from having to re-derive the math from scratch every time. The formula also breaks down when the discount rate is negative, which has become relevant in certain European bond markets and some specialty finance applications. The mathematics still works but the economic interpretation becomes questionable. A negative discount rate implies that receiving money later is preferable to receiving it now, which contradicts most standard financial reasoning. If you encounter negative rates in your work, document your approach and note the limitation explicitly.
One more thing worth noting: the formula assumes a constant discount rate across all periods. In reality, yield curves slope up and down, and the appropriate discount rate may vary by maturity. Using a single rate is a simplification that introduces error, particularly for long-dated annuities. The more accurate approach uses a forward rate curve and discounts each payment at its corresponding spot rate. This is what institutional appraisers do for large transactions. For quick estimates, the flat-rate assumption is acceptable within a few percent, but you should be aware of the direction and magnitude of the bias it introduces.