How Present Value Actually Works in Practice
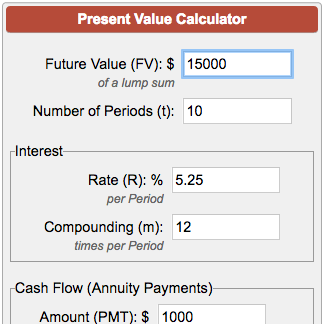
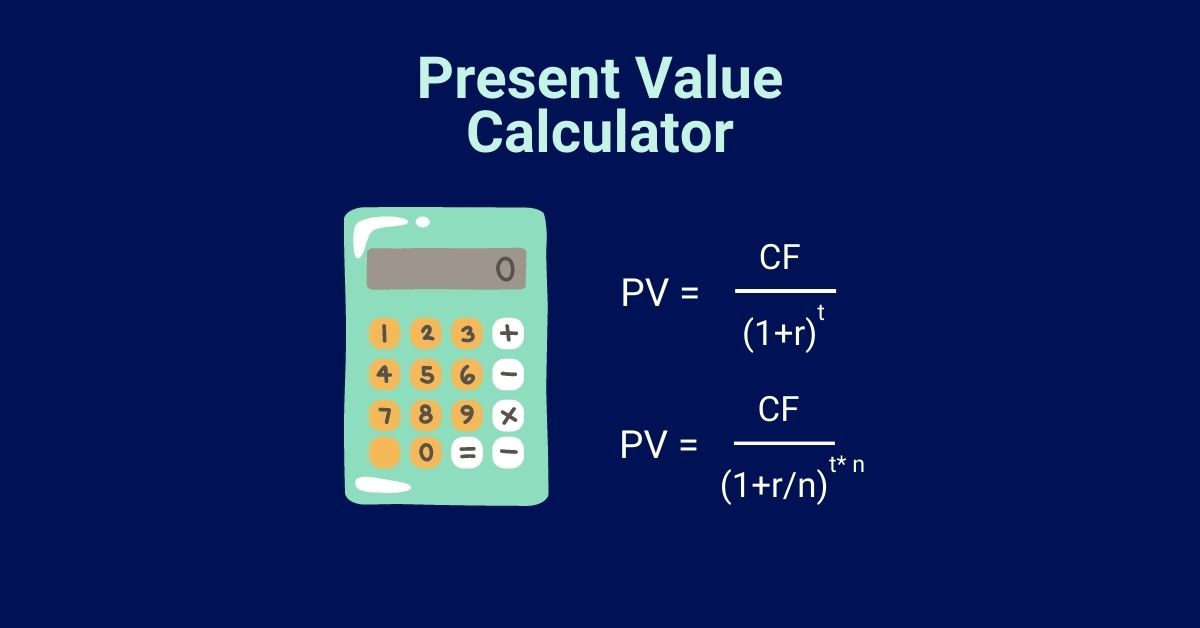
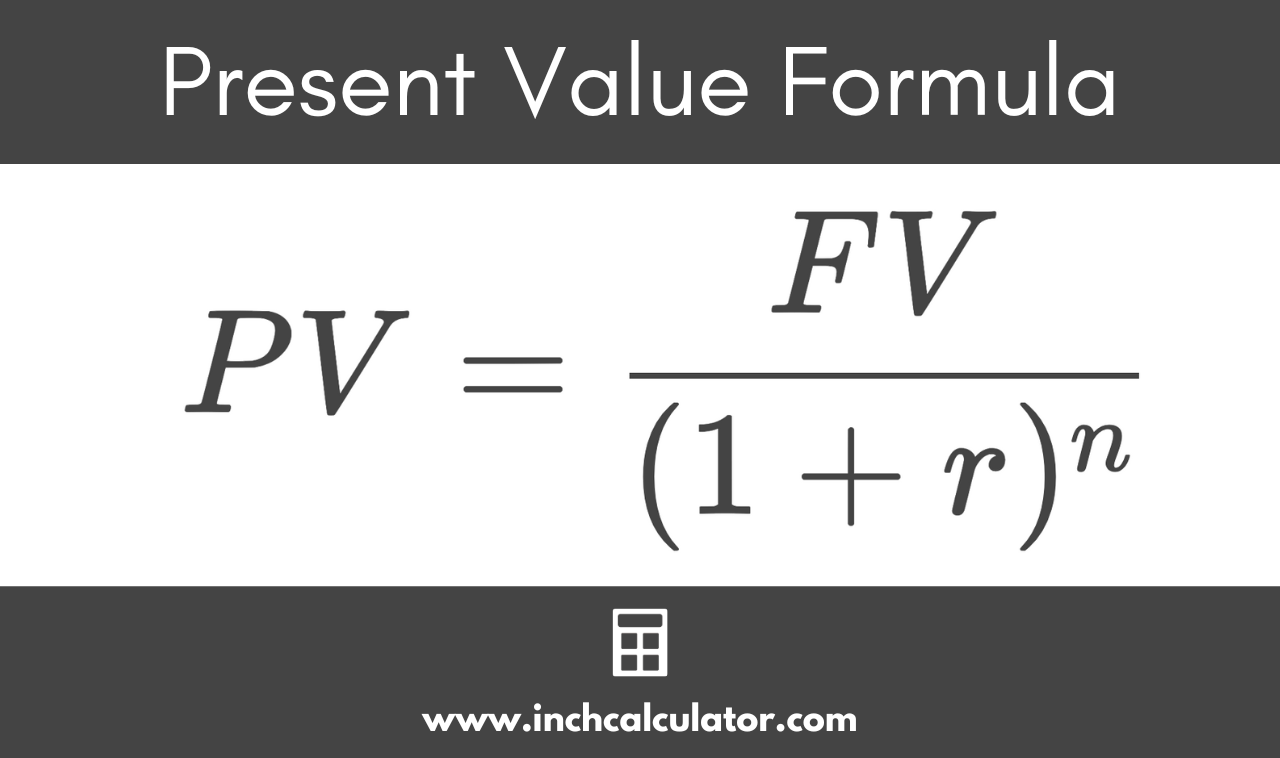
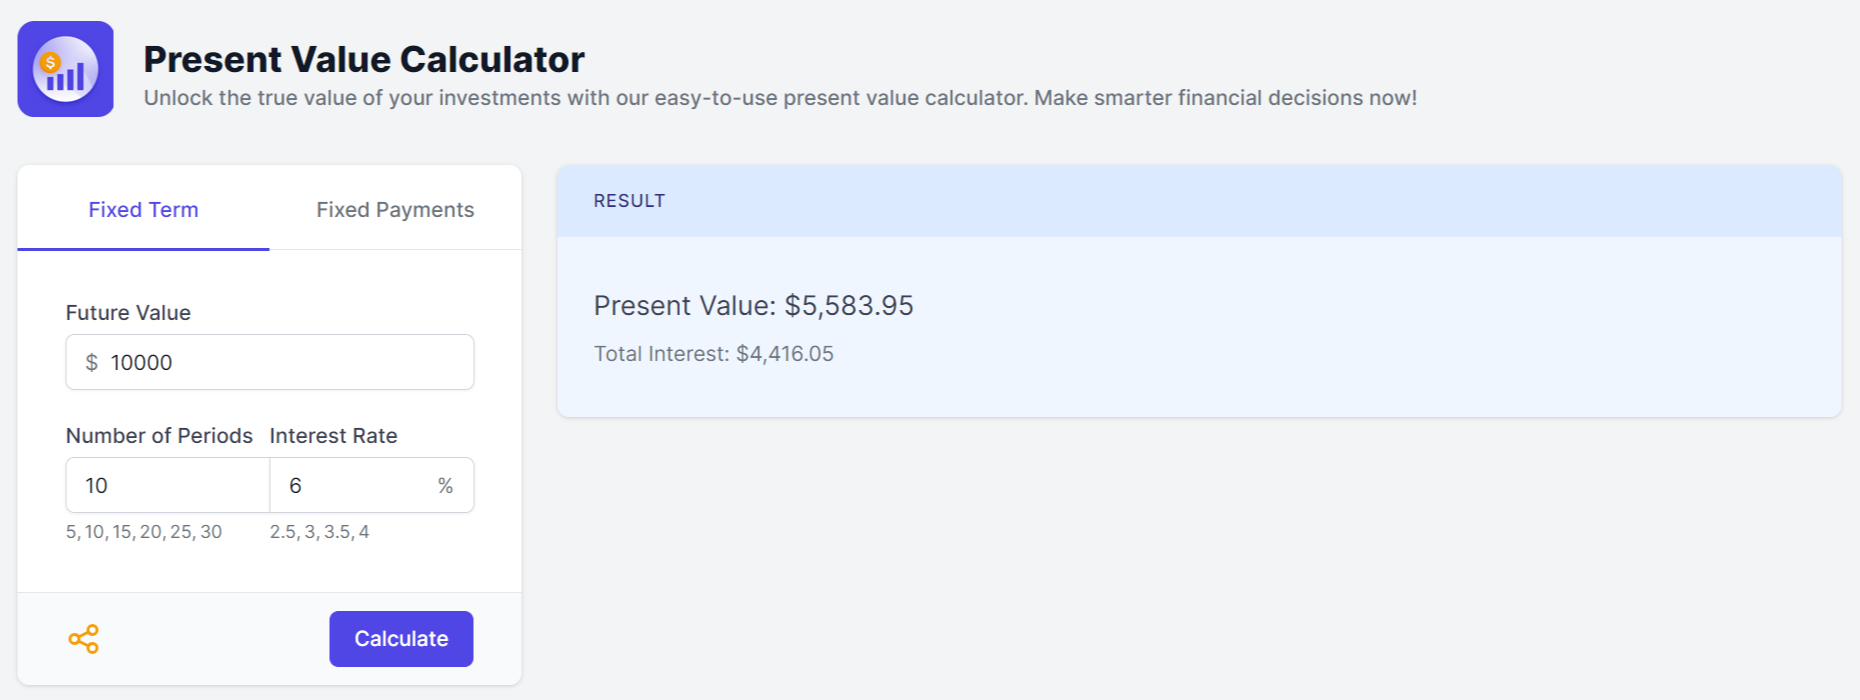
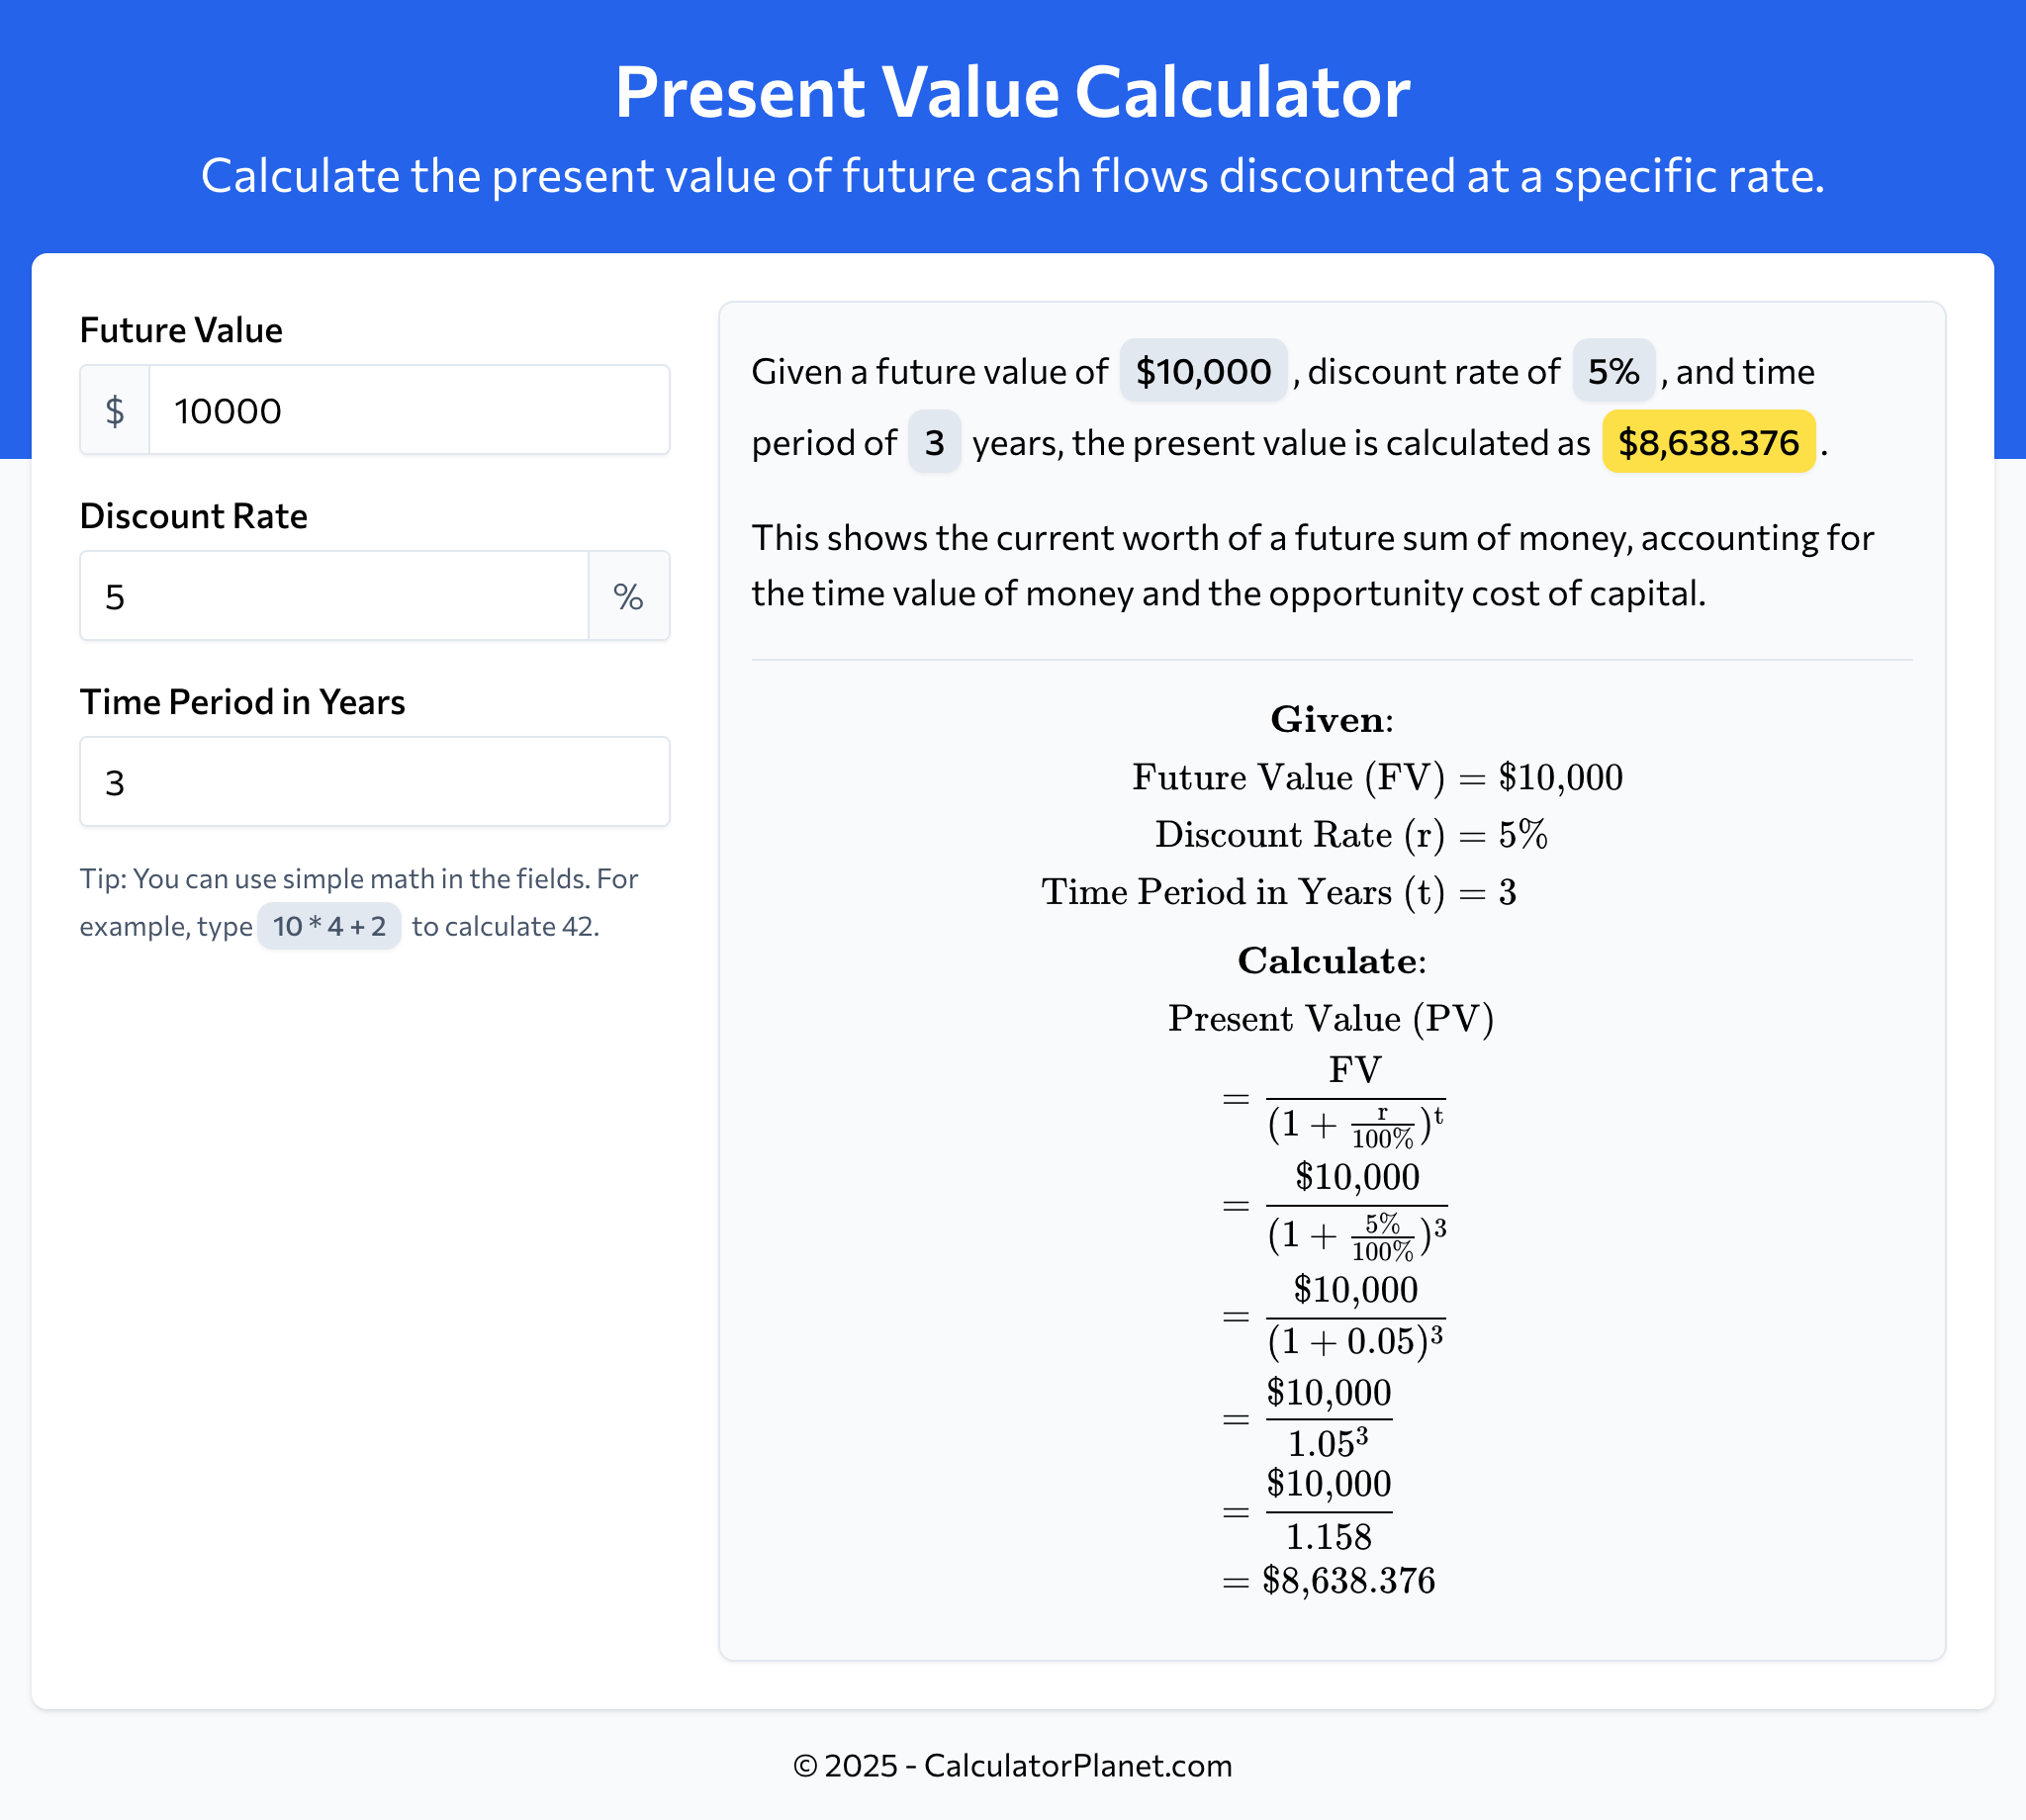
Most people think Present Value is just a formula you plug numbers into. It is, but the way you set it up matters more than the math itself. I spent years doing this for capital budgeting, lease evaluations, and bond pricing before I stopped caring about being clever about it. The basic formula is straightforward: PV = FV / (1 + r)^n. Future value divided by one plus the discount rate, raised to the number of periods. That is the entire thing. Everything else is just adjusting for annuities, irregular cash flows, or varying discount rates across periods. Present Value Calculator tools exist because doing this by hand for a long series of cash flows is tedious, not because the concept is hard. A good calculator lets you input a stream of future payments and spit out what that stream is worth today. You pick the discount rate, enter the cash flows, hit calculate. Done.I remember working on a project where the cash flows weren't annual—they came in quarterly, and the discount rate was given as an annual nominal rate compounded monthly. The mismatch between compounding frequency and payment frequency threw off every standard calculator I tried. The workaround was to convert the nominal annual rate to an effective quarterly rate first using (1 + r_nominal/m)^m-1, then plug that into the quarterly cash flow model. Took me about ten minutes once I realized that was the issue. Most junior analysts I worked with spent two days on it because they kept feeding the raw annual rate into a quarterly model.
Common Misunderstandings That Cost Real Money
One thing nobody tells you upfront: the discount rate you choose can make or break your entire analysis, and most people pick it based on habit rather than anything rigorous. Using your company's weighted average cost of capital as a blanket discount rate for every project is a lazy approach that works fine for rough screening but fails when you need precision. Different projects carry different risk profiles. A infrastructure project with stable cash flows should use a lower rate than a R&D initiative with uncertain returns. Another pitfall is ignoring the time value of money within individual periods. If you're discounting cash flows that occur mid-year, treating them as end-of-year events shifts your result enough to matter on large deals. I've seen $50 million NPV swings from that alone on commercial real estate acquisitions.The mathematical side has a quirk most users don't notice until they hit it. When you compound more frequently than once per period, the effective rate grows but at a diminishing rate. Moving from annual to semi-annual compounding makes a real difference. Moving from monthly to daily compounding on a ten-year horizon might change your result by fractions of a percent. For most practical purposes, annual or semi-annual compounding is sufficient. Only institutional fixed income desks bother with continuous compounding, and even then it is mostly about convention, not precision.
Setting Up a Calculator You Can Trust
If you are building your own tool or configuring a spreadsheet, the first decision is how to handle irregular cash flow dates. Some Present Value Calculator implementations assume even periods. That works for bonds with fixed coupon dates. It fails immediately for venture capital investments, construction draw schedules, or any situation where payments land on weird dates. The cleanest approach is to discount each cash flow individually using the exact fraction of periods between today and that cash flow date. So instead of (1 + r)^3 for year three, you compute (1 + r)^3.27 if the payment arrives 3 years and about three months from now. It adds a line to your model but eliminates a whole class of errors. I use a simple Excel setup: column A for dates, column B for cash flow amounts, column C for the fraction of years between the date and today using actual day counts divided by 365. Column D is the discount factor. Column E multiplies the cash flow by the discount factor. Sum column E and you have the present value. It takes about five minutes to build and saves you from relying on any black-box tool.Limitations Worth Knowing About
Present Value calculations assume a known discount rate, but discount rates are estimates. They shift with market conditions, central bank policy, and the specific risk environment at the time of analysis. A model that spits out a clean present value number creates a false sense of precision. The output is only as good as the inputs, and the discount rate input is almost never known with certainty. The method also breaks down when cash flows are deeply uncertain in direction, not just magnitude. If you are valuing a patent that might generate positive cash flows under one scenario and total zero under another, discounting expected values gets you an answer, but that answer can be misleading if the scenario probabilities are subjective. In those cases, decision tree analysis or real options frameworks give you more useful information than a single present value figure.There is also the inflation trap. You can either discount nominal cash flows with a nominal rate or real cash flows with a real rate, but mixing them produces garbage results. I once saw a procurement team discount projected cost savings in nominal terms using a real discount rate and then wonder why their NPV looked suspiciously high. The fix was straightforward—adjust the cash flows for expected inflation before discounting—but catching the error took three review cycles because the calculation itself was internally consistent, just based on the wrong pairing of inputs.
Get the Full Details