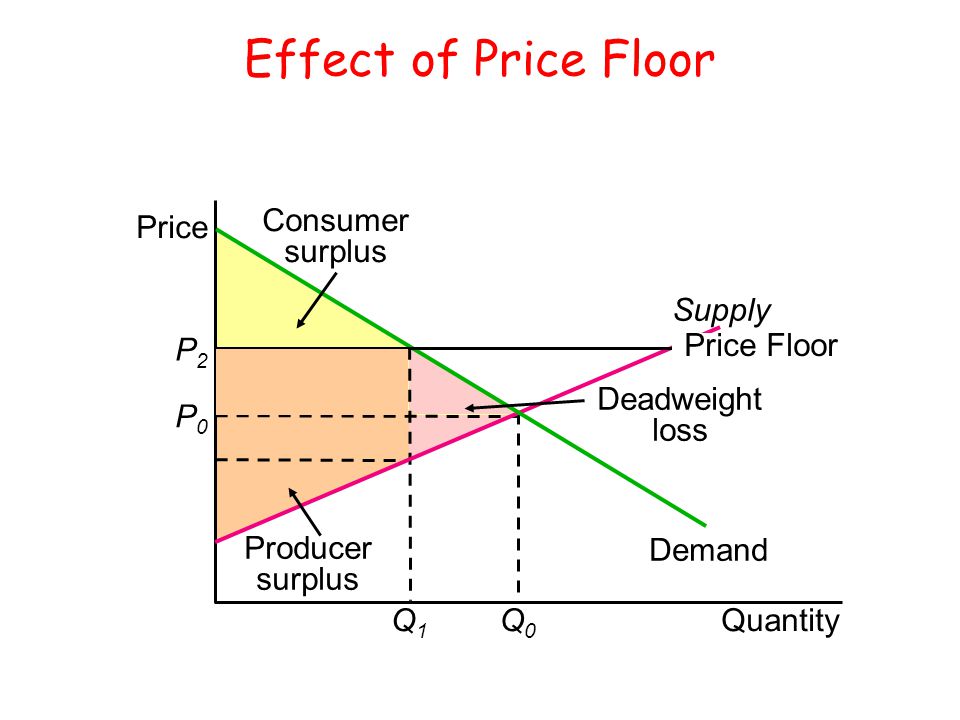
Setting a minimum price above equilibrium
I learned about price floors the hard way, back when I was consulting for a regional agricultural cooperative trying to stabilize wheat prices. They wanted a guaranteed minimum payment per bushel that sat well above what the market would naturally settle at. Everything looked fine on paper until we started seeing what actually happened to the surplus and the people who needed wheat the most. A price floor is a government-mandated minimum price that sits above the equilibrium point where supply meets demand. When you enforce it, the quantity supplied exceeds the quantity demanded, creating a surplus that nobody asked for. The market can no longer clear itself. Buyers drop out because the price is too high, while producers keep churning out more because the price is attractive to them.
Price Floor And Deadweight Loss
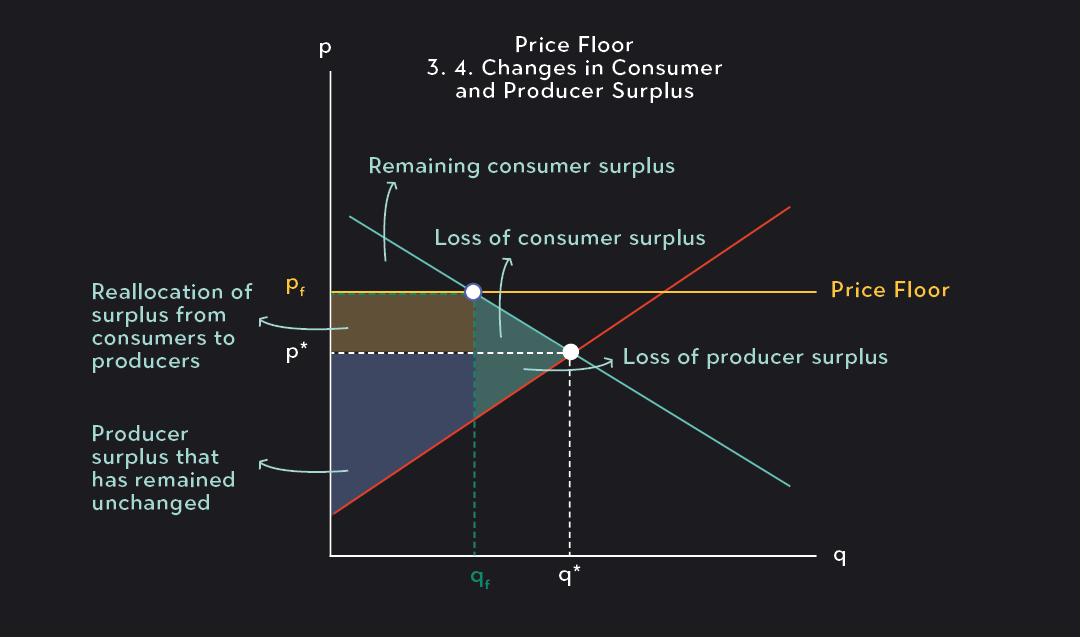
The deadweight loss from a price floor is the total welfare that disappears when the market is forced away from equilibrium. It is the triangle formed between the supply curve, the demand curve, and the quantity actually traded under the floor. Buyers who valued the product more than it cost to produce but less than the floor price simply walk away. Sellers who could have produced efficiently at the market price now face uncertainty about whether their output will sell at all. In practice, I calculate this by finding the equilibrium quantity first, then noting the quantity traded under the floor, and integrating the area between the supply and demand curves across that gap. The formula is straightforward, but the real-world messiness comes from estimating where those curves actually are. Demand elasticity matters enormously. A staple crop like wheat has relatively inelastic demand, so the quantity drop is modest but the surplus balloons. A luxury good with elastic demand sees buyers flee quickly, and the deadweight loss grows faster than the surplus. One thing beginners consistently miss is that the deadweight loss triangle assumes the entire surplus is wasted. That is rarely true. In my agricultural consulting work, the government often steps in and purchases the surplus for storage, export subsidies, or humanitarian programs. When they do that, the surplus disappears from the market entirely, which actually increases the deadweight loss beyond the standard triangle because you are now paying taxpayers to move product that nobody wanted at the floor price. The fiscal cost plus the welfare loss compounds.
I encountered a particularly ugly edge case with a dairy price support program where the government bought the surplus but the storage facilities were already maxed out. Instead of storing it, they sold it below cost on international markets, which depressed global prices and hurt farmers in developing countries who never agreed to the scheme in the first place. The deadweight loss was no longer contained within the domestic market. It leaked across borders, and trying to quantify that spillover took me three weeks of customs data and shipping manifests just to get a rough estimate. The workaround I settled on was to model the price floor not as a hard constraint but as a range with probability weights for different government intervention scenarios. Rather than assuming the surplus would be destroyed, stored, or exported, I assigned a 40 percent probability to domestic storage, 35 percent to subsidized export, and 25 percent to waste or donation based on historical spending patterns. This gave a weighted expected deadweight loss that was far more useful for policy recommendations than the textbook triangle. Another counter-intuitive point is that price floors can sometimes reduce deadweight loss under very specific conditions, though this is rare and depends on market structure. If the supply curve is perfectly elastic and the demand curve is extremely steep, the quantity reduction is minimal and the surplus is small enough that the administrative cost of enforcing the floor exceeds the welfare loss from the mispricing. In those narrow cases, a price floor might be cheaper than the alternative of monitoring and adjusting quotas every quarter.
Get the Full Details
I once advised a small island nation considering a fish price floor to protect local fishermen. The demand for fresh fish was so inelastic that the quantity traded barely moved, and the deadweight loss was smaller than the administrative cost of running the price monitoring system. We recommended a direct subsidy to fishermen instead, which achieved the same income support goal without distorting the market price or creating a surplus that needed disposal. Here is where the method breaks down completely. Price floor analysis assumes you know the supply and demand curves with reasonable accuracy. In reality, you rarely do. Agricultural supply curves shift every season based on weather. Demand curves shift based on consumer tastes, substitute availability, and income changes. If your curve estimates are off by even ten percent, the deadweight loss calculation can be wrong by fifty percent or more. I have seen policy reports use stale elasticity estimates from five years prior, which led to floor prices that created surpluses three times larger than projected. The biggest bottleneck is data. You need point-in-time data on quantities and prices across the relevant market segment. For niche markets or emerging products, this data simply does not exist. You end up relying on surrogate markets or expert judgment, both of which introduce error. In one project for a renewable energy certificate floor price, we had to use data from a related fossil fuel credit market as a proxy because the certificate market was three years old and had almost no trading volume. The deadweight loss estimate was essentially a guess wrapped in a spreadsheet.
If you are working with a market where the price floor is likely to be temporary or politically unstable, consider modeling the floor as a scenario analysis rather than a fixed parameter. Run the calculation under multiple floor levels and document how the deadweight loss scales. This approach is more honest about uncertainty and usually more useful for decision-makers than a single point estimate that implies false precision. I also recommend checking whether the price floor interacts with existing quotas, tariffs, or subsidy programs. These policy layers compound in non-linear ways. A price floor combined with a production quota can actually reduce deadweight loss compared to the floor alone because the quota limits supply and prevents the surplus from growing. But the quota creates its own distortions, and the net welfare effect depends on which instrument is more efficient at allocating the limited quantity. The practical takeaway is that price floors always create deadweight loss, but the size of that loss is highly sensitive to your assumptions about elasticity, government behavior, and market structure. The textbook triangle is a starting point, not an answer. Get the data right, test multiple scenarios, and be honest about what you do not know.


