How Principal Financial 401K Withdrawal Actually Works When You Need the Money
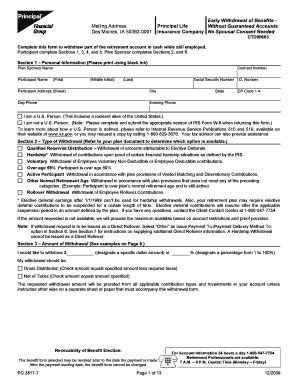
Most people discover Principal Financial 401K Withdrawal options when they already have a financial problem. The account balance looks decent on paper, but you need cash now and the withdrawal process feels like climbing through a maze. I spent three years helping my company's HR team deal with these requests, and I learned the hard way that the documentation requirements vary wildly depending on your situation. Start by logging into your Principal account at principal.com. You will find the withdrawal section under the "Transactions" or "Services" menu. Principal offers several withdrawal types: hardship distributions, loans, and regular withdrawals after age 59½. Each has completely different tax implications and penalty structures that most people don't understand until it is too late. Hardship withdrawals require you to certify that you have an immediate and heavy financial need. Principal will ask for documentation—medical bills, eviction notices, or repair estimates. The review process usually takes 5-7 business days if your paperwork is clean. I once had a client whose hardship application got rejected because he submitted a credit card bill instead of a medical statement. Principal's system flagged it as insufficient documentation. He resubmitted with the correct paperwork and got approved within 3 days.
401K loans from Principal are often cheaper than people think. You can borrow up to 50% of your vested balance or $50,000, whichever is less. The interest rate typically runs about 1-2% above the prime rate. You pay that interest back to your own account through payroll deductions. Most people miss the catch: if you leave your job, the loan becomes due immediately. If you cannot repay it within 60-90 days, it converts to a distribution and you owe taxes plus a 10% early withdrawal penalty.
Common Pitfalls with Principal Financial 401K Withdrawal
The biggest mistake people make is not understanding the tax withholding. Principal automatically withholds 20% for federal taxes on most distributions. If you need the full amount, you will need to find that money elsewhere to cover the shortfall. I helped someone who withdrew $10,000 expecting to receive $10,000. She got $8,000 after withholding. She had to dig up $2,000 from savings to cover the emergency she was trying to fix. Another issue is the state tax treatment. Some states tax 401K withdrawals differently than the federal government. California and New York are particularly aggressive about retirement account taxation. If you move to a high-tax state after taking a Principal Financial 401K Withdrawal, you might owe additional state taxes when you file your return. Check your state's rules before initiating any distribution. Principal's online portal sometimes shows outdated account balances. The displayed value might reflect last month's earnings, not today's. This matters when you calculate withdrawal amounts. I noticed this discrepancy when a colleague tried to withdraw her entire balance and found she was $300 short because the market had dropped overnight. Always verify your current balance by calling Principal's member services before submitting a withdrawal request.
Get the Full Details
When Principal Financial 401K Withdrawal Makes Sense
Retirement age distributions are the obvious choice if you are 59½ or older. You avoid the 10% early withdrawal penalty entirely. taxes still apply at your ordinary income rate, but that is usually manageable. Required Minimum Distributions kick in at age 73 under current SECURE 2.0 rules. Principal will calculate your RMD automatically, but you should verify the amount each year. The IRS imposes a 25% penalty on excess deficiencies if Principal miscalculates your required distribution. Hardship withdrawals make sense for genuine emergencies, not lifestyle expenses. Principal defines hardship as medical costs, education expenses, home purchase, or prevention of eviction. They do not consider vacation plans, debt consolidation, or general living expenses. The bar is higher than most people expect. I watched someone get denied a hardship withdrawal for car repairs because Principal determined he could finance the repair through a personal loan instead.
Alternative Options Before Taking a Principal Financial 101K Withdrawal
Consider a roth conversion if you have a roth option available. You pay taxes now but withdraw tax-free in retirement. This strategy works well if you expect to be in a higher tax bracket later. The conversion process through Principal usually takes 2-3 weeks. You receive confirmation once the funds transfer between accounts. Partial withdrawals might solve your problem without emptying the account. Principal allows you to withdraw a portion of your vested balance while leaving the rest invested. This approach reduces your tax liability compared to a full distribution. The minimum withdrawal amount varies by plan, but most allow as little as $500 per transaction. If you are between jobs, you might qualify for a rollover to an IRA instead of taking a distribution. This preserves your tax-deferred status and avoids immediate taxation. Principal facilitates rollovers directly, but you must initiate the request within 60 days of receiving the distribution check. Failure to complete the rollover within this window triggers full taxation plus penalties.
Some employer plans offer in-service withdrawal provisions that allow access to funds before retirement age. Principal supports these arrangements if your plan documents permit. Check with your HR department to see if your particular plan includes this option. The availability varies significantly between employers, even within the same industry.