Working With Accounting And Finance: The Stuff Nobody Teaches You In School
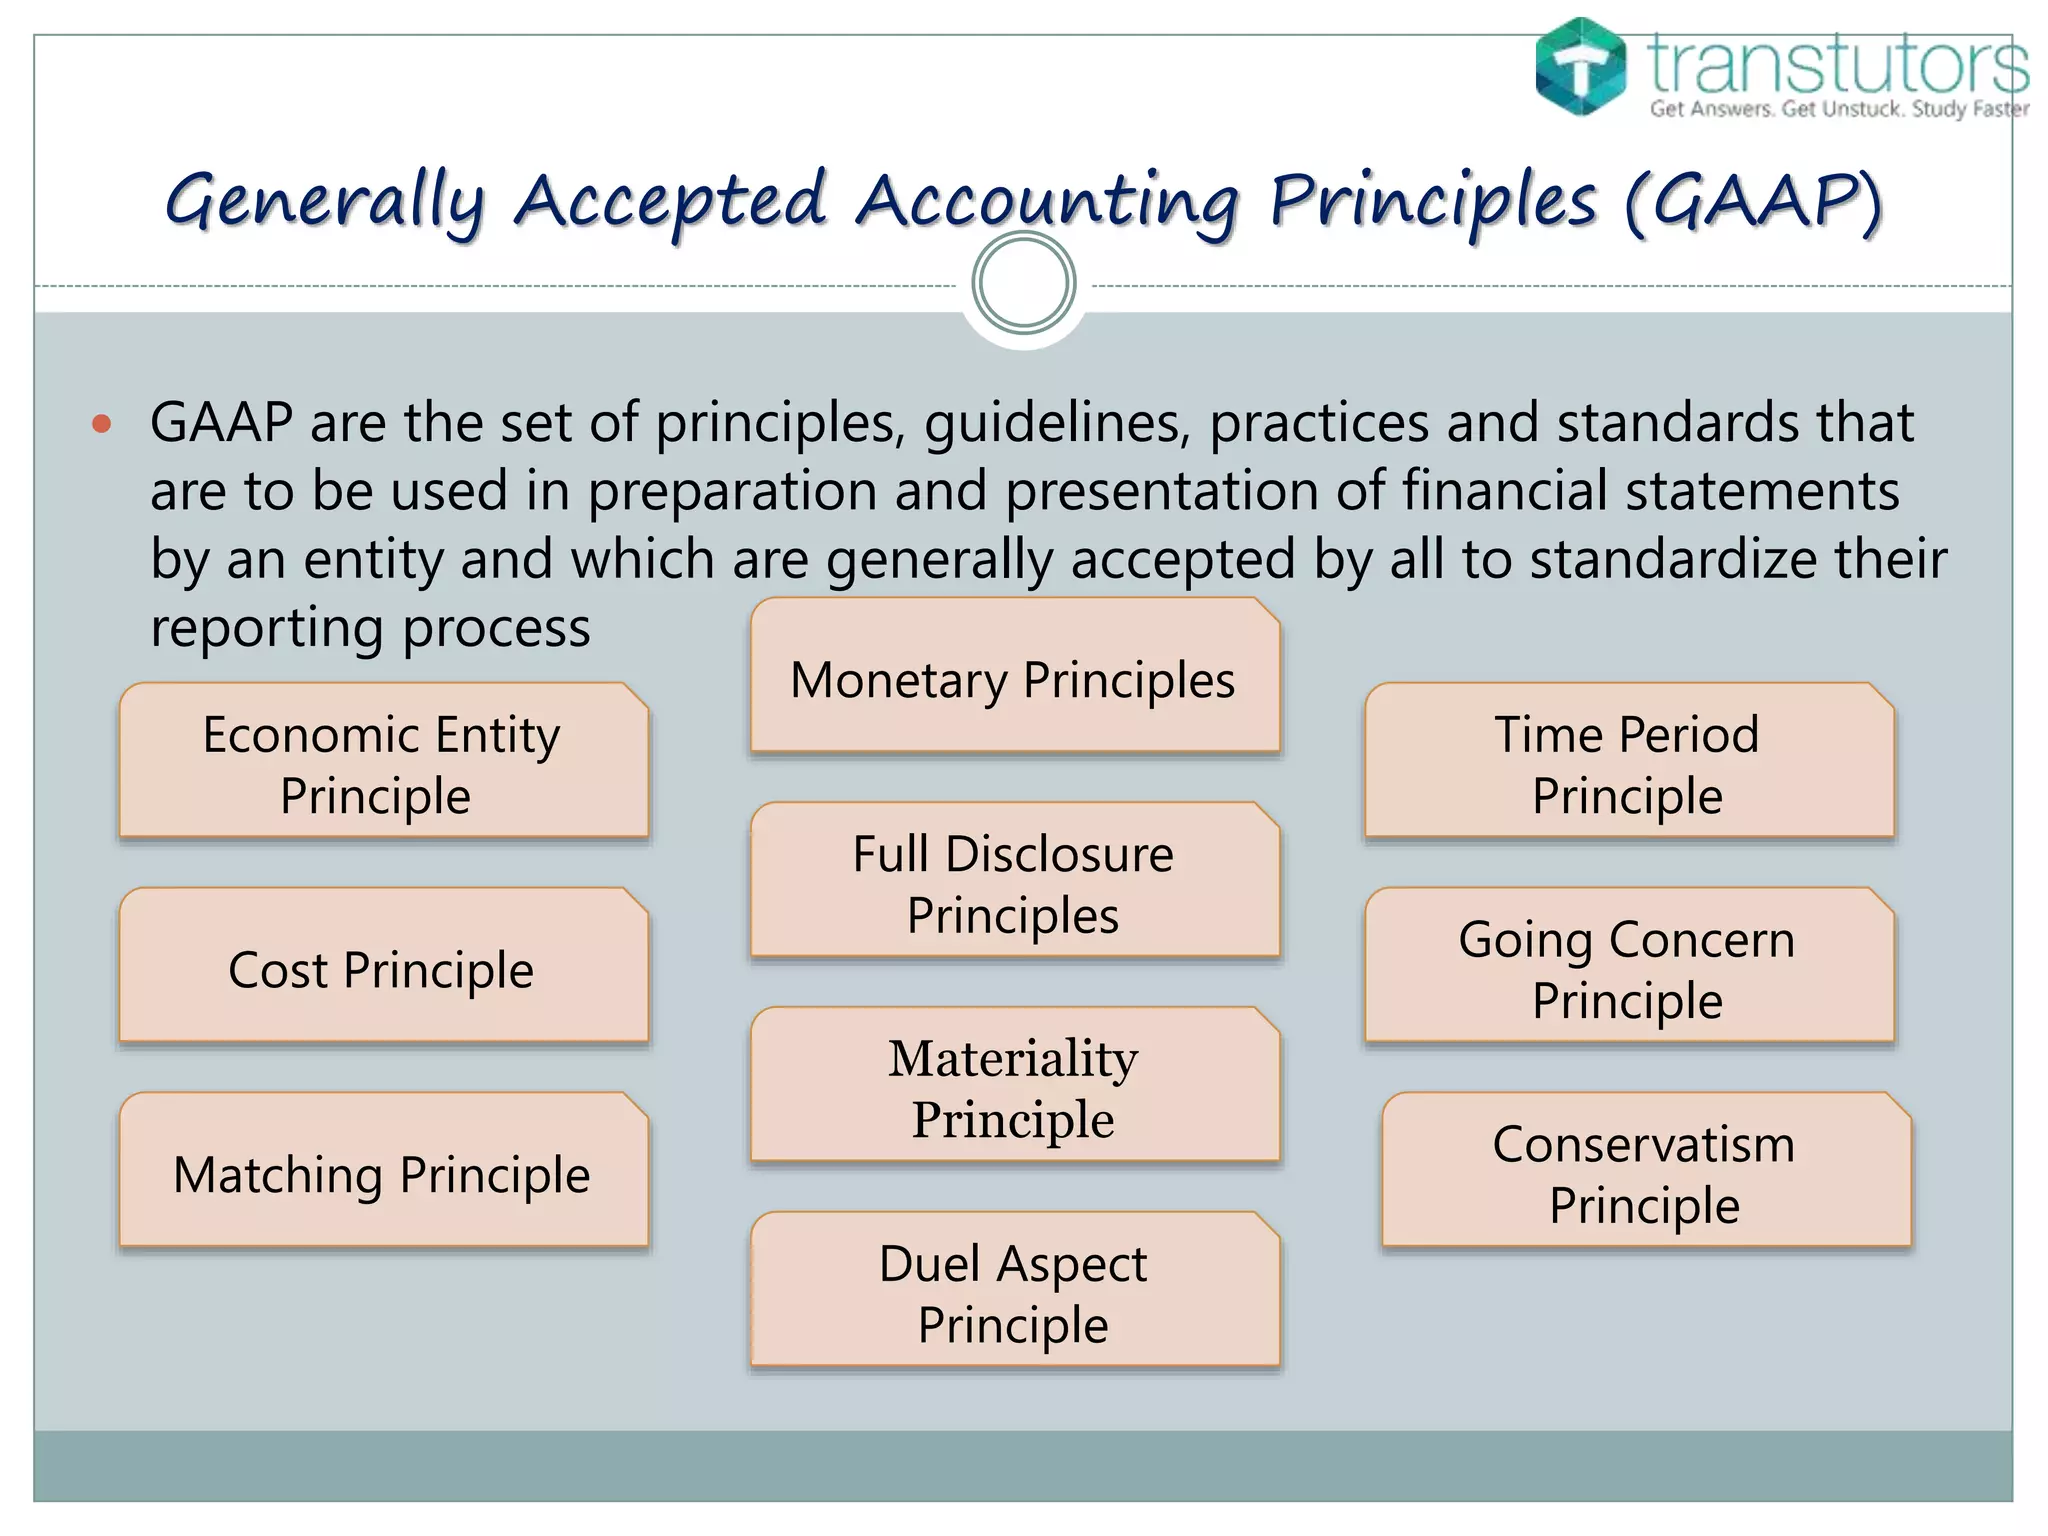
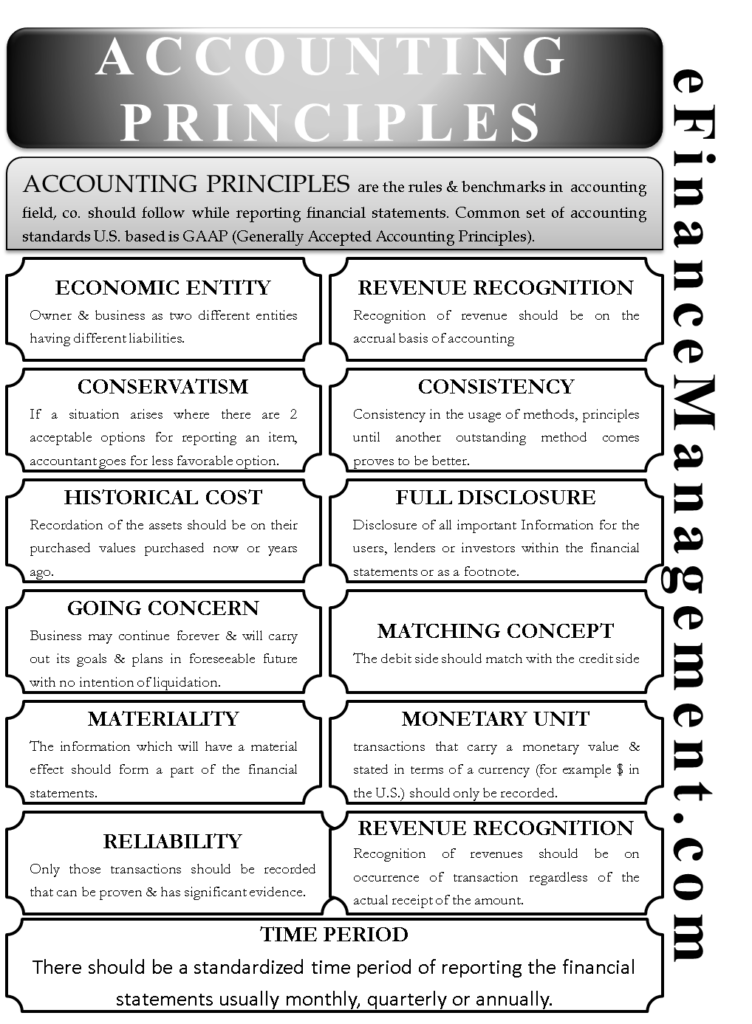
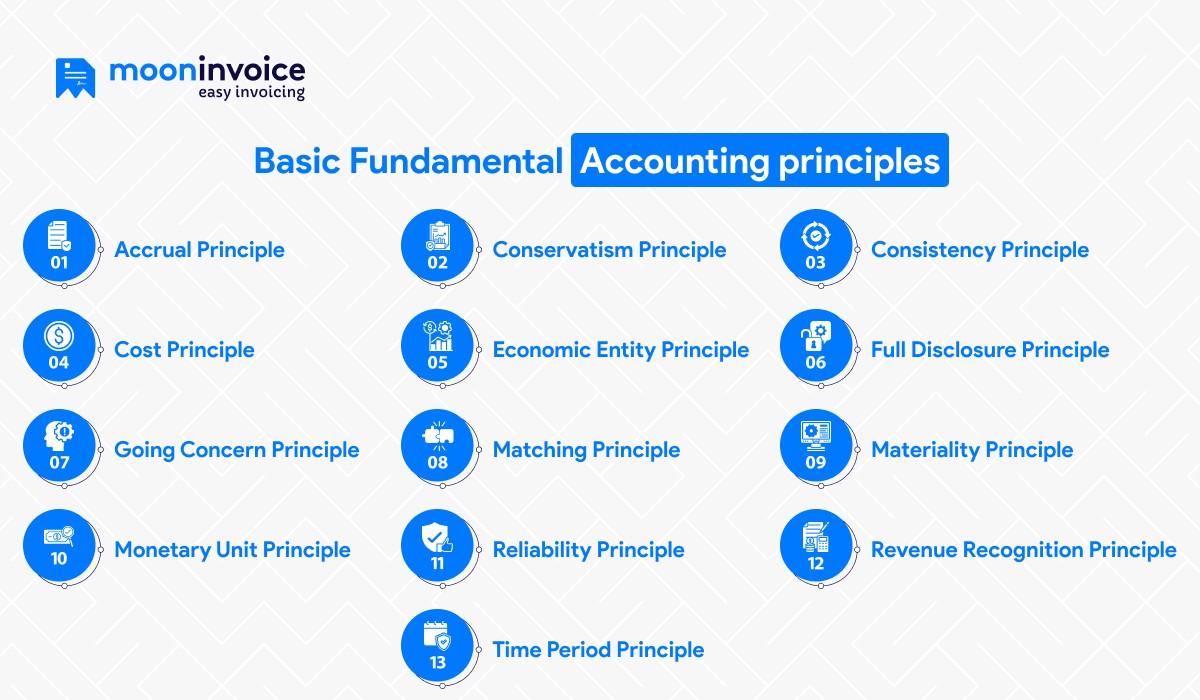
Most people learn accounting as a set of rules. Revenue goes here, expenses go there. The accounting equation balances and everyone goes home happy. It works fine until you hit a real situation where two rules contradict each other or a company needs to make a judgment call that isn't in the textbook. That is where actual finance work lives. The core principles are not complicated. They are just easy to get wrong when you are rushing. The revenue recognition principle says you record revenue when it is earned, not when you get paid. The matching principle says expenses go in the same period as the revenue they helped generate. The going concern assumption means you prepare financials assuming the business will keep operating, which affects how you value assets. Conservatism means you recognize losses sooner than gains. Materiality means you do not bother with perfect precision on small items. These are simple enough until a transaction touches two of them at once. I have seen junior accountants get tripped up by the interaction between revenue recognition and matching, particularly with service contracts that span multiple periods. You recognize the revenue over time but you need to match the costs properly. A common mistake is to expense everything upfront because it feels safer. It is not. That understates your gross margin in early periods and inflates it later, which looks worse than simply allocating costs correctly.
The accrual versus cash method decision matters more than most people think. Accrual accounting gives you a realistic picture of profitability. Cash accounting is simpler but it can make a profitable quarter look terrible if you had a bunch of big payments go out that month. If you run a service business, I would strongly recommend accrual from the start. The cleanup cost of switching later is annoying. You end up rewriting statements for every period you were on cash.
Methods You Will Actually Use
Here is the straightforward way I approach any new accounting problem. First, identify the transaction type. Is it revenue, expense, asset, liability, or equity? Second, figure out the timing. When did the economic event happen versus when cash moved? Third, check materiality. Is the amount large enough to require precise treatment or can you book it roughly? Fourth, verify against the applicable standard. ASC 606 for revenue, ASC 842 for leases, ASC 350 for goodwill impairment. Not everything needs a standard, but the ones that do matter a lot. I learned this sequence the hard way on a mid-size SaaS company around 2019. They had bundled software subscriptions with implementation services. The contract didn't break out the pricing for each component. Revenue should have been allocated across the performance obligations using standalone selling prices. Instead, the previous bookkeeper had recognized everything as subscription revenue over the contract term. Implementation work was expensed as incurred. It understated cost of revenue and inflated gross margin by about twelve percent. The fix took two days. I pulled every active contract from the prior year, identified the ones with bundled services, estimated standalone selling prices based on what the company charged other customers, and ran a catch-up adjustment. I did not restate the audited financials because the error was not material to the total, but I flagged it clearly in the notes. That is the practical balance between perfection and reality.
Get the Full Details
Edge Cases That Trip People Up
Lease accounting under ASC 842 is where most small to mid-market companies struggle. You need to identify leases, calculate the lease liability at present value, and record a right-of-use asset. The discount rate choice matters. Using your incremental borrowing rate versus the rate implicit in the lease can change your liability by a meaningful amount, especially on longer leases. I once saw a restaurant group miss this because their landlord refused to disclose the implicit rate, and they just left the entries off entirely for eighteen months. Inventory valuation is another area where textbook examples fail. LIFO, FIFO, and weighted average produce different numbers, and the difference is not academic when you are calculating COGS and taxes. If you are on LIFO and prices are rising, your taxable income will be lower than FIFO. That is the whole point. But LIFO conformity means you also have to use it for financial reporting. Some companies switch to FIFO for tax purposes without realizing they lose the LIFO reserve benefit. The interaction between LIFO layers and inflation can create surprises if you are not tracking layer formation carefully. Foreign currency translation is worse than most people expect. You translate assets and liabilities at the current rate and equity at historical rates. Revenue and expenses at the average rate. The resulting translation adjustment goes into other comprehensive income, which is equity, not net income. This creates a weird situation where your net income looks stable while equity swings wildly. I worked with a manufacturer that had euro-denominated payables and dollar revenue. A twenty percent swing in the euro moved their equity by fifteen percent without touching earnings. When the board asked why equity dropped, the explanation took me a full afternoon to make digestible.
Common Pitfalls And How To Avoid Them
The biggest mistake I see is confusing bookkeeping with accounting. Bookkeeping records transactions. Accounting interprets them. A bookkeeper posts an invoice. An accountant decides whether it is a capital expenditure or an expense, whether revenue is earned yet, whether a reserve is needed. If your process stops at posting, you are not doing finance work. Another pitfall is relying on automated software without checking the logic. QuickBooks and Xero do nice things automatically, but automation means you get the wrong answer faster. I have seen recurring journal entries set up to reverse themselves when they should not, leading to duplicated revenue recognition across quarters. Always trace the automation back to the source transaction. Impairment testing is another area where people cut corners. Goodwill impairment testing is required annually, or sooner if indicators exist. The old method tested goodwill at the reporting unit level using fair value comparisons. The new method, ASU 2017-04, simplified it but some companies still skip it entirely because it feels tedious. Skipping it is not an option if you have goodwill on your balance sheet. I once found a company that had not tested impairment in five years after an acquisition that clearly underperformed. The goodwill was worth less than half its book value. The adjustment wiped out two years of reported earnings in one quarter.
Tools That Actually Help
FASB ASC is the primary reference for US accounting standards. It is free at fasb.org. Download the PDF version if you want offline access, but the online searchable version is faster. IFRS is available at ifrs.org and is free for individuals. If you work in public markets, you also need SEC filings and staff accounting bulletins for context. For practice, I recommend working through real financial statements instead of textbook problems. Pick a public company, pull their 10-K, and trace one revenue line item back to the footnote. See how they recognize it. Check their critical accounting policies section. You will learn more from one real annual report than from ten hypothetical exercises. If you need to run calculations, Excel is still the standard. I use macros sparingly. The spreadsheet itself should show your logic transparently so someone else can audit it later. Black box models cause more problems than they solve. Save every working file with version numbers and dates. I lost three weeks of work once because I overwrote a file without saving a copy first. It was not dramatic but it was avoidable.
Financial statement analysis requires ratio computation, trend analysis, and benchmarking against peers. Ratio calculation is mechanical. The judgment comes in deciding which ratios matter for your specific situation and whether the underlying numbers are distorted by accounting choices. Two companies with identical operations can show very different ratios if one depreciates differently or uses a different revenue policy. Always adjust for those differences before drawing conclusions.
Where This Breaks Down
No framework covers everything perfectly. Revenue recognition guidance is detailed but still leaves room for interpretation on complex arrangements. Lease accounting is thorough but extremely burdensome for companies with hundreds of small leases. Goodwill impairment rules are simpler now but the underlying estimation problem remains. Fair value measurements rely on market data that may not exist for illiquid assets. These are known limitations, not secrets. The best practitioners know where the rules are fuzzy and document their assumptions clearly. Automation tools are improving but they cannot handle judgment calls. You still need someone who understands the principles to review entries, challenge assumptions, and decide when to deviate from standard treatment. That is the part machines cannot replace yet, and it will likely stay that way for the foreseeable future.