Financial management basics that actually matter
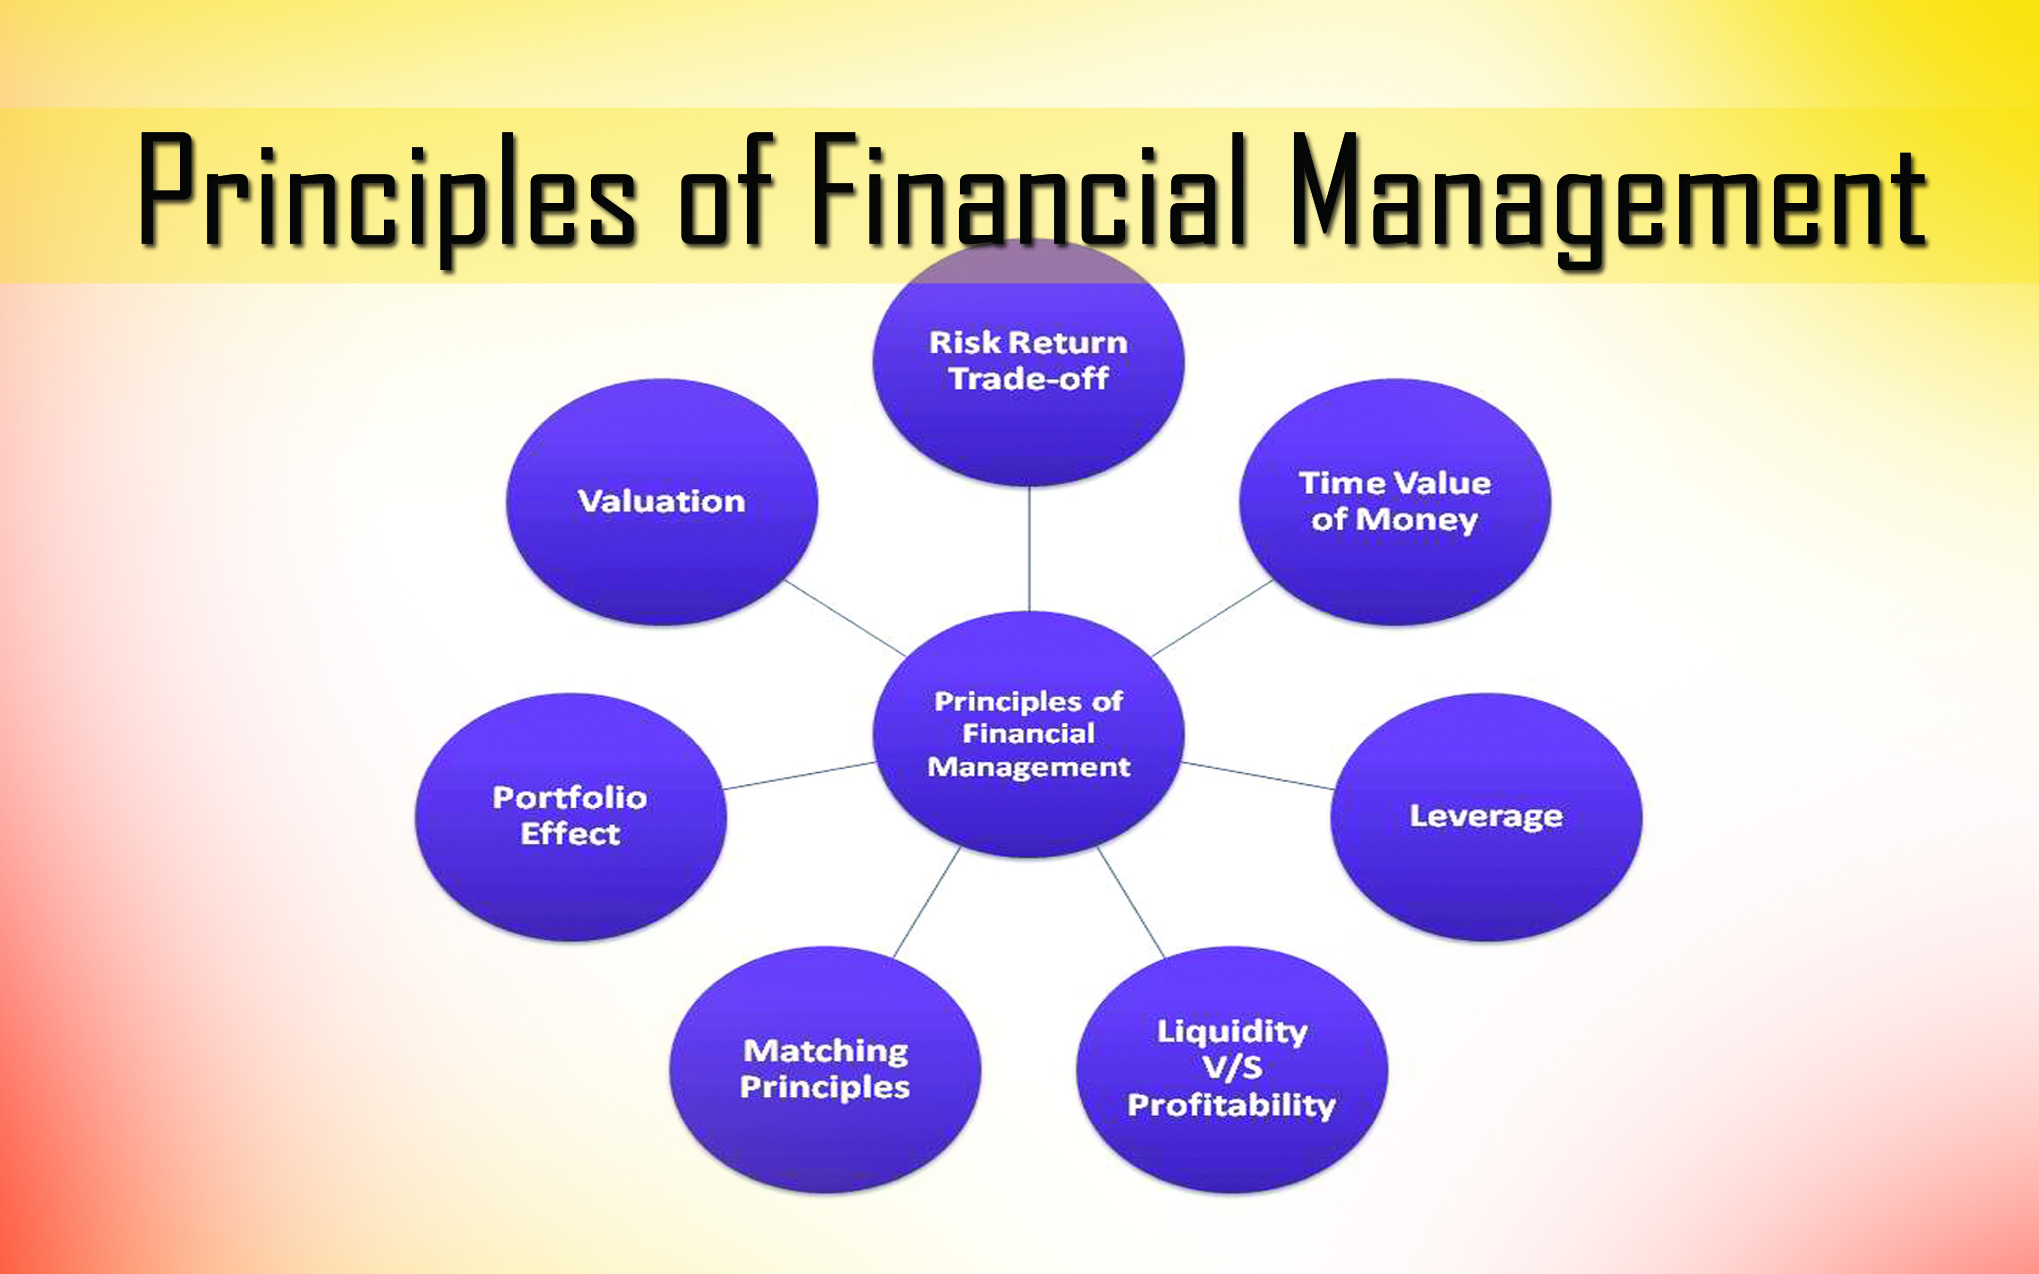
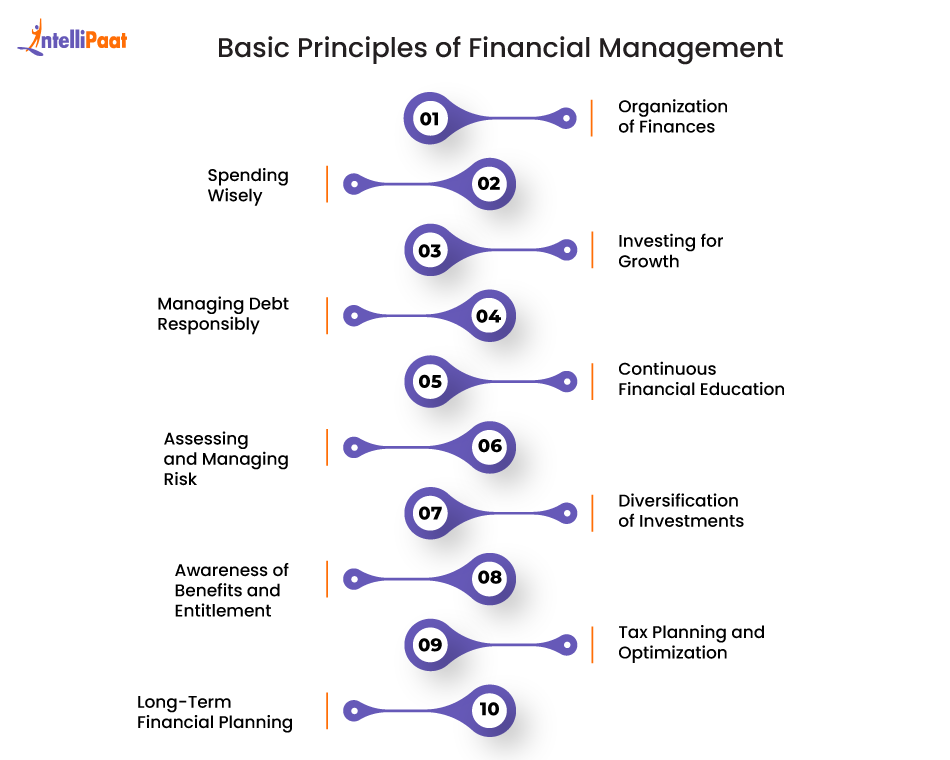
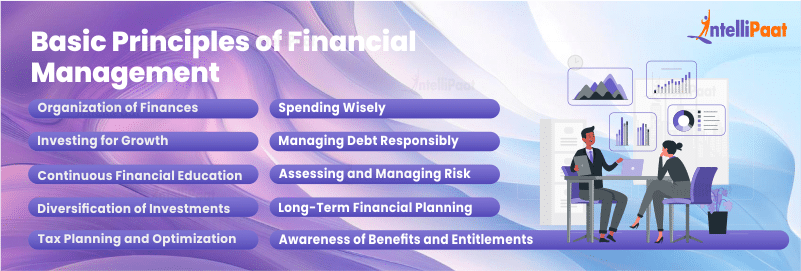
Most people think financial management is about spreadsheets and forecasting models. It isn't. It's about keeping cash from disappearing when something goes wrong. I learned this the hard way back in 2018 when a major vendor raised their payment terms from net-30 to net-60 overnight. Our accounts payable didn't change. We had two months of negative cash flow before anyone noticed. That was my crash course in working capital management. The Principles Of Basic Financial Management are really just three things done consistently: track your cash position daily, keep costs variable when revenue is variable, and never spend money you haven't actually received yet. Everything else is decoration.
Understanding the core framework
Financial management rests on understanding the relationship between liquidity, profitability, and solvency. These three concepts pull in different directions. Profitability doesn't guarantee you can pay your bills next week. Solvency doesn't mean you won't run out of cash tomorrow. Liquidity is the bridge between them. Most small businesses fail because they optimize for profitability while ignoring liquidity. I worked with a company once that was profitable on paper for three consecutive years. Their income statement looked fine. Their balance sheet was manageable. They closed down because every receivable was 90 days past due and they couldn't cover a single payroll. Profit is an opinion. Cash is a fact.
Practical applications in daily operations
Here is how this plays out when you are actually running something. You need to maintain a minimum cash reserve that covers at least 30 days of operating expenses. Not revenue. Expenses. Fixed and variable combined. When I managed a team, we calculated this number monthly using the prior quarter's actual burn rate, not budgeted figures. Budgeted figures are where things go to die. Accounts receivable management is where most people lose money. Offer discounts for early payment. I usually recommended 2/10 net 30 terms because it actually works. Customers will pay in 10 days if you give them a reason. The cost of the discount is usually less than the cost of late payment or bad debt write-offs. Run your dSO days every week, not every quarter. Three month-old receivables are already problems. Six month-old ones are losses. Inventory management follows similar logic. Carrying costs eat into margins faster than most people realize. Storage, insurance, obsolescence, and tied-up capital all add up. The Economic Order Quantity formula exists for a reason. Calculate your optimal order size based on actual demand patterns, not gut feelings or supplier minimums that are too large. I once reduced inventory holding costs by 40 percent just by ordering more frequently in smaller batches. The shipping cost increase was minimal compared to the carrying cost savings.
Get the Full Details

Cost structure optimization
Mixed costs are the enemy of financial predictability. Fixed costs create rigidity. Variable costs create flexibility. When revenue drops, you want your costs to drop with it. This is why leasing equipment instead of buying, outsourcing non-core functions, and using contract labor during peak periods makes sense. The per-unit cost might be slightly higher, but you survive downturns. I encountered a specific problem with a manufacturing client who had significant fixed overhead from leased equipment. When demand fell 30 percent during a seasonal dip, they still owed the full lease payment. The workaround was negotiating a sublease agreement for the unused capacity and converting the fixed lease to a variable usage-based arrangement with the original landlord. It took six weeks of negotiation and legal review, but it prevented a cash crisis. Depreciation methods matter more than most accountants admit. Straight-line depreciation creates predictable expenses but hides the reality that assets often lose more value in early years. Accelerated depreciation methods like double-declining balance match expenses to actual asset performance better. This affects your taxable income and cash flow timing. Choose your method based on your actual usage patterns, not just what simplifies your tax filing.
Common mistakes and how to avoid them
Using last year's budget as this year's baseline is the fastest way to embed inefficiency into your operations. I see this constantly. Someone takes the prior year's expense line and adds five percent, assuming five percent growth covers inflation and increases. It doesn't. Start each budget cycle from zero and justify every line item. The process takes longer but produces budgets that actually reflect reality. Confusing revenue with profit is another frequent error. Booking a large sale doesn't help if the gross margin is negative after direct costs. I had a situation where a team celebrated closing a major contract, then discovered the project would operate at a loss once material and labor costs were applied. The deal should have been rejected or renegotiated. Revenue without margin analysis is just noise. Ignoring the time value of money when making capital investment decisions is equally damaging. A dollar today is worth more than a dollar next year. Use net present value calculations for any expenditure over a certain threshold. I typically set the threshold at 90 days of operating expenses or one-tenth of annual revenue, whichever is lower. Anything above that threshold requires formal NPV analysis with a discount rate matching your cost of capital.
When traditional methods fail
Traditional financial management tools assume stable operating environments. They don't work well in volatile markets where input costs fluctuate wildly or demand patterns shift unpredictably. I encountered this when raw material prices doubled in four months during a supply chain disruption. Historical cost data became useless almost overnight. The workaround was implementing rolling forecasts updated monthly instead of annual budgets, and building cost escalation clauses into supplier contracts going forward. Another limitation is that standard financial ratios don't capture qualitative risk factors. Your current ratio might look healthy at 2.1, but if 60 percent of your current assets are uncollectible receivables, the ratio is meaningless. Always dig into the composition of each line item rather than accepting summary ratios at face value. Break down accounts receivable by age, inventory by turnover rate, and payables by terms. The numbers tell different stories depending on how you slice them. Cash flow forecasting has its own blind spots. Most models assume patterns will continue based on historical averages. When a major customer changes payment terms or goes bankrupt, your forecast becomes fiction within weeks. I learned to build scenario analysis into every forecast, testing best case, expected, and worst case assumptions. The worst case usually involves losing your largest customer or having your biggest receivable turn bad. Plan for it before it happens.

Implementation steps for smaller organizations
Start with a weekly cash flow statement. Not monthly. Weekly. Track actual receipts and payments, not budgeted amounts. You will spot problems months earlier than with monthly reporting. A simple spreadsheet with columns for beginning balance, collections, disbursements, and ending balance for each week is enough to begin with. Implement variance analysis on your top twenty expense categories. Everything below that threshold can use simplified monitoring. The Pareto principle applies heavily to financial management. Twenty percent of your expense categories likely represent eighty percent of your spending. Focus your attention there. I found that reviewing just twelve categories covered about 85 percent of total expenditures in most small business environments I worked with. a minimum viable financial management system before adding complexity. Get the basics working correctly first: cash tracking, receivables management, and expense monitoring. Only then add forecasting models, budget variance analysis, and capital allocation frameworks. Most organizations skip ahead and end up with elaborate systems built on unreliable data. Garbage in, garbage out applies universally.
Training matters more than tools. A simple system used well beats a sophisticated system used poorly. I spent more time teaching teams to understand what the numbers meant than I did implementing software features. Financial literacy across the organization reduces errors, improves decision-making, and catches problems earlier than any automated system can.
The role of automation
Modern accounting software can automate routine financial management tasks, but automation without proper controls creates new risks. I saw a company automate their accounts payable process and immediately start overpaying vendors because the reconciliation step was removed. Automation should augment human oversight, not replace it entirely. Keep at least one person reviewing automated transactions monthly. Real-time dashboards sound appealing but can create analysis paralysis. Decision-makers get overwhelmed by data volume and miss important signals buried in the noise. I recommend starting with three to five key metrics per department rather than comprehensive reporting. Revenue growth, gross margin, cash conversion cycle, operating expense ratio, and days sales outstanding cover the essentials without flooding stakeholders with information they won't use.

Limitations and when to seek external help
Basic financial management principles work well for stable, predictable businesses. They break down in turnaround situations, during rapid expansion, or when entering new markets with uncertain demand patterns. In these cases, the historical data that financial models rely on becomes irrelevant or misleading. External consultants with turnaround experience can provide perspective that internal teams lack simply because they are too close to the problems. Small business owners often try to handle all financial management internally to save costs. This works until the business reaches a complexity threshold where professional help becomes necessary. The breakpoint varies but typically occurs around five to ten million in annual revenue, or when you have multiple product lines, several locations, or international operations. At that point, the time spent managing finances detracts from revenue-generating activities. Certain situations absolutely require external expertise. Tax planning for complex structures, fundraising preparation, merger and acquisition due diligence, and regulatory compliance all benefit from professional involvement. Trying to DIY these processes usually costs more in mistakes and missed opportunities than the professional fees would have been. The cost of good advice is always less than the cost of bad decisions made without it.
Ongoing refinement
Financial management is not a set-and-forget system. Markets change, businesses evolve, and assumptions that held last year may be completely wrong today. Review your financial management processes quarterly at minimum. Test whether your cash reserves are adequate, whether your costing models reflect current conditions, and whether your forecasting accuracy is improving or deteriorating. I keep a running log of forecast versus actual results for each major line item. After twelve months of data, I can see which areas I systematically overestimate or underestimate. This pattern recognition improves future forecasting accuracy significantly. Most people never do this because they assume next period will be similar to this period. It rarely is. The best financial management systems are simple enough to maintain reliably but comprehensive enough to catch real problems. Striking this balance requires ongoing judgment and adjustment. There is no perfect solution that works for every organization at every stage. The goal is building a system that serves your current needs while remaining flexible enough to adapt when those needs change.