What Actually Matters When You're Trying To Get Business And Finance Right
Most people treat Principles Of Business And Finance like a checklist. They learn the definitions, pass the quiz, and then get confused when their actual company cash flow looks nothing like the textbook example. I have seen this happen repeatedly over the years, usually to people who are smart but have never dealt with a real accounts receivable problem at 11 PM on a Friday. The foundation is straightforward enough. You need to understand how money moves through an organization, why timing matters more than the raw numbers, and how the various financial statements connect to each other. But connecting those dots in practice is where things get messy.
Principles Of Business And Finance That Actually Shape Decisions
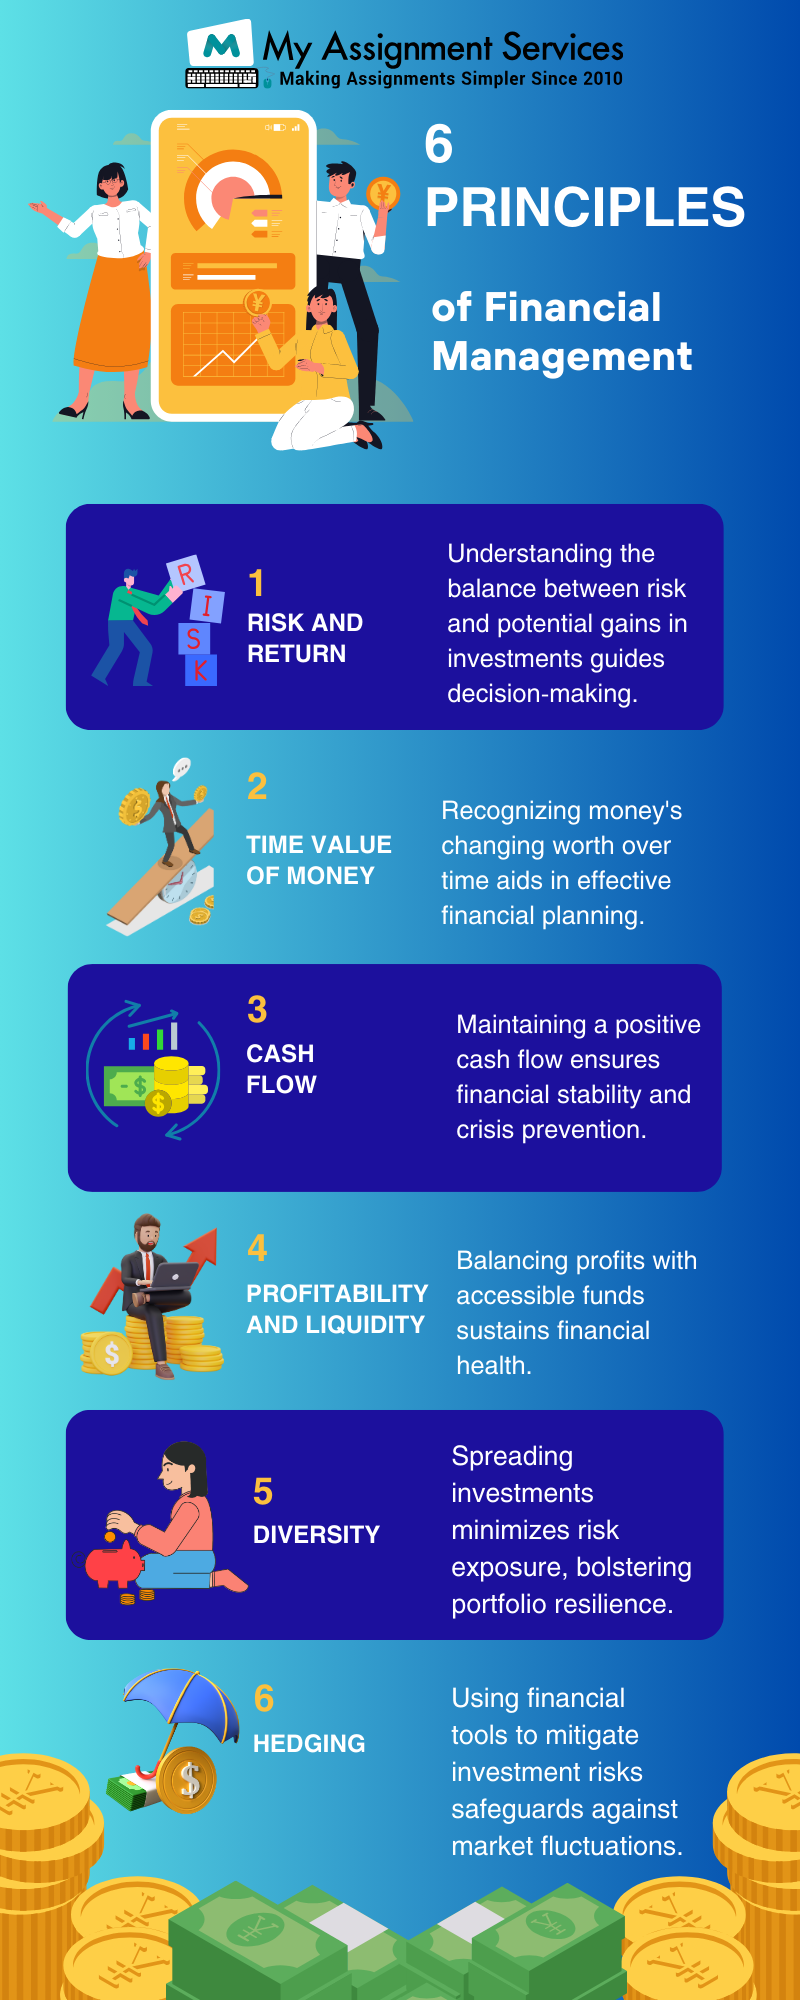
Let me start with the stuff most introductory courses gloss over. The principle of time value of money is not just a formula you plug into Excel. It is the single most important concept in finance, and people consistently underestimate it because the math looks deceptively simple. A dollar today is worth more than a dollar tomorrow, yes, but the real insight is understanding how much more depending on your cost of capital, your risk profile, and the opportunity cost of tying up funds in a particular investment. I once worked with a small manufacturing client who was offered a contract worth $200,000 payable in 18 months. The spreadsheet said it was profitable. The actual economics told a different story when you factored in the weighted average cost of capital, the working capital drain from upfront material purchases, and the inflation adjustment on their input costs. We turned it down. The revenue looked good on paper. The net present value was negative once you stopped treating money as interchangeable across time periods. That is one of the counter-intuitive things about this field. Good looking revenue can absolutely destroy value. Profit and cash flow are not the same thing, and nobody warns you about that until you are staring at an overdraft because your customers pay on 60-day terms and your suppliers want net 30.
Risk and return relationship is another principle that gets taught in a vacuum. The basic idea is that higher returns require accepting higher risk. What people miss is that not all risk is diversifiable, and you should only expect compensation for the risk that cannot be eliminated through portfolio construction. Unsystematic risk specific to your business should be managed through operational discipline, not priced into your required returns. Systematic risk, the kind tied to market movements, is where the risk premium actually lives. Another thing that trips people up is the distinction between accounting profit and economic profit. Accounting profit follows GAAP or IFRS rules and gives you a number for tax and reporting purposes. Economic profit subtracts the cost of equity capital from your operating income. If your return on invested capital is 12 percent and your cost of capital is 11 percent, you are technically profitable by accounting standards but creating almost no real economic value. At 10 percent return with an 11 percent cost of capital, you are destroying value even if your income statement looks fine. This distinction matters enormously when you are evaluating whether to expand, acquire, or hold.
Get the Full Details
The Practical Framework Most People Skip
Here is how I approach analyzing a business situation, and it is not always in the order you might expect. I start with cash flow because everything else depends on it. If the business cannot meet its obligations when they come due, the balance sheet composition and income statement elegance become irrelevant. Step one is mapping the cash conversion cycle. Days inventory outstanding plus days sales outstanding minus days payable outstanding. This single metric tells you how many days of operating cash are trapped in the working capital loop. A negative cycle, which Walmart and Amazon have managed at various points, means suppliers are effectively financing your operations. A positive cycle of 90 days or more means you need substantial external funding just to keep the lights on. Step two is understanding the capital structure and what it implies about risk. Debt amplifies returns in good times and accelerates failure in bad times. The question is not whether to use debt but how much debt the business can service under stress conditions, not under baseline assumptions. I always run a downside scenario where revenue drops 20 percent and costs are sticky, then check whether interest coverage holds above the covenant thresholds most lenders require.
Step three is valuation, and this is where most beginners make costly errors. They apply a multiple from a comparable company without adjusting for growth rate differences, margin profiles, or risk characteristics. Enterprise value to EBITDA is useful but only when you understand what EBITDA excludes. It ignores capex requirements, working capital changes, and tax obligations. A capital intensive business and a software business might trade at similar EV/EBITDA multiples but have completely different free cash flow generation profiles. I encountered a specific problem with a logistics company that demonstrated why these principles need to be applied together rather than in isolation. They had strong revenue growth, decent EBITDA margins, and what looked like a manageable debt load on paper. But their cash conversion cycle was expanding because they were taking on larger contracts with longer payment terms to win business. The growth was consuming cash faster than it was generating it. Traditional leverage ratios looked fine because the debt hadn't increased, but the quality of earnings was deteriorating. The workaround was restructuring their contract terms to require milestone payments instead of completion-based payments, which shortened the cash conversion cycle by 35 days and eliminated the need for additional revolving credit. It was not a finance problem in isolation. It was a commercial strategy problem that manifested as a finance problem.
Common Pitfalls And Where The Models Break Down
The most dangerous assumption in business finance is that past performance reliably predicts future results. It does not. Margins compress during commodity price spikes. Customer concentration risk becomes real risk when your largest client renegotiates. Regulatory changes can restructure entire business models overnight. Any financial plan that does not include explicit sensitivity analysis for at least three plausible alternative scenarios is essentially a wish list dressed in spreadsheet clothing. Another pitfall is confusing correlation with causation in financial metrics. Revenue growth and profit growth moving together does not mean one causes the other. Both could be driven by a third factor like market expansion or a favorable regulatory shift. When that third factor reverses, the correlation breaks and you are left with a business that grew into overcapacity. Cost of capital estimates are another area where small errors produce large valuation differences. Using a generic industry average WACC instead of calculating a company-specific cost of equity through the CAPM framework, then adjusting for size premium and company-specific risk, will give you a number that is roughly in the right neighborhood but potentially off by 200 to 400 basis points. That difference can swing a valuation decision by millions on a mid-sized transaction.

The biggest limitation of standard financial analysis is that it is backward looking by nature. Financial statements report what happened. They do not capture brand momentum, talent retention, technological advantage, or competitive positioning. These intangible factors often determine whether a business sustains its financial performance or deteriorates, yet they barely appear in the numbers. A business with strong intangibles can trade at a premium to its book value for years. A business losing its intangible edge can look financially healthy right up until the moment it is not. If you want a practical starting point, the basic financial statements are available free through the SEC EDGAR database for public companies, and many jurisdictions offer small business financial toolkits through their commerce departments. The knowledge itself does not require paid subscriptions. What requires effort is applying it honestly to your own situation instead of using it as confirmation bias for decisions you have already made.