How to Actually Use an Amortization Schedule Without Losing Your Mind
A printable amortization chart is just a table that breaks down every payment on a loan into principal and interest over the life of the loan. You see the balance drop month by month. Most people download one off the internet and then realize halfway through year three that the numbers don't quite add up because someone used a slightly different rounding convention. I've spent more hours than I care to admit chasing down half-cent discrepancies in borrowed schedules. The standard approach is to grab a loan calculator, plug in your principal, rate, and term, then export or print the results. Some sites charge for this. Others give you a PDF that looks professional but contains errors in the later periods. The trick is knowing which ones to trust and which ones to verify yourself before you hand them to a client or use them for a real financial decision.
Getting a Reliable Printable Amortization Chart
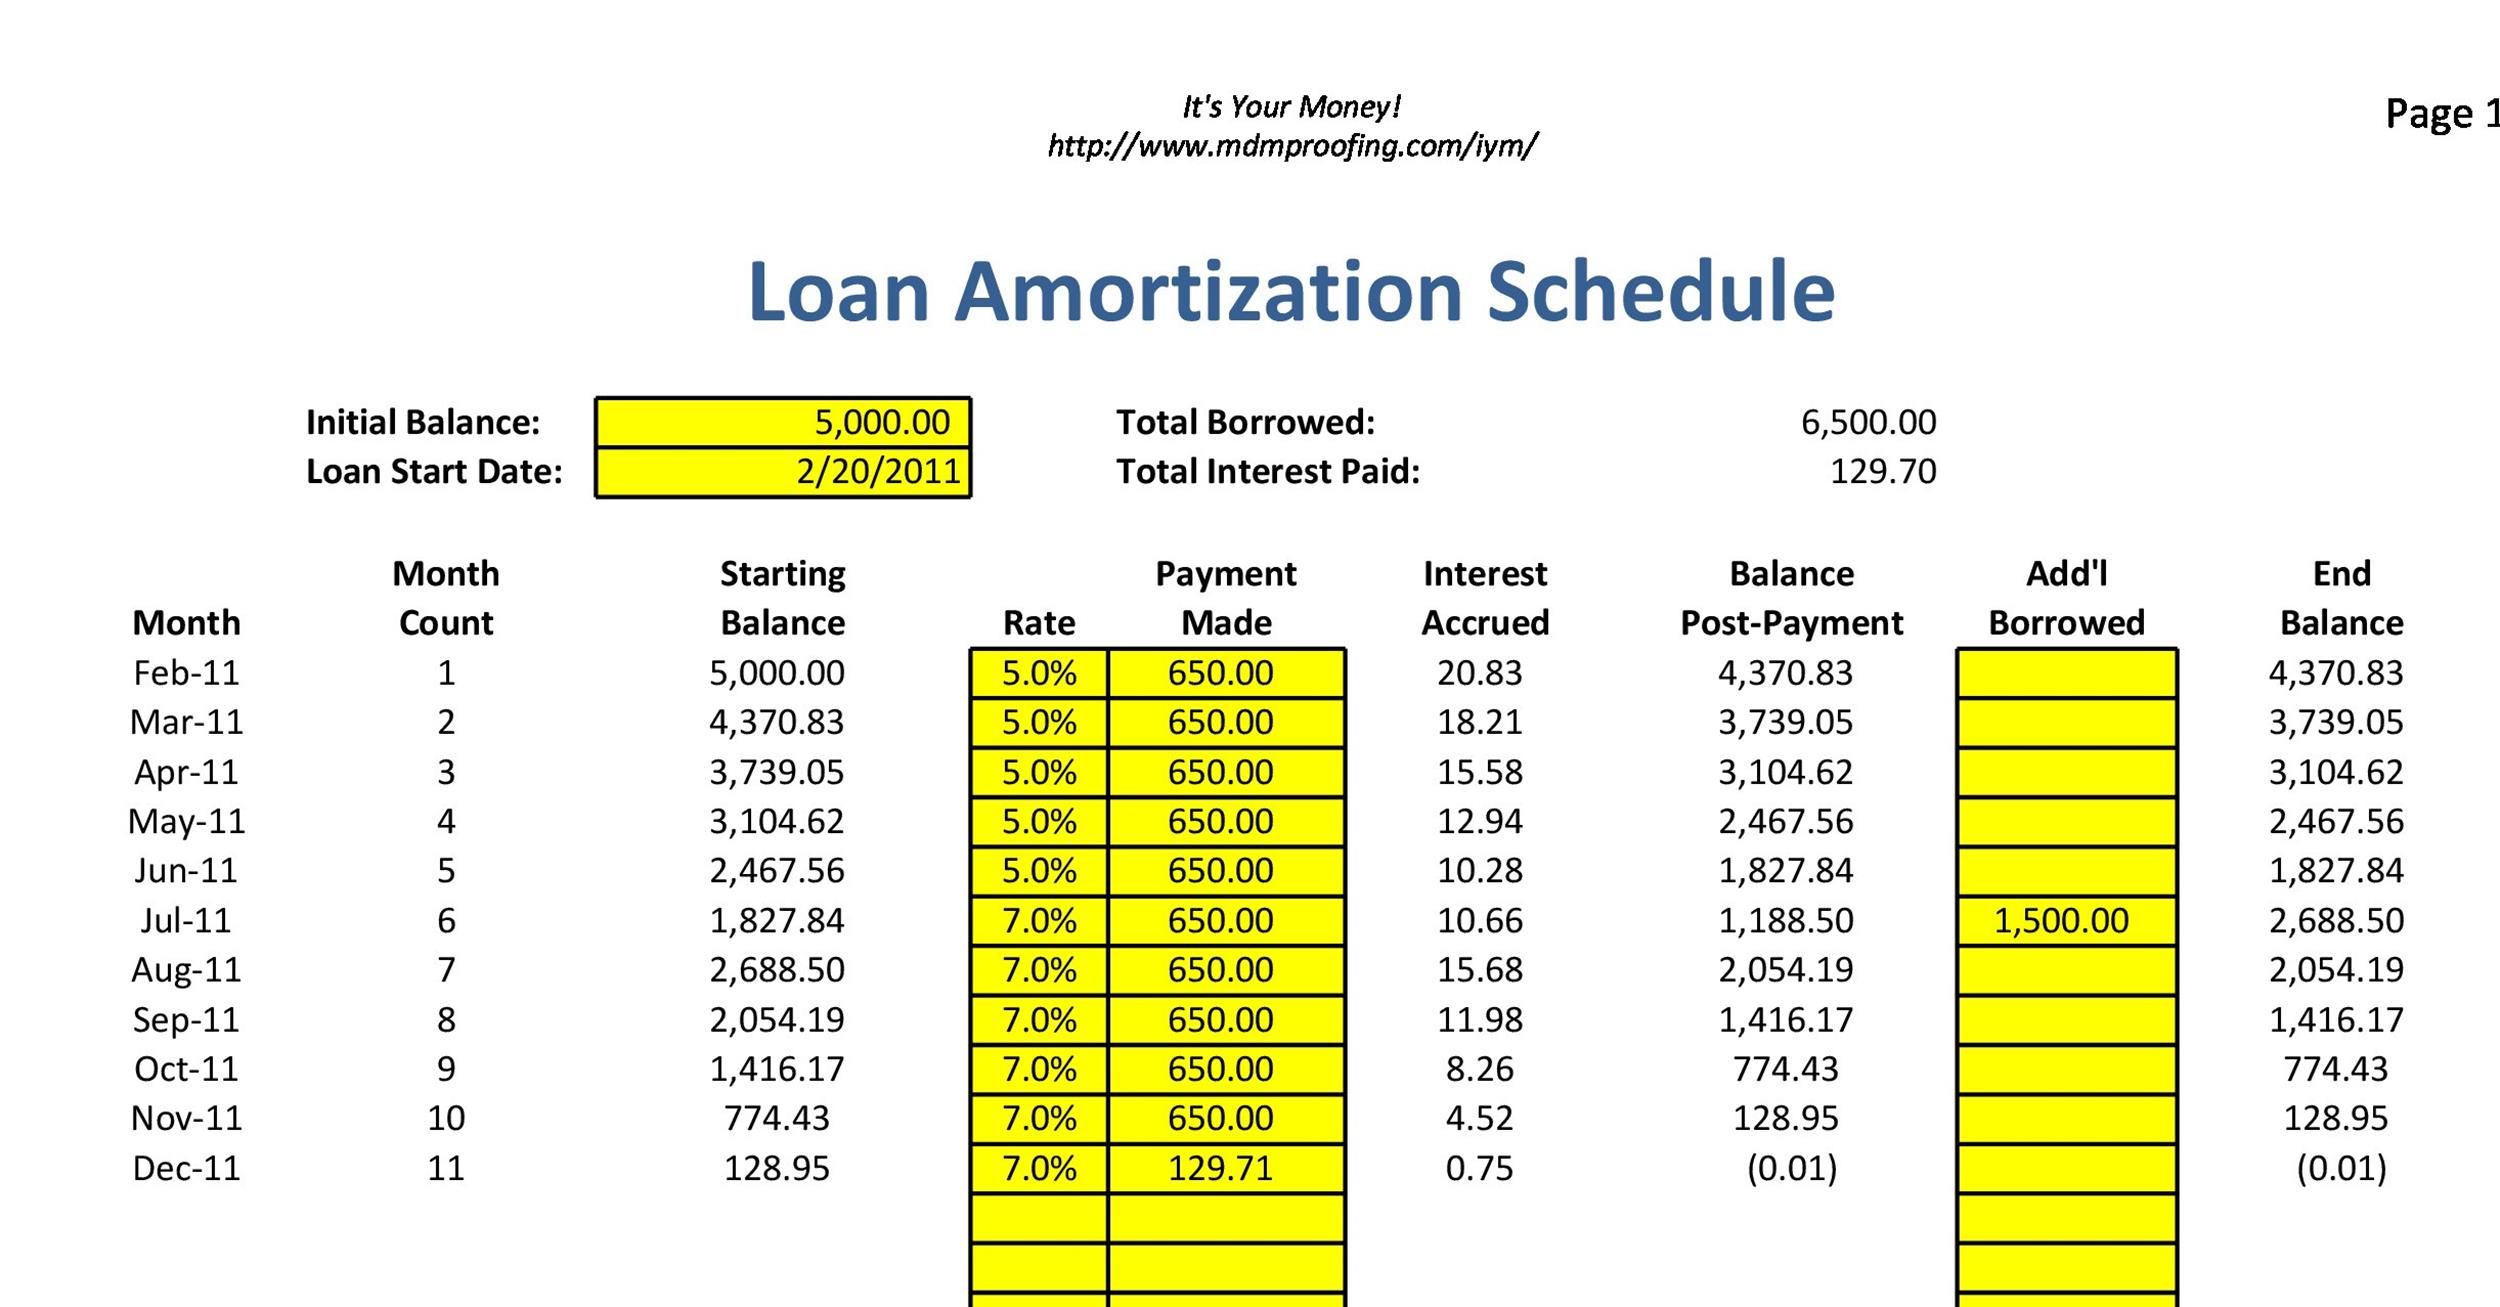
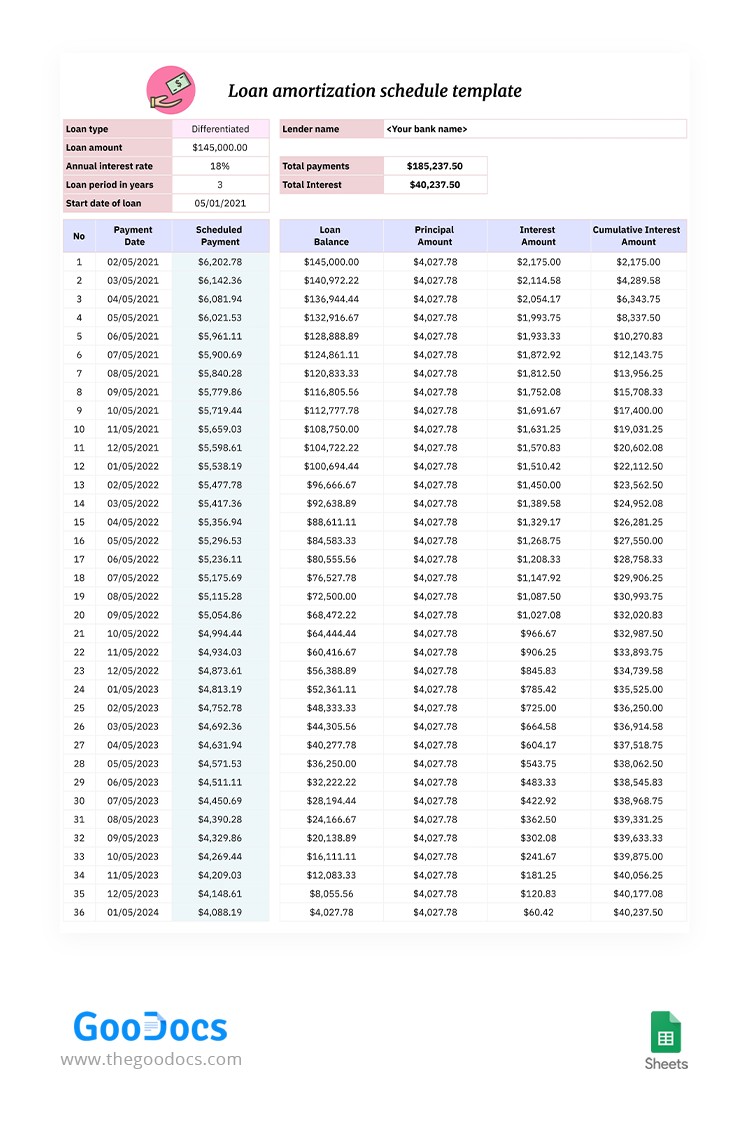
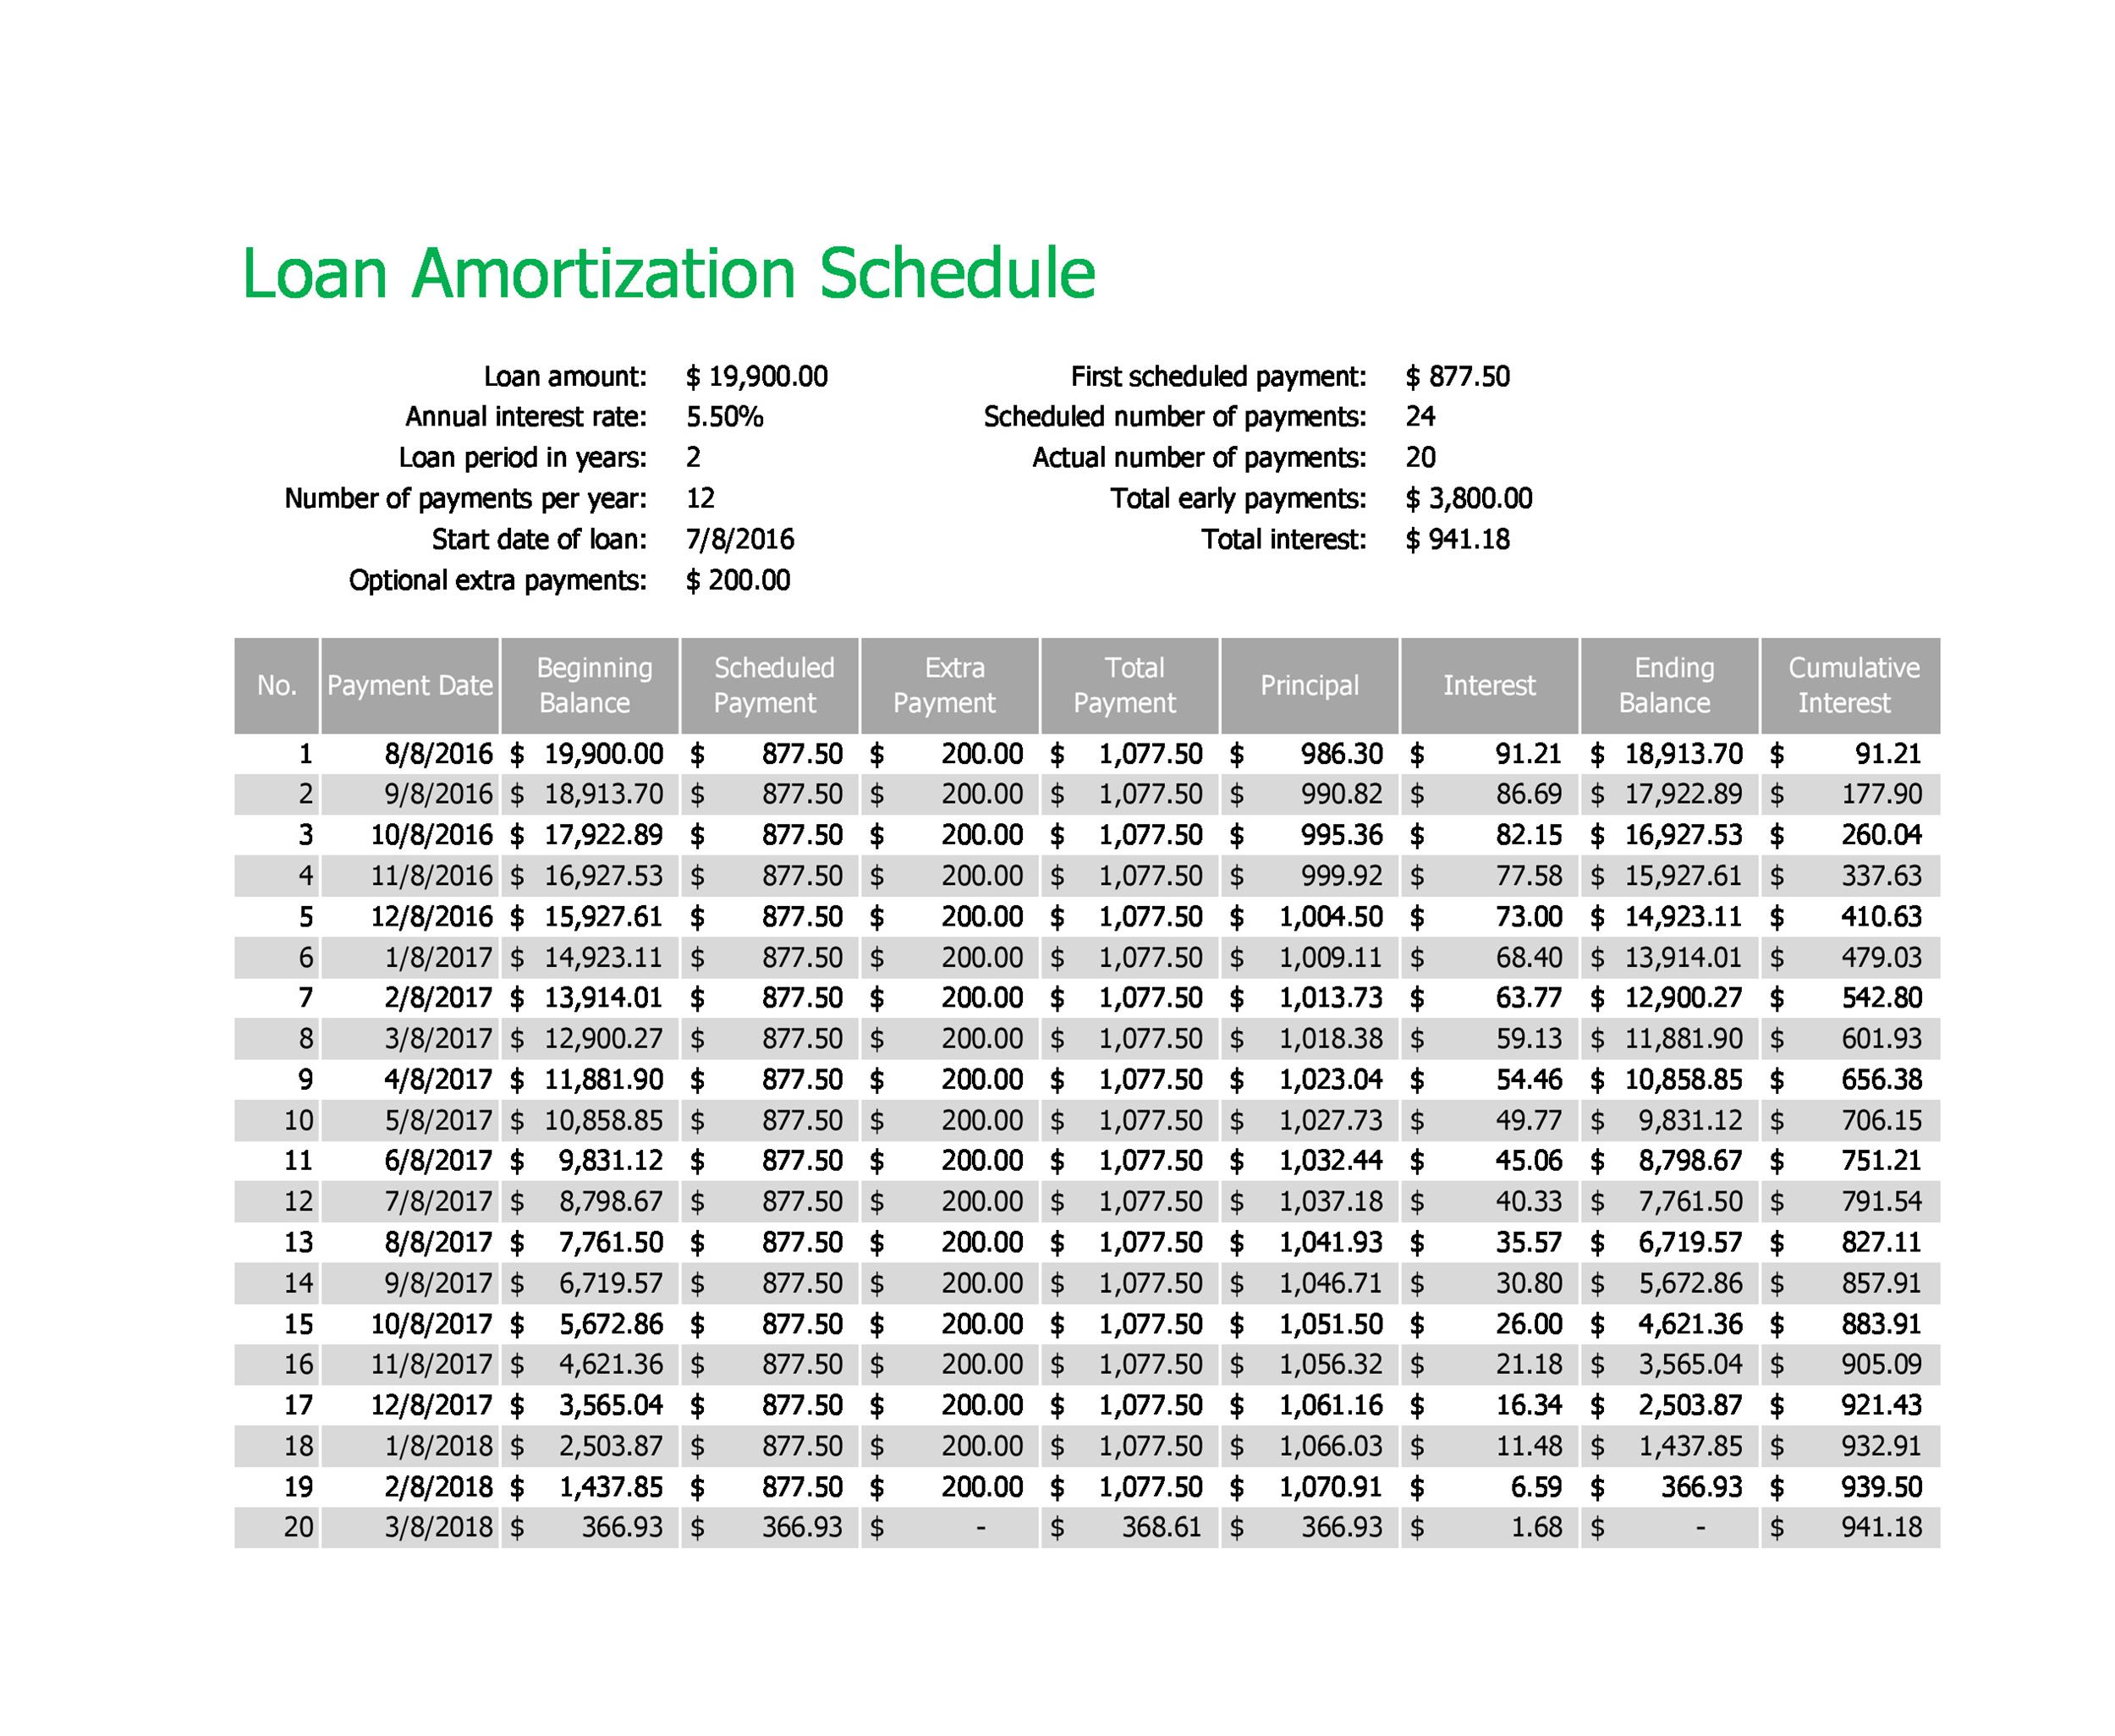
You can generate one yourself in a spreadsheet, which is what I recommend. Open a blank Google Sheet or Excel file and set up five columns: Payment Number, Beginning Balance, Payment Amount, Principal Portion, Interest Portion, and Ending Balance. In row one, put your loan terms as inputs at the top. The monthly rate is your annual rate divided by 12. The total number of payments is your term in years times 12. For the first payment, the interest portion equals the beginning balance multiplied by the monthly rate. The principal portion is the total payment minus the interest portion. The ending balance is the beginning balance minus the principal portion. Drag those formulas down for every payment. This usually takes about twenty minutes the first time and three minutes after that. A ready-made Printable Amortization Chart from a third-party site might save you the setup time but often lacks the flexibility to handle edge cases like irregular payment dates or additional principal payments. I ran into this exact problem last year when a borrower made a extra $5,000 payment in month fourteen and then switched to biweekly payments. The pre-generated schedule was useless after that point. I had to rebuild the table from scratch to account for the recalculation of the remaining term and adjusted payment amount. If you're dealing with anything beyond a straightforward fixed-rate loan with no deviations, building your own sheet is the only reliable path. Here is something most people miss about amortization schedules: the interest portion is front-loaded because it is calculated on the remaining balance, not the original loan amount. This means in the early years you are barely chipping away at the principal. A common misconception is that paying extra toward principal early in the loan destroys your equity temporarily. It does not. Extra principal payments immediately reduce the balance, which reduces the interest calculated in the next period, which means more of your regular payment goes toward principal going forward. The schedule adjusts itself automatically when you modify the beginning balance each period.
Another counter-intuitive detail involves how some lenders round. Federal regulations generally require rounding to the nearest cent at each payment period, but a handful of smaller lenders use truncated rounding or round at the end of each quarter instead of each month. This creates small discrepancies that compound over time. I once caught a discrepancy of forty-seven dollars between my spreadsheet and a lender-provided schedule on a fifteen-year loan. The lender rounded the monthly payment up by eleven cents and then absorbed the difference somewhere else in the calculations. The amortization table they printed did not match the actual payoff amount. Always reconcile the final payment against the stated payoff quote before relying on any schedule. The biggest limitation of a printable amortization chart is that it assumes a static loan. If your loan has an adjustable rate, points, escrow, or a balloon payment, the schedule becomes inaccurate after the first rate change or special payment event. An adjustable-rate mortgage schedule printed at closing is essentially a snapshot, not a living document. You will need to regenerate the chart every time the rate adjusts, which typically happens every six or twelve months. Skipping this step will give you a misleading picture of your actual obligation. If you want a simple, no-nonsense Printable Amortization Chart for a standard fixed-rate loan, you can build one using the method above or use a reputable free calculator like the one at NerdWallet or Bankrate. Export the results to PDF and verify the first twelve rows against manual calculations before printing. The verification step adds about five minutes but prevents you from acting on flawed data later. I have seen too many people sign refinancing documents based on schedules that were off by a significant margin because nobody checked.
Get the Full Details

The alternative to a printed chart is keeping the schedule in a live spreadsheet where you can update it whenever the loan changes. This is harder to share with a spouse or advisor but far more accurate over time. A printed chart is useful for quick reference or inclusion in loan documents, but it has a shelf life. Once the loan deviates from its original terms, the paper version is already wrong.