How to Build an Amortization Schedule That Actually Prints Cleanly
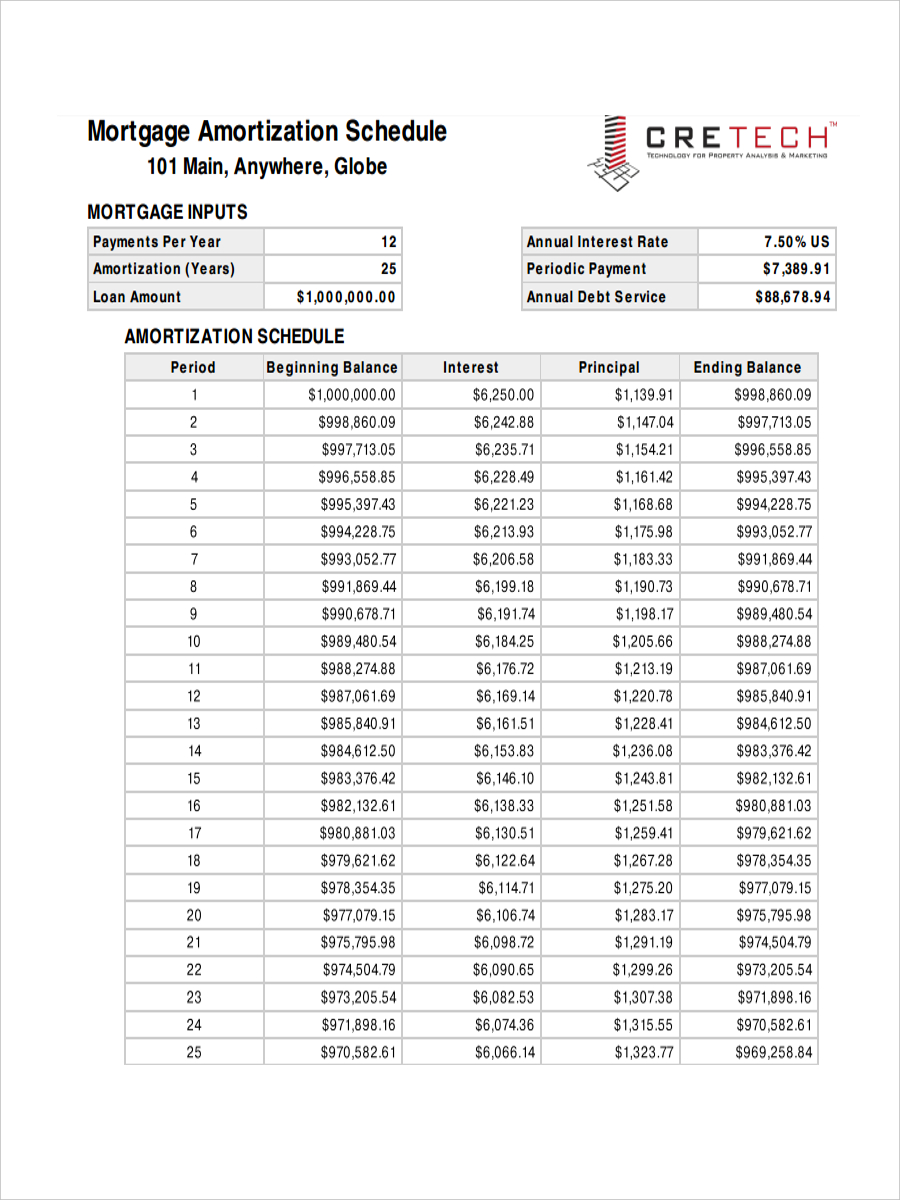
I spent about three years doing construction loans and commercial mortgages before I ever figured out how to make an amortization schedule that didn't look like garbage when printed. Most online calculators give you a table that's either too wide for letter paper or cuts off the middle columns because they designed it for screens, not printers. The gap between what people need and what tools actually deliver is bigger than it should be. A Printable Amortization Schedule is just a table showing every payment over the life of a loan, broken down into principal and interest. But making it print-ready means dealing with column widths, row counts, and those moments when the schedule runs 30 years and your printer thinks it's a novelty art piece.
Why Your Printable Amortization Schedule Looks Terrible
Here's the thing nobody tells you: most browsers will choke on a 360-row table if you don't set page breaks correctly. I had a client who tried printing a refinance schedule from a free online calculator and ended up with 12 pages where pages three through eleven were just empty margins and half a column header. He called me at 6 PM on a Friday because his closing was tomorrow and the title company needed the full schedule signed and stamped. The workaround was brutal but simple. I wrote a small Python script using the `reportlab` library that generated a proper PDF instead of relying on browser print-to-PDF. It set the page size to A4, forced column breaks every 24 rows, and included a running total of remaining principal at the bottom of each page so you could verify the math mid-document. Took me about 45 minutes to write, saves me hours on every loan package now.
The Spreadsheet Method (If You Don't Want to Code)
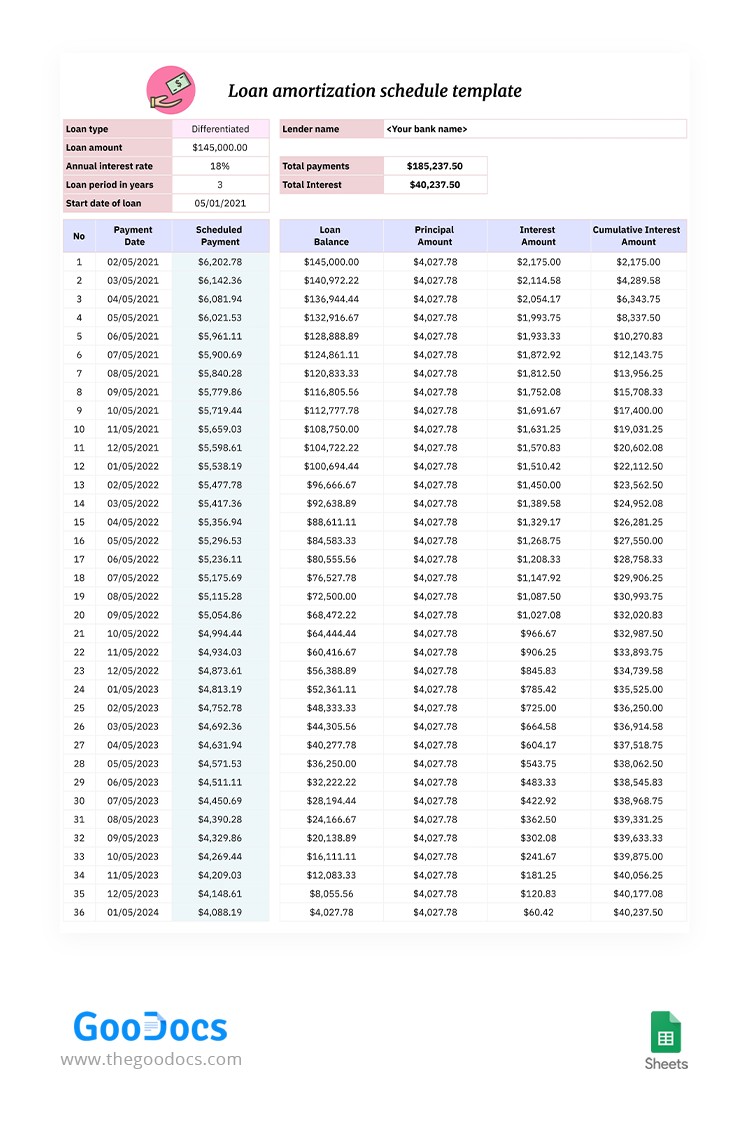
Not everyone needs a custom PDF generator. Sometimes you just need something you can tweak and print from Excel or Google Sheets. The trick is getting the column widths right before you hit print. Start with seven columns minimum: Payment Number, Date, Beginning Balance, Payment Amount, Principal, Interest, Ending Balance. If you're doing a balloon payment or adjustable rate, add columns for Rate Change Date and New Interest Rate. People always forget those until they're halfway through the document and realize they can't explain why the payment jumped from month 61 to 62. Set your print area to fit on letter paper with 0.5-inch margins. That gives you about 6.5 inches of usable width, which means your columns need to average roughly 0.9 inches each. Use a monospace font like Courier or Consolas for the numbers so everything lines up. Proportionally spaced fonts make alignment impossible when you have 360 rows.
Get the Full Details

Here's a counter-intuitive tip: add a column for cumulative principal paid. It sounds redundant but when you're handing this to a borrower or an underwriter, they want to see at a glance how much equity they've built by payment 120 or 240. Without that column, they have to subtract every ending balance from the original loan amount, which introduces errors and slows everything down.
The Calculator Approach (For Quick Estimates)
Sometimes you don't need the full 30-year breakdown. You need to know what the payments look like for a specific property deal and you need it five minutes ago. That's where online amortization calculators come in, but most of them are trash for printing. I recommend the one on Bankrate or NerdWallet for quick lookups, but neither gives you a proper printable format. What I actually do is plug the numbers into a free Google Sheets template, then use File > Print with the "Fit to page" option turned off. That prevents the sheet from shrinking your columns to unreadable sizes. The printed output won't be pretty, but it's legible and fast. If you need something more professional, there's a free tool called LoanCalc that exports to CSV. You can then open that CSV in Excel, format it properly, and print from there. The CSV export is the key step because it strips away all the web formatting that breaks when you try to print directly from the browser.
Edge Cases That Will Bite You
Not all loans are simple fixed-rate mortgages. Here's what happens when you try to print an amortization schedule for weird loan structures and what you do about it. Balloon payments: A 7/1 ARM with a balloon at year seven looks fine for the first 84 payments, then suddenly the last payment is massive. When printed, that row will spike and break your table alignment unless you format it separately. I solve this by coloring balloon payment rows in light yellow so they stand out. Borrowers notice immediately, and it prevents the awkward conversation where someone thinks the last payment is a typo. Interest-only periods: If the first five years are interest-only, your principal column will show zero for 60 rows. That's technically correct but confusing when printed. Add a note in the header row that says "Payments 1-60: Interest Only" so anyone reading the physical copy isn't wondering why the principal never changes. I've seen loan officers skip this and spend 20 minutes on the phone explaining it to clients who thought they were being scammed.
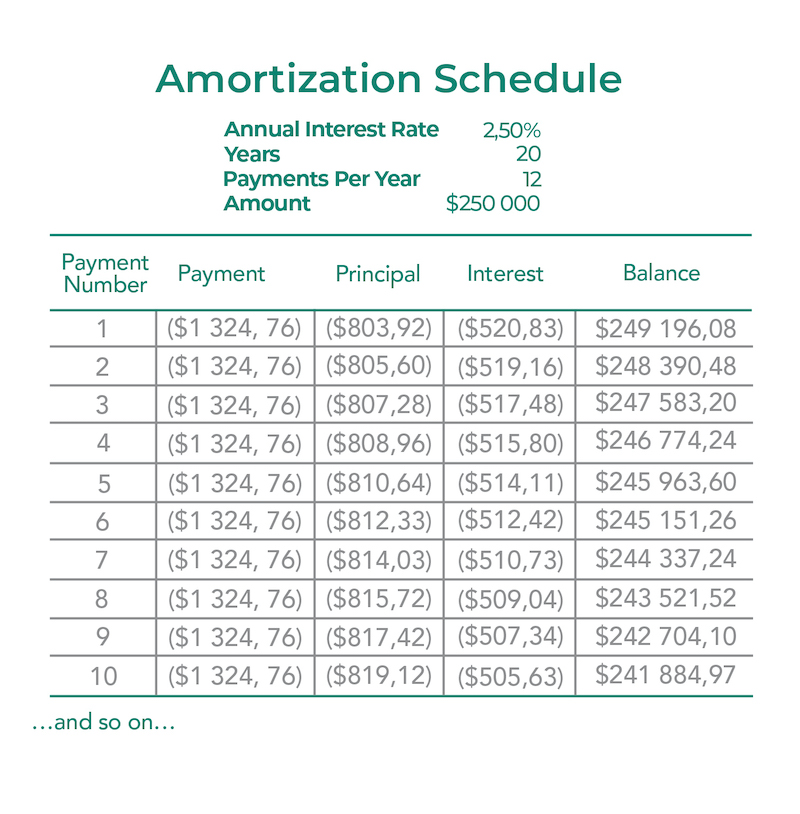
Graduated payment mortgages: These are rare now but they still exist in some portfolios. The payment amount changes every year for the first ten years, then stabilizes. Your schedule will have 120 different payment amounts if you break it down monthly. That's 120 rows with no repeating pattern, which makes verification a nightmare. I add a subtotal row every 12 months showing the annual payment change percentage. It takes two extra minutes to add but saves an hour of back-and-forth when someone questions the numbers.
When a Printable Amortization Schedule Won't Work
Let me be blunt about the limitations. Custom PDF generation with Python requires you to have Python installed and know how to run scripts. If you're a casual user who just needs one schedule for one loan, that's overkill. The spreadsheet method works for 90 percent of cases, but it hits a wall when you need to generate schedules in bulk for multiple loans simultaneously. Also, browser-based print functions will always struggle with tables longer than 200 rows. I've tested this repeatedly. Anything past payment 200 on a standard letter-sized page and the text becomes uncomfortably small or the columns get compressed until you can't read the numbers without squinting. If you're dealing with a 30-year loan and need the full schedule in one document, split it into two print jobs: payments 1-180 and payments 181-360. Page breaks between the halves keep everything readable. Another limitation: most free online calculators don't handle extra payments well. If your borrower makes additional principal payments mid-term, the schedule changes completely. You can't just adjust one row and reprint. You need to regenerate the entire table from the point of the extra payment forward. This is where the Python script pays off because you can pass in a list of irregular payments and it recalculates everything automatically.
File Format Options for Your Printable Amortization Schedule
You have three realistic options for getting this onto paper or a PDF. PDF: Best for formal presentations and legal documents. Use reportlab or a similar library if you're coding it, or export from Excel using the "Save as PDF" option. Avoid using the browser's print-to-PDF for anything longer than 100 rows. The quality degradation is noticeable and it makes professional impressions suffer. Excel/CSV: Best for editing and reuse. If you think you'll need to adjust numbers later or import the schedule into another system, keep it in spreadsheet format. CSV is universal but loses formatting. Excel keeps everything but requires the recipient to have compatible software.

Printed paper: Still relevant for certain transactions. Title companies, escrow officers, and some government agencies prefer physical copies with wet signatures. If you're submitting to those folks, print on actual paper, not PDF. Check their requirements first though because some accept both and some insist on one or the other. The bottom line is that there's no single perfect tool for every situation. I keep three methods ready: a Python script for bulk or complex loans, an Excel template for standard refinances, and a browser calculator for quick estimates. Which one I use depends on the loan structure, the timeline, and whether the borrower needs to sign anything physical. Most of the time it's the Excel template. It's fast, flexible, and prints cleanly if you set it up right the first time.