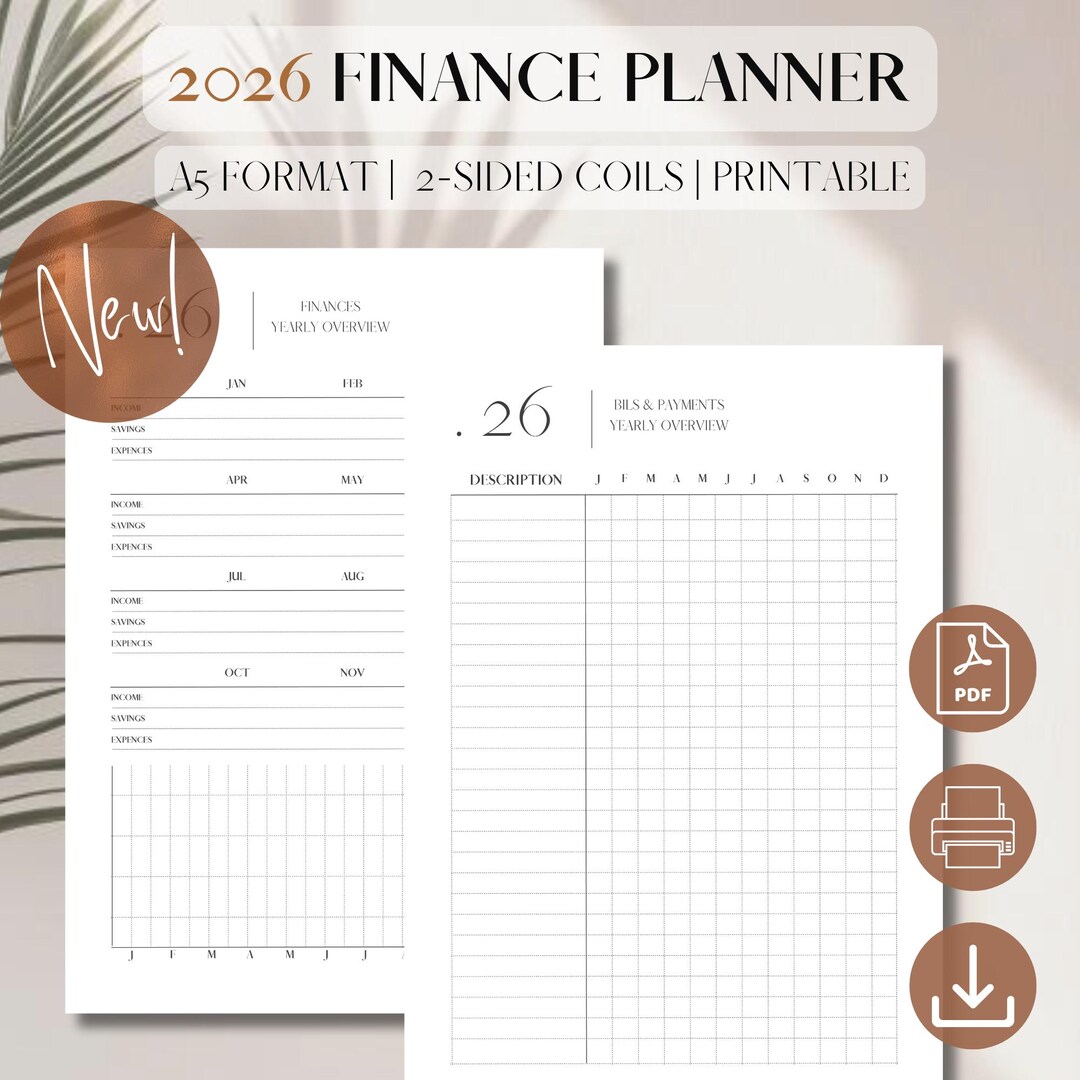
What Printable For Finance 2026 Actually Is
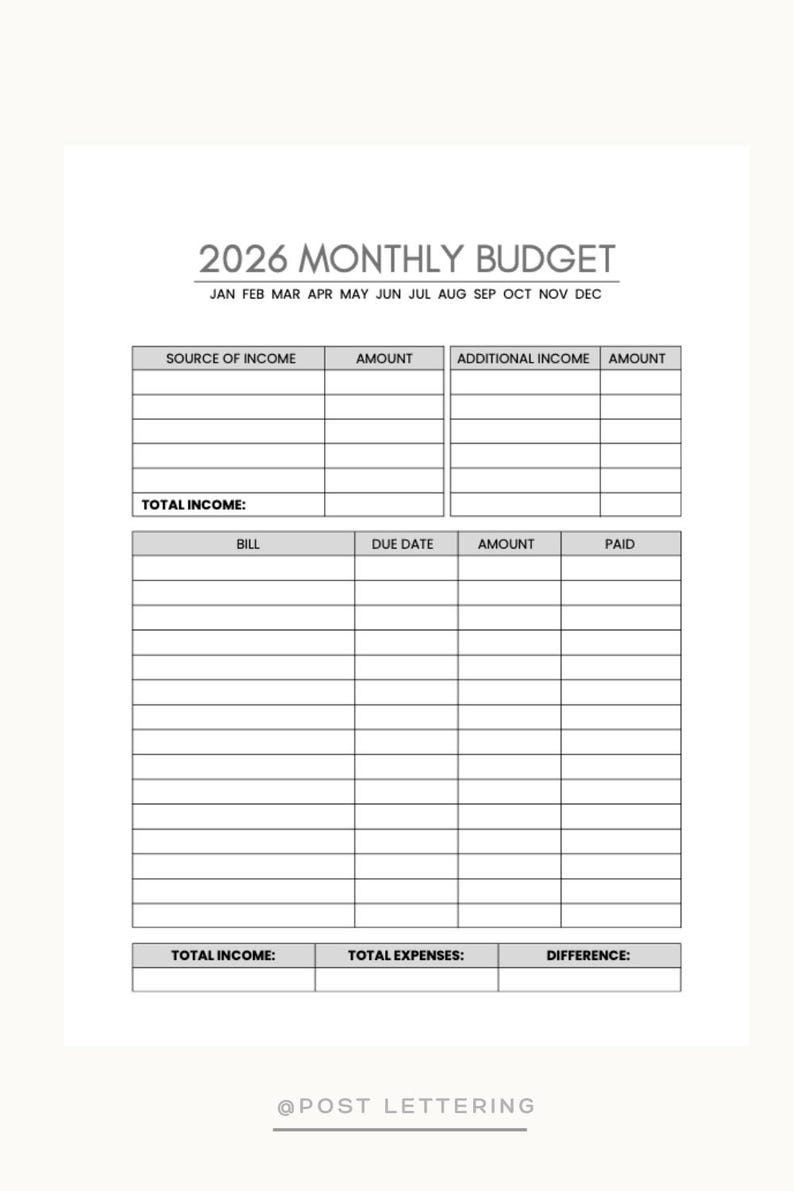
It's a set of downloadable financial planning sheets you print out or use digitally. Budget trackers, expense logs, debt payoff schedules, savings goal charts, tax prep checklists. That's the whole category. People use them to get organized when spreadsheets feel too rigid or when they want to work without a screen. I've been doing personal finance tracking since before apps had decent UIs, and honestly, nothing beats pen on paper for certain kinds of decisions. Your brain processes different information when you write instead of type. The market has shifted a bit from last year. In 2024 and early 2025, everything was geared toward generative AI integration and app syncing. For 2026, the more useful printables are the ones that acknowledge people are overwhelmed. The best sets I've found don't assume you'll track every coffee purchase. They give you a few key views: monthly cash flow, annual net worth check-ins, and a debt avalanche ladder. That's it. The ones trying to include everything become useless because nobody fills out twelve sections every month. I downloaded a popular set last fall that claimed to cover every financial scenario. Twelve tabs. Monthly, weekly, daily trackers, investment portfolios, insurance summaries, credit score logs. I filled out exactly one page before abandoning it. The problem wasn't the design quality. The problem was the cognitive load. A good printable has to earn its existence on each page by making a decision easier, not harder.
How to Actually Use These
Most people approach printables wrong. They treat them like something to complete perfectly. That's why they quit after three weeks. The right approach is to use them as conversation starters with your own finances, not as compliance documents. Start with the monthly cash flow sheet. Print four copies at the start of the quarter. Don't buy a fancy notebook. Don't laminate anything. Just regular printer paper in a folder. At the end of each month, look at where the money actually went compared to where you thought it would go. Circle the surprises. Next month, adjust. You're not recording data for a spreadsheet. You're building pattern recognition. This usually cuts down the mental bandwidth required to think about money from something exhausting to maybe ten minutes a week once you've done it a few times. The debt payoff section deserves a specific callout. Most printable debt snowball or avalanche templates just list your balances and minimum payments. That's fine but incomplete. The one insight nobody emphasizes is the psychological friction of seeing your name cross off a list. Even if the math says avalanche (highest interest first) is better, the snowball (smallest balance first) often produces better adherence. I had a client last year who was $8,000 in credit card debt at 22 percent APR and another $3,000 in a personal loan at 9 percent. Mathematically, she should crush the cards first. She tried that for two months and stalled out completely. When we switched to paying off the personal loan first, she hit it in six weeks and then tackled the cards with actual momentum. The printable doesn't change the math. It changes the behavior.
Where People Mess This Up
Here are the specific problems I see repeatedly. The first is printer cost and paper waste. I had someone email me last March complaining their $40 printable bundle ended up costing $120 in ink cartridges and specialty paper. They printed every page in color double-sided on cardstock. You don't need any of that. Standard black and white on 20-pound paper is fine. If a page has charts or color coding, print it once and keep it somewhere visible. Don't reprint monthly. The second problem is the assumption that a printable replaces a system. A piece of paper doesn't automatically pay your bills or negotiate lower interest rates. I know that sounds obvious but people buy printables the way some people buy gym memberships expecting automatic fitness. The printable is a coordination layer. You still have to do the actual financial work it helps you organize.
Get the Full Details
The third issue is more technical. Many printable PDFs use forms that don't fill in reliably when printed from certain browsers. I spent twenty minutes troubleshooting why a debt tracker's pre-printed boxes were rendering half an inch to the left on Chrome but perfect on Safari. The workaround is to download the PDF and open it in your operating system's native viewer first, verify the layout, then print from there. Also, some free printables include non-standard fonts that render poorly on older printers. If the text looks pixelated or misaligned, that's usually the culprit rather than a hardware issue.
Getting The Actual Files
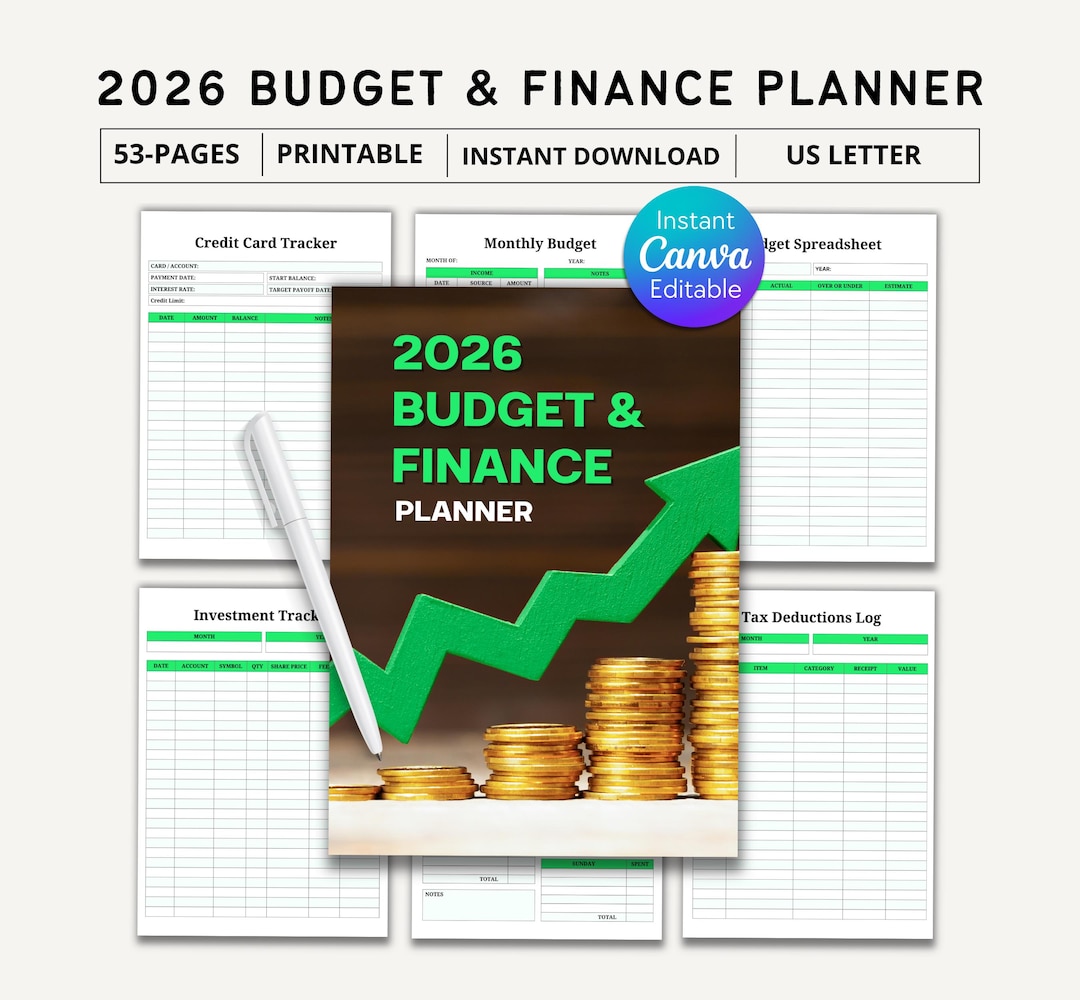
You can find Printable For Finance 2026 resources on a few reliable sites. The ones worth your time are typically from certified financial planners or established personal finance educators rather than generic template aggregators. Some of the better free options come from university extension programs and nonprofit financial counseling organizations. They tend to be less polished visually but more accurate mathematically, which matters more than you'd think. I've seen several commercial printables with errors in their debt payoff calculations where the compound interest formulas were miscalculated, leading people to underestimate how long their debts would take to eliminate. Paid bundles on platforms like Etsy or from well-known finance creators tend to have better design and more comprehensive coverage. The tradeoff is cost and sometimes over-engineering. A $15 bundle might include seventy pages but only twelve of them will see regular use. The rest become digital clutter.
When Printables Aren't The Right Move
I want to be blunt about the limitations because most product descriptions won't be. Printables don't work well if you live paycheck to paycheck with irregular income. The assumption built into almost every financial printable is relatively stable monthly cash flow. If your income fluctuates by forty percent or more between months, a static PDF can't adjust fast enough and you'll end up either ignoring it or constantly rewriting it by hand, which defeats the purpose. They also don't scale for complex situations. Multiple income streams, self-employment taxes, rental properties, investment accounts across different brokerages, college savings plans, insurance policies to track. Once your financial life hits that level of complexity, a printable becomes a fragment rather than a system. You'd be better served by a simple spreadsheet or a basic budgeting app, not because those tools are inherently superior but because they can link and calculate relationships between variables that a static page cannot. The biggest failure mode is perfectionism. I've watched people spend more time designing the perfect printable system than actually managing their money. Two weeks of setting up headers in a document editor, hunting for the right font pairing, color-coding every category, customizing templates to include income sources you don't even have anymore. That's not financial planning. That's procrastination with better aesthetics.