What You Need to Know About IRS Form 262
Form 262 is the IRS document used when a payer needs to collect withholding tax on certain foreign pension and annuity distributions. It gets filed with the IRS to report that withholding has occurred or to request exemption from it. The form itself isn't complicated, but people tend to mess it up in predictable ways. I spent about three years handling these for a mid-size pension administration firm, and the most common issue I saw was payers not understanding the difference between withholding and treaty-based exemptions. That confusion alone accounts for maybe half the rejected filings we dealt with.
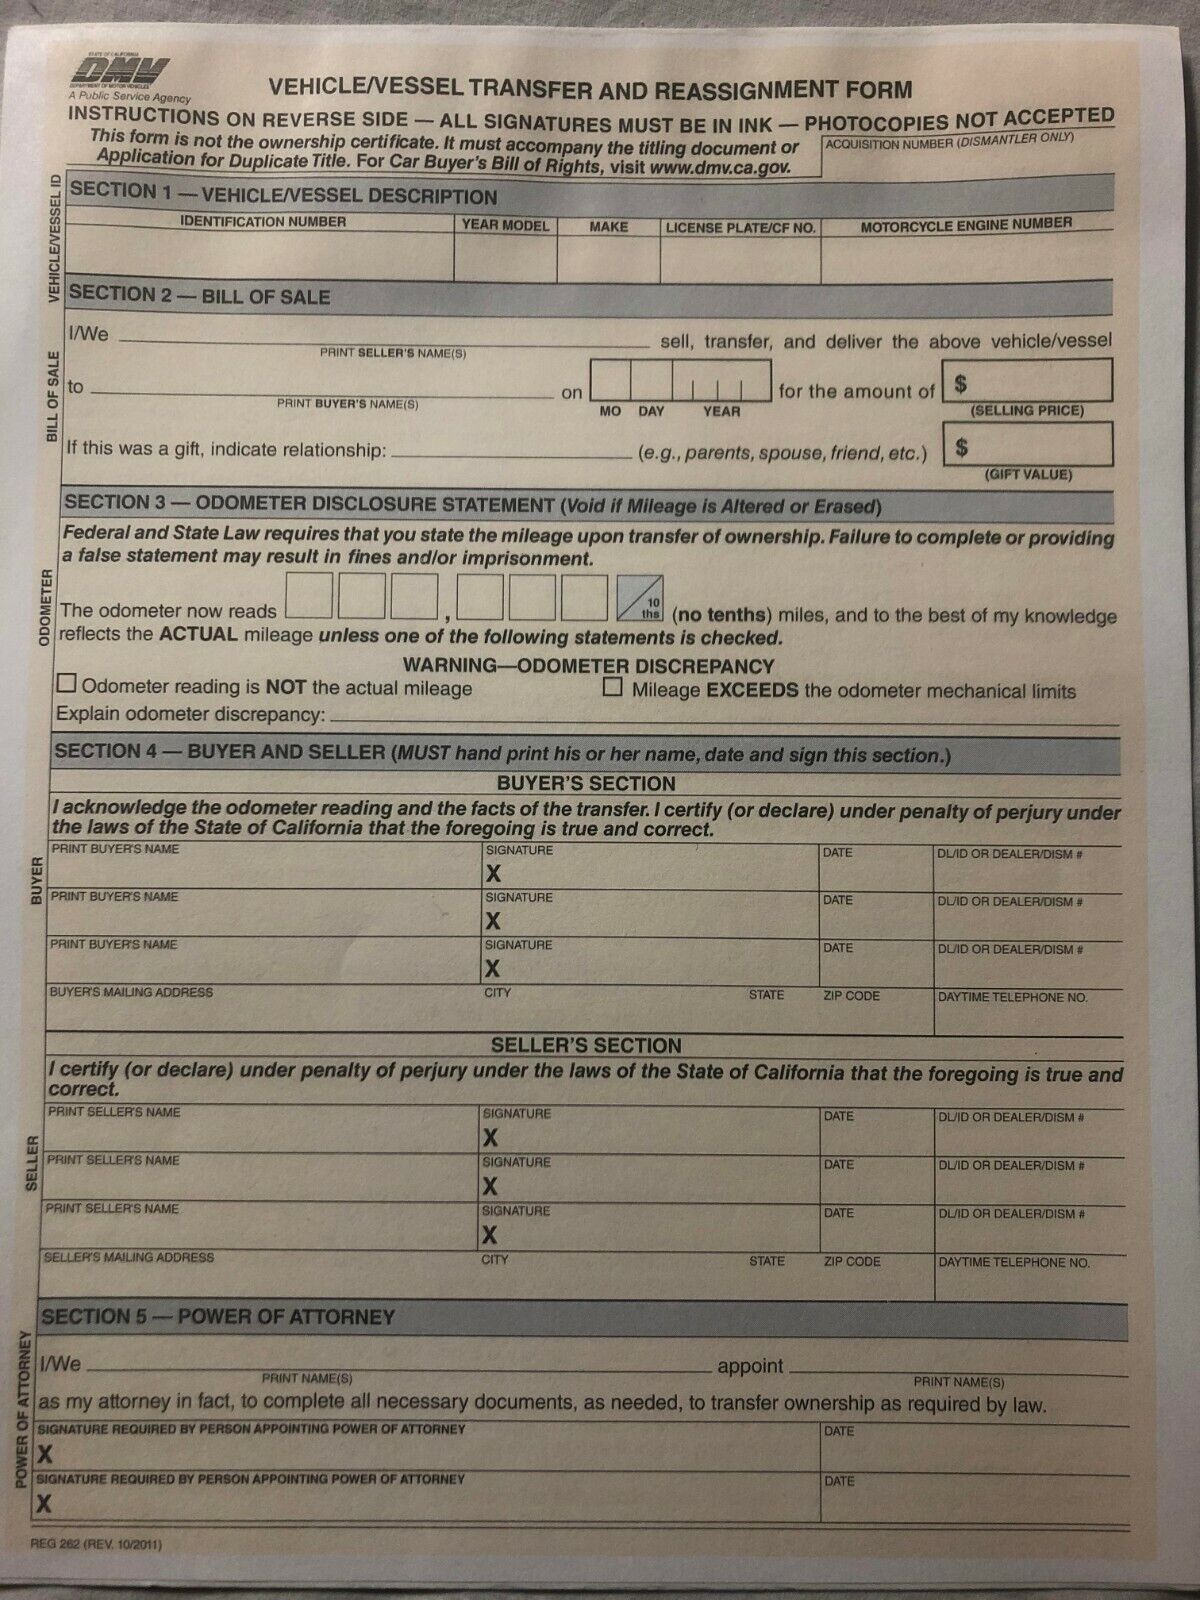
Where to Find the Printable Reg 262 Form Pdf
The IRS publishes the current version directly on their website at irs.gov. You want the instructions too, not just the form blank. The instructions section on eligibility and the filing thresholds is where the actual substance lives. Download the PDF version so you can fill it out digitally if your system supports that. The paper version tends to get misread by OCR systems during processing. Here's the practical link: go to irs.gov/forms-pdfs and search for Form 262. The Printable Reg 262 Form Pdf will be the most recent revision. Make sure the revision date is current. I've seen people use two-year-old versions and waste hours on corrections because the withholding tables changed.
How the Form Actually Works
Part I of the form captures the payer information and the recipient's taxpayer identification number. Part II is where the withholding calculation happens. You need to determine the correct withholding rate based on whether the recipient is a U.S. person or a foreign person, and whether any treaty exemption applies. The tricky part most people miss: if the recipient claims a treaty exemption, you need to have a valid Form W-8BEN or equivalent on file before you can reduce or eliminate withholding. Without that documentation, the default rate kicks in, and getting it reversed later is a separate process that involves amended filings and waiting periods. I had a client who lost about $12,000 in over-withheld funds because their paperwork wasn't processed in time, and recovering it took fourteen months.
Get the Full Details
Common Mistakes and What to Avoid
One thing nobody warns you about is the effective date field. If you get that wrong, the entire withholding period shifts, and you end up reporting tax for the wrong calendar year. Always triple-check the payment date against the form date. Mismatches here are the #1 reason the IRS sends those annoying correction notices. Another issue: people often forget that Form 262 needs to be filed separately for each recipient. It's not a aggregate form. If you're paying out to ten different foreign pension recipients in the same quarter, that's ten separate filings. I know that sounds obvious, but I've seen firms try to bundle them and get flagged for it. The withholding rate itself is another area where things go sideways. The standard rate for most foreign pension distributions is 30%, but that's not always the final number. Some jurisdictions have reduced treaty rates. You need to verify the specific rate for the recipient's country of residence before you calculate anything. The IRS treaty lookup tables are available online, but they're not always updated immediately when new treaties come into effect.
When This Method Doesn't Work
Form 262 only covers certain types of foreign pension and annuity income. It does not apply to Social Security benefits, U.S.-source retirement distributions, or most other types of pension income. If your situation involves a mix of U.S. and foreign sources, you may need to file different forms for each portion. Trying to force everything onto one 262 is a quick way to create compliance problems. Also, if you're dealing with large or complex pension arrangements, especially ones involving multiple trusts or shell entities, the form alone won't capture everything. You might need supplementary documentation or professional tax guidance. The form is a reporting tool, not a comprehensive solution for complicated cross-border pension structures.
Quick Reference for Filing
- File quarterly if you have withholdable payments during that period
- Keep copies of all W-8 forms and treaty exemption documentation for at least four years
- Use the IRS e-filing system when possible to avoid processing delays
- Double-check the recipient's ITIN or SSN before submitting
The whole process usually takes about twenty minutes per recipient if your records are organized. If you're scrambling to find documentation mid-filing, it can easily stretch to an hour or more. Keeping a clean folder structure for each recipient pays off immediately.