Solving Differential Equations When the Textbook Stops Working
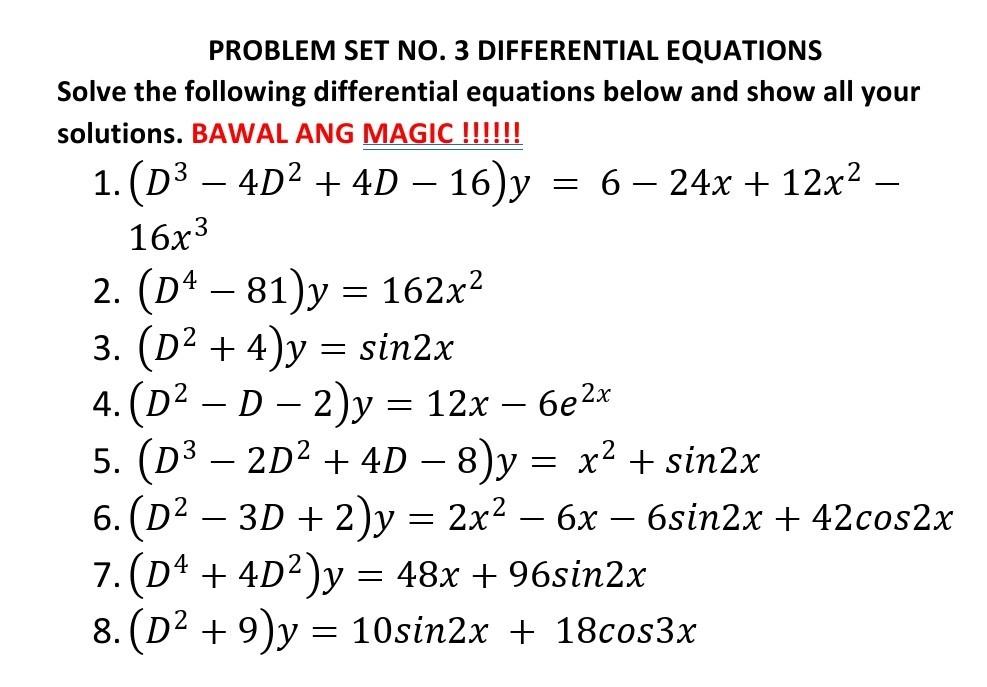
I spent six months trying to get a boundary value problem right on a thermal simulation project and kept hitting a wall where analytical methods fell apart and numerical approaches introduced unacceptable error. The issue wasn't that I didn't know the theory. It was that no one really talks about what happens between the ideal textbook example and the messy reality where your Problem Differential Equation refuses to behave. Let me just walk through what actually matters when you are dealing with these, because most guides skip the part where everything goes sideways.
Getting to Grips with the Problem Differential Equation
A differential equation relates a function to its derivatives. That is the standard definition you will find anywhere. The part nobody emphasizes is that most real world problems don't produce clean, linear, second order equations with constant coefficients. You will routinely encounter nonlinear terms, variable coefficients, mixed boundary conditions, and sometimes equations that are stiff enough to make even robust numerical solvers take an unreasonable amount of time. The first thing I learned the hard way is that your choice of solution method depends entirely on the structure of the equation, not on what you happen to be comfortable with. If you try to force an analytical technique onto a problem that only yields numerically, you will waste days. If you jump straight to a numerical solver without checking for stiffness or boundary layer behavior, you will get an answer that looks reasonable until you refine the grid and watch it fall apart.
Methods That Actually Work in Practice
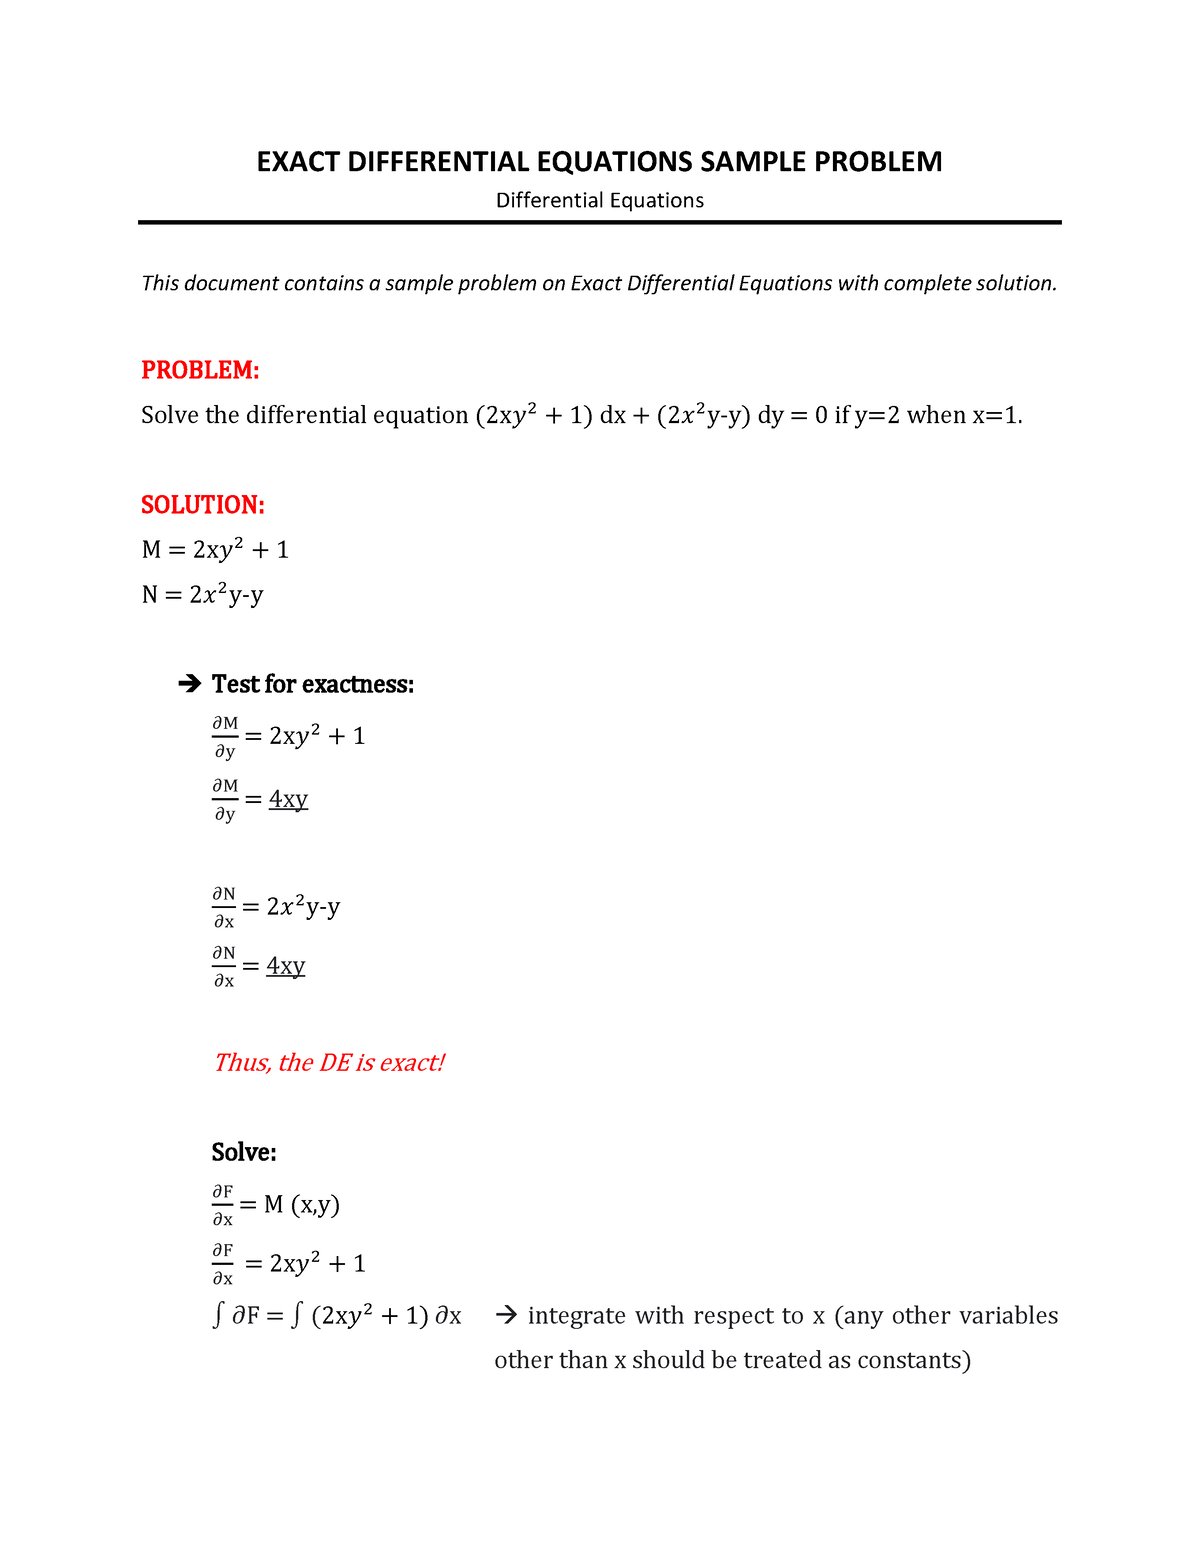
Here is how I approach these now, after enough failures to stop guessing. Separation of variables still has its place, but only when your equation and boundary conditions are compatible with it. I check that first. If the spatial and temporal parts can cleanly separate under the given constraints, great. If not, I move on immediately instead of trying to manipulate the equation into a shape it does not want to take. The integrating factor method works well for first order linear equations. I use it when I have a single dependent variable and its first derivative showing up linearly. It is fast, reliable, and usually takes under five minutes by hand for properly structured problems.
Get the Full Details

Laplace transforms are useful when you have initial value problems with discontinuous forcing functions or impulse inputs. I reached for this method on a circuit analysis problem once where the voltage source switched between three different profiles over time. Doing that piecewise with classical methods would have been painful. The transform collapsed it into algebraic manipulation and the inverse transform gave me the solution cleanly. For the cases where none of the above apply, numerical methods are your path. Runge Kutta fourth order is the default for good reason. But I also keep finite difference and finite element approaches in my toolkit depending on whether I am dealing with an ordinary or partial differential equation and what the domain geometry looks like.
What Beginners Miss
One counter intuitive thing that trips people up is the relationship between order and solution complexity. A second order equation does not automatically produce a more useful or more difficult solution than a first order nonlinear one. Nonlinearity is usually where the real trouble starts, not higher order. I have seen people confidently apply linear superposition to equations that clearly contained squared terms or products of the dependent variable and its derivative. Superposition does not apply there. At all. Another thing that is rarely stressed: the difference between existence and uniqueness and your ability to actually compute the solution. Picard-Lindelof theorem tells you when a unique solution exists locally. It does not help you find it. I have problems where existence was guaranteed on paper but the solution involved special functions or required asymptotic approximations because closed form expressions simply did not exist in any practical sense.
The Edge Case That Cost Me a Week
I was working on a heat transfer model for a composite material with temperature dependent thermal conductivity. The equation ended up being nonlinear and stiff because the conductivity changed rapidly over a narrow temperature range. My initial approach used a standard explicit finite difference scheme. It was stable for large time steps at lower temperatures but oscillated wildly once the gradient increased. The solution diverged around the transition zone and I couldn't figure out why until I plotted the local mesh Fourier number and saw it exceeded the stability limit in exactly that region. The workaround was switching to an implicit Crank Nicolson scheme for that section, which is unconditionally stable, combined with adaptive time stepping that reduced the step size automatically when the solution gradient spiked. I also added a linearization step using Newton iterations inside each time step to handle the nonlinear conductivity term. This cut my total computation time from roughly four hours of failed attempts down to about twenty minutes of actual run time once the setup was correct. If you are facing something similar, the key insight is to check stability criteria before you trust any numerical result, not after.
When These Approaches Fail Completely
I should be blunt about the limitations. Analytical methods fail whenever the equation lacks the symmetries or linearity they require. Numerical methods can produce garbage if your discretization is too coarse, your boundary conditions are ill posed, or your solver isn't configured for the stiffness profile of the problem. There is no universal fallback. For strongly nonlinear partial differential equations in complex geometries, even advanced numerical techniques can struggle. I have encountered reaction diffusion systems where the solution developed sharp fronts that required specialized adaptive mesh refinement just to resolve properly. Standard solvers smoothed those out entirely and gave answers that were wrong in the regions that mattered most. In those situations, I recommend checking whether a perturbation method or a similarity transformation might simplify the equation first. Sometimes a coordinate change or an asymptotic approximation reduces a nearly unsolvable problem to something manageable. If neither works, you may need to accept a lower accuracy requirement or reformulate the problem physically rather than mathematically.
Practical Workflow I Use Now
Classify the equation first. Ordinary or partial. Linear or nonlinear. Order. Homogeneous or not. Boundary or initial conditions. Write all of that down before touching a solution method. Then check whether an analytical approach is feasible based on that classification. Give yourself maybe twenty minutes. If it doesn't click, move to numerical. Verify your numerical results with a grid independence study at minimum. Compare against an analytical solution if one exists for a simplified version of your problem. If nothing matches, your model or your implementation is wrong somewhere and you need to find it before trusting any output. Most of the errors I have seen in practice come from skipping the verification step. People get an answer from their solver and stop. That is where mistakes hide.