Why Your Number at Closing Is Never What You Think It'll Be
I spent a good chunk of my twenties watching people get blindsided at the closing table because they had no idea what their actual proceeds would look like. They know the sale price. They know roughly what they owe on the mortgage. Beyond that, it's guesswork. That's where a Proceeds Calculator comes in, and honestly, it's one of those tools that sounds obvious until someone actually asks you to account for transfer taxes in a county with staggered rates. A proceeds calculator is a straightforward tool that takes your expected sale price and subtracts every cost associated with the transaction — mortgage payoff, real estate commissions, title fees, prorated taxes, HOA liens, inspection credits, anything that carves into what lands in your pocket. The output is your net proceeds. Nothing fancy. But the devil is in the details, and most free online calculators miss at least one of them.
Using a Proceeds Calculator Without Losing Money
Start by gathering three numbers: your estimated sale price, your remaining mortgage balance, and the commission structure. Those are the anchors. Everything else branches off them. If you're working with a buyer agent and a seller agent, factor both sides of the commission. Some transactions split 2.5% to each side, others negotiate differently. Don't assume. From there, run through the checklist. Transfer taxes vary wildly by jurisdiction and sometimes by property value tier. In one county I dealt with, the rate stepped up at $400,000, $600,000, and $1,000,000, so a property that sold for $999,000 cost roughly $2,400 less in transfer taxes than one at $1,001,000. That gap mattered to my client. Most basic calculators don't handle tiered transfer tax structures at all. You end up plugging in the numbers manually or finding a tool that actually supports local regulations. Recording fees are another quiet expense. Usually a few hundred dollars, but in some counties it scales with the deed value. Title insurance premiums differ between owner's and lender's policies. Home warranty plans, if the seller pays them, run a flat rate. HOA transfer fees, capital gain projections if you own the property long enough, and even utility proration can shift the final number by a couple thousand dollars depending on how thorough you are.
The best approach is to use a Proceeds Calculator that lets you input line items rather than relying on a single percentage estimate for everything. Generic calculators typically assume a 5 to 6 percent total commission and bolt on a flat closing cost figure. That works for a rough sketch. It fails when you're trying to decide whether to negotiate the seller credit on repairs or let the buyer walk. I once had a scenario where the calculator showed a client about $47,000 in net proceeds, but after I dug into the specifics — a local special assessment lien the county had placed on the property for sidewalk work, a non-standard HOA transfer fee, and a municipal recapture tax on a down-payment assistance program the seller had used years ago — the real number dropped to just over $38,000. That fifteen-thousand-dollar gap came from things no generic tool flags. My workaround was building a custom spreadsheet with the exact lien search results and the assistance program payoff schedule, then feeding those into the calculator as fixed line items instead of estimates.
Get the Full Details
The Counter-Intuitive Stuff Nobody Talks About
Most people treat the sale price as the starting point and everything else as deduction. The more accurate way is to work backward from your minimum acceptable proceeds. If you need $50,000 to walk away clean, and your costs add up to roughly 10 to 12 percent of the sale price plus any fixed debt, you actually need to list higher than you think. A common mistake is listing at exactly what covers the mortgage and a little extra, then discovering the closing costs ate the surplus. Another thing that trips people up: the difference between gross proceeds and net proceeds. Gross is the sale price minus the mortgage payoff. Net is everything after every fee, credit, and adjustment. The gap between those two numbers in a typical residential transaction usually lands between 8 and 14 percent of the sale price, depending on location and deal structure. If a calculator only shows gross, it's not giving you the answer you actually need. Capital gains tax deserves its own mention. Some calculators include it. Many don't. If you've lived in the home for at least two of the last five years, you may qualify for an exclusion — up to $250,000 for single filers or $500,000 for married filing jointly — but that only applies if the property wasn't used as a rental before you moved in, or at least not recently. Mix in rental history and the calculation gets complicated fast. A Proceeds Calculator won't sort that out for you. You need a tax professional or at least a solid estimate from one before you sign anything.
When This Tool Completely Falls Apart
There are situations where a proceeds calculator is barely useful. Short sales and foreclosures are the main ones. In a short sale, the lender decides what they'll accept, and their approval number often has nothing to do with your calculator's output. The calculator tells you what should happen. The bank tells you what will happen. Fixer-uppers with renovation value plays suffer the same problem. If you're buying a distressed property, flipping it, and using a proceeds calculator to model your exit, the numbers only hold if comps behave. Markets shift. Inventory dries up. Your predicted sale price evaporates in a quarter. There's also the issue of seller concessions. If the buyer negotiates credits for repairs or closing costs, those come out of your proceeds too. Some calculators let you input concessions. Many don't. And when they do, they often misclassify them as buyer-side costs instead of seller-side deductions. That shifts your entire projection by the concession amount.
If you're dealing with any of those scenarios, skip the standalone calculator and build a detailed model in a spreadsheet or use a more specialized tool. A simple Proceeds Calculator will give you a false sense of precision. That's worse than having no number at all, because you'll make decisions based on it.
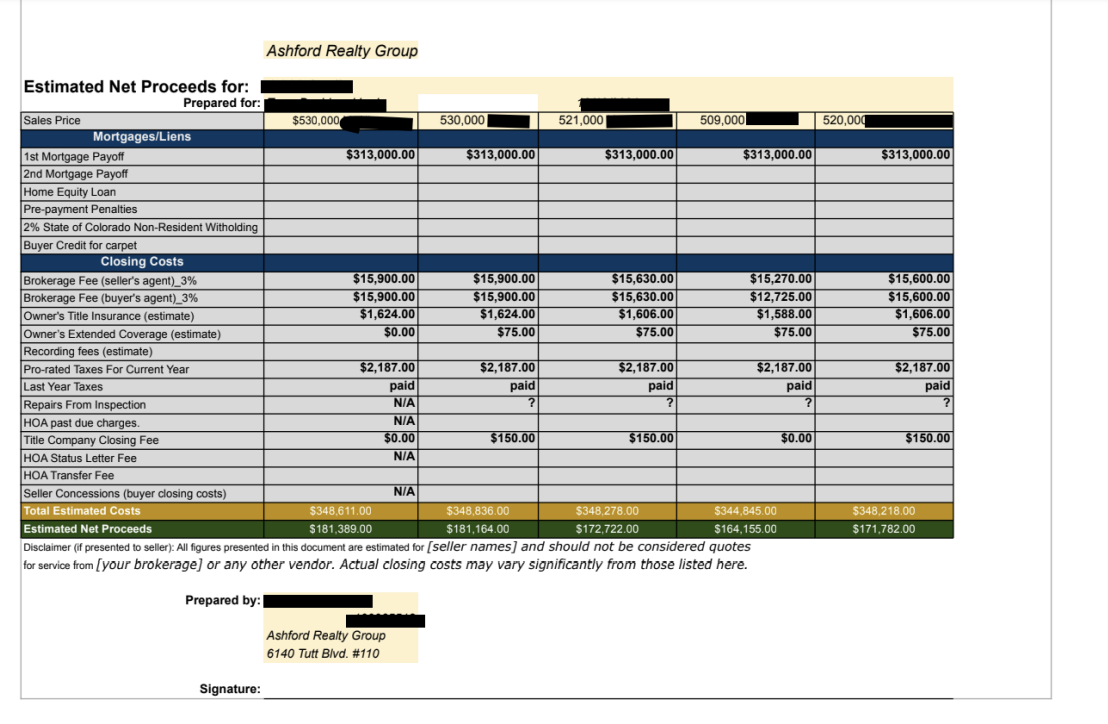
What to Look For in a Good Calculator
Pick one that breaks out line items instead of lumping closing costs into a single field. You should be able to see commission, title, escrow, transfer taxes, HOA fees, and any adjustments separately. If it doesn't let you customize or add custom line items, it's going to leave gaps. Regional support matters more than people realize. A tool that works for California will undercount by thousands in New Jersey due to stamp taxes. Another that assumes standard two-agent splits will misfire on for-sale-by-owner transactions where you still owe a buyer agent commission. Check that the calculator reflects the market you're actually in. Speed is worth something too. A decent Proceeds Calculator should generate results in under a minute once your data is entered. If it takes five minutes to figure out how to use it, you're better off with a spreadsheet and a clear formula. There are plenty of free templates online. The ones that cost money usually offer nothing extra unless they include automated lien lookup or integration with your local MLS data, which is rare outside of paid professional platforms.
The bottom line is that a calculator is a planning tool, not a prediction. It shows you what the math looks like given your assumptions. When those assumptions shift — and they always do — the output shifts with them. That's why the best use of a Proceeds Calculator is early in the process, to set realistic expectations, then revisiting it once you have actual offers and inspected conditions in hand.