Buying a car isn't complicated, but dealerships profit from you skipping steps
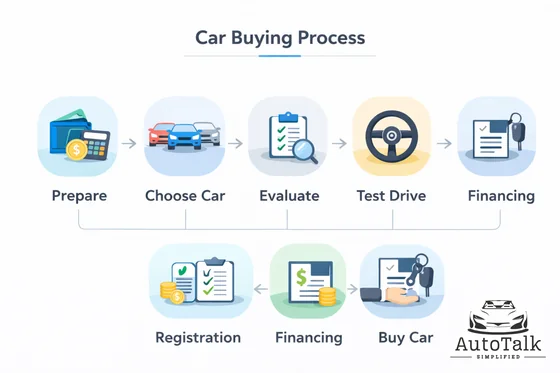
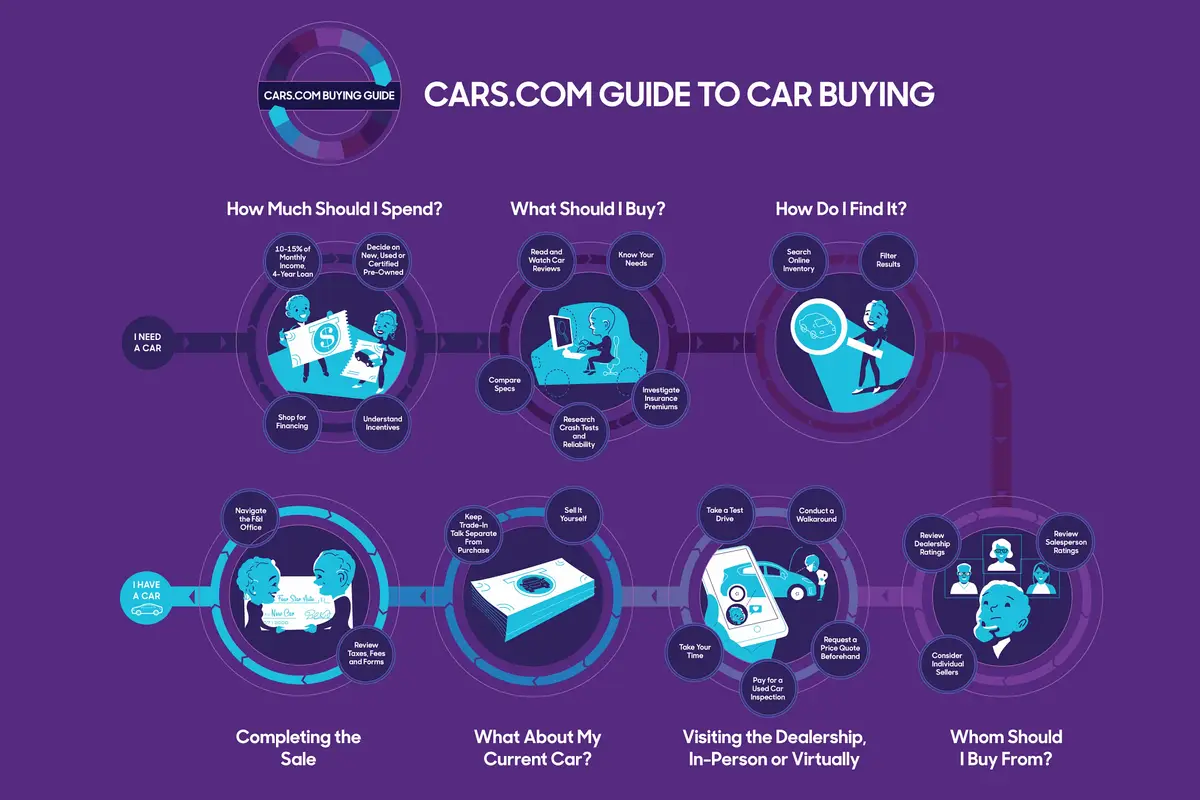
I spent a lot of years in auto retail and then on the consumer side after that. The things I see people mess up consistently are the same every time. They show up without research, they let the salesperson dictate the pace, and they roll the payment around so much that nobody can figure out what the car actually cost. This guide is about walking into a dealership or looking at a private sale with your eyes open. Start with the budget. Not the monthly payment. The total budget. Figure out the maximum out-the-door price you're willing to pay, including tax, title, registration, and any dealer fees that are non-negotiable. When you only think in monthly payments, you can be talking about a $40,000 car and still feel good about it because the payment looks "reasonable" after stretching it over seven years at a high interest rate. That's how you end up owing three times the car's value. Get pre-approved for financing before you walk into a dealership. Credit unions usually beat bank rates, and online lenders like LightStream or Auto Financial Group can give you a solid baseline number in about ten minutes. Walk in with that pre-approval letter and you've already changed the entire dynamic. The dealer will still try to beat it, but now you have a floor you can measure everything against instead of hearing numbers blind.
Research the exact vehicle online first. Use Kelley Blue Book, Edmunds, and TrueCar to find the fair purchase price in your zip code. Don't rely on the sticker. The sticker is a proposal, not a fact. When I was working lots, we'd get inventory with holdbacks and rebates that the MSRP didn't reflect. Knowing the invoice price and the destination charge lets you spot when a deal is actually bad. For example, a 2019 Highlander with 40,000 miles might list for $28,000 but the fair price in my market was closer to $24,500. That's a real gap, not a negotiation fantasy. Get the out-the-door price in writing before you come in. Email the salesperson or use the chat function on the dealer's site. Ask specifically for the out-the-door number with no hidden add-ons. Most dealers will give you a number that includes things like paint protection, nitrogen tires, and fabric guard that cost them roughly nothing and carry a huge markup. One time I had a dealer quote me $3,200 in add-ons that weren't even offered on the vehicle I wanted. I pointed out each line item and asked which one applied. They removed $2,800 of it immediately. Those products are almost entirely optional. When you go to the dealership, focus on the total price first. Do not let them pivot to monthly payments. If they ask what payment you want, say "I'm buying the car, not renting it. Give me the out-the-door number and we'll talk about financing from there." This shift alone will change how serious they take you. Salespeople are trained to move the conversation to payments because it's easier to manipulate a monthly figure than a total price.
Test drive with a purpose. Check for things that matter past the first five minutes: engine noises under acceleration, transmission shifting smoothness through all gears, brake pedal feel, steering pull, and whether the infotainment system responds quickly or lags. I once bought a used truck that ran fine at idle and at highway speeds but had a hard clunk when shifting from drive to reverse at low speed. The dealer swore it was normal. It wasn't. I took it to an independent mechanic and found a worn transfer case mount. That repair ran about $600. The dealer would have known exactly what was wrong because they'd seen it a dozen times. The inspection step is where most buyers skip. Get a pre-purchase inspection from an independent mechanic before you hand over any money on a used car. This isn't a formality. It's the single most important step in the entire process. A $150 inspection can save you $3,000 in repairs you'd discover three months later. Some dealers resist this because they know their reconditioning department misses things. If a dealer says "we don't allow outside inspections," that's a red flag worth walking away from immediately.
Get the Full Details
Where deals actually go sideways
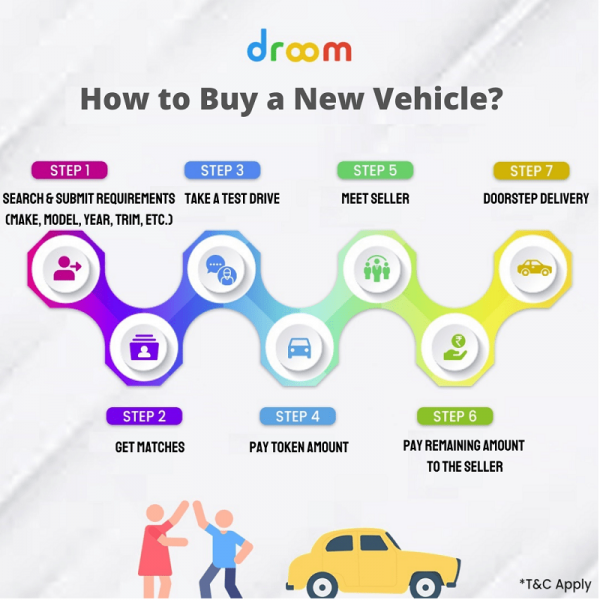
The biggest trap is the trade-in conversation happening at the wrong time. If you tell the salesperson about your trade early, they'll roll it into the deal and confuse the math. They'll give you a low trade value, inflate the new car price slightly, and make the whole transaction look better than it is. Do your trade research separately on KBB and CarMax before you go in. Know what your car is worth as a private sale and what a dealer would realistically pay. Then discuss the trade last, after the new car price is locked in. Another trap is the extended warranty push. Dealer warranties carry enormous markups. A powertrain warranty that costs the dealer $400 might sell for $1,500. Third-party warranties from companies like Endurance or CARCHEX often cover the same things at a third of the price. The dealer's profit margin on these is one of their highest. I've sat in rooms where the manager would sit with a customer for twenty minutes pushing a $2,000 bumper-to-bumper warranty on a car that came with a remaining factory warranty already covering most of the same components. It's a grind to keep saying no, but it's worth it. Here's a counter-intuitive point about timing: the end of the month isn't always the best time to buy. Dealership monthly quotas matter, yes, but so does annual inventory management. Late December can be strong because dealers want to clear out the current model year before the new ones arrive. Early summer is good for trucks and SUVs when demand drops. And Thursday through Saturday is usually when salespeople are most available because the weekend rush hasn't hit yet. Monday mornings are when you'll get the most attention from a manager who has quota pressure and nobody else in the building.
The document review stage is where people sign too fast. Take your time reading every page. Check the vehicle identification number on the contract matches the car. Verify the agreed-upon price is actually what's on the contract. Look for any fees you didn't agree to. I had a friend who signed a contract and didn't notice a $149 "document preparation fee" that wasn't in the original quote. It's a small amount individually but these fees add up and they're rarely advertised upfront. In some states, document fees are capped. In others, they're unlimited. Knowing your state's rules helps.
A real problem I ran into and how I handled it
I was helping a buddy buy a used Ford F-150 from a independent lot about six years ago. The vehicle history report looked clean, the inspection came back okay, and the price was fair. We got to the financing part and the dealer's lender offered us a rate that was 4 percentage points higher than our pre-approval. When I asked why, the finance manager said the truck had a " rebuilt" title and that made it higher risk in their system. The CarFax report I'd pulled didn't clearly flag it as rebuilt versus salvage. The title paperwork on the desk showed "rebuilt" but it was stamped over something else, and we hadn't caught it in the quick glance. The workaround was simple but easy to miss: I pulled the full VIN report directly from the state's DMV website, not just the third-party service. The state record showed the vehicle had been declared a total loss by an insurance company, repaired, and recertified as rebuilt. That's legal in our state, but it affects financing rates, insurance costs, and resale value. Armed with that, we walked away from the dealer's financing and used my pre-approval instead. The rate difference saved us roughly $2,200 over the life of the loan. The title issue was the kind of thing that gets glossed over if you're just looking at a summary report and not the actual title document.

Private sales versus dealerships
Private sales can save you significant money because there's no dealer markup. But they come with different risks. You won't have a warranty of any kind unless the seller offers one in writing, which almost never happens. You also handle the title transfer yourself, and that's where mistakes happen. In some states, the seller needs to notarize the title. In others, you need to fill out a separate odometer disclosure form. Skip the right steps and you could be stuck with a title that doesn't transfer cleanly. For private sales, meet at the buyer's bank or a notary public if one is available. Exchange money and paperwork in a supervised setting. Run the VIN through a paid report like Alex or NICB before you hand over any cash. And never accept a title that isn't in the seller's name matching their ID. I've seen cases where someone tried to sell a car with a title that listed a different owner, usually because the vehicle was still under a loan or the previous owner had passed away. These situations can tie up your registration for months.
The paperwork you actually need to have ready
Bring your driver's license, proof of insurance if the dealer requires it upfront, and your proof of income if you're self-employed and the dealer's lender asks for it. For private sales, bring a cashier's check or arrange the transfer at a bank. Personal checks from buyers raise flags for sellers because they can bounce. Having cash or a guaranteed check speeds everything up and makes sellers more willing to negotiate. After the sale, make sure you get the title properly assigned, the bill of sale, and any warranty documents. Keep copies of everything. File your tag and title application with your DMV promptly. Delayed registration can result in fines in some states. If you're financing, the lender will hold the title, but you should still get a copy of the signed contract and lien documentation for your records. The whole process from start to finish usually takes between four and eight hours for a first-time buyer at a dealership if everything goes smoothly. If you do your homework beforehand, you can cut that down to about two hours. The extra time people spend at the dealership is almost always in the finance office, where the conversation shifts from price to products and payment options. Staying focused on the total price and having your financing sorted in advance is the single biggest time saver.
One last thing that surprises people: dealer add-ons are almost always negotiable. Window tint, undercoating, wheel locks, VIN etching, air freshener kits. These are things they slap on right before delivery. You can ask them to remove any or all of them before you sign. I've had dealers remove $1,800 worth of add-ons just by asking politely but firmly. They'd already marked them up 300 percent and knew nobody was going to miss them. Don't assume the price they quoted includes everything you're obligated to keep.