What this actually is
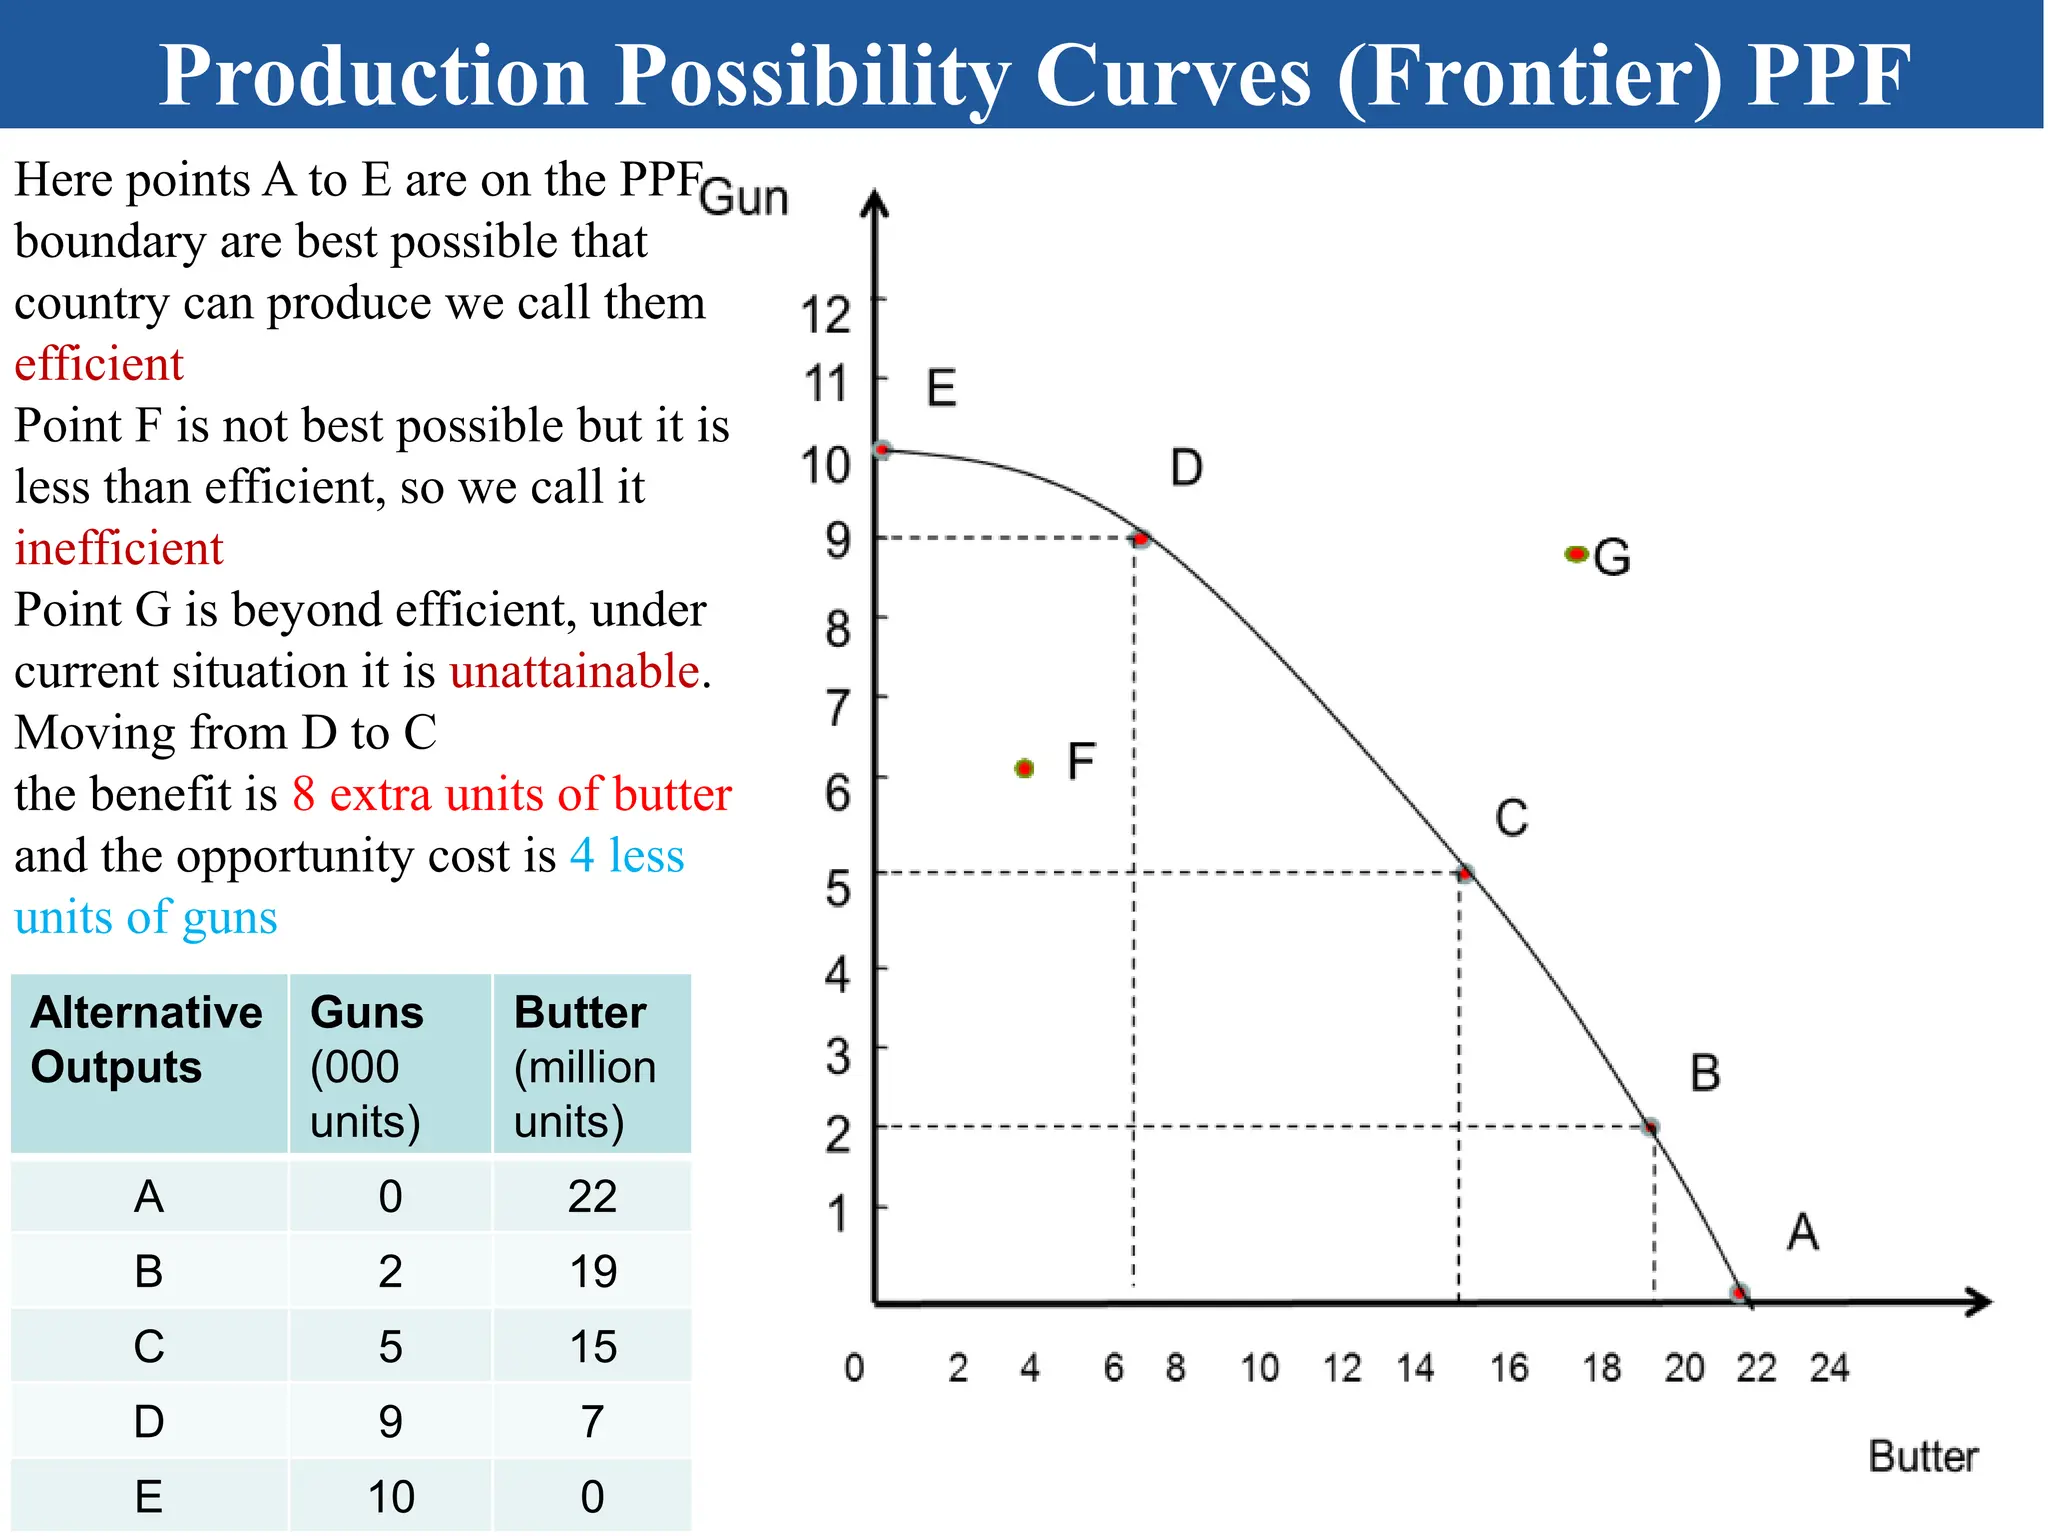
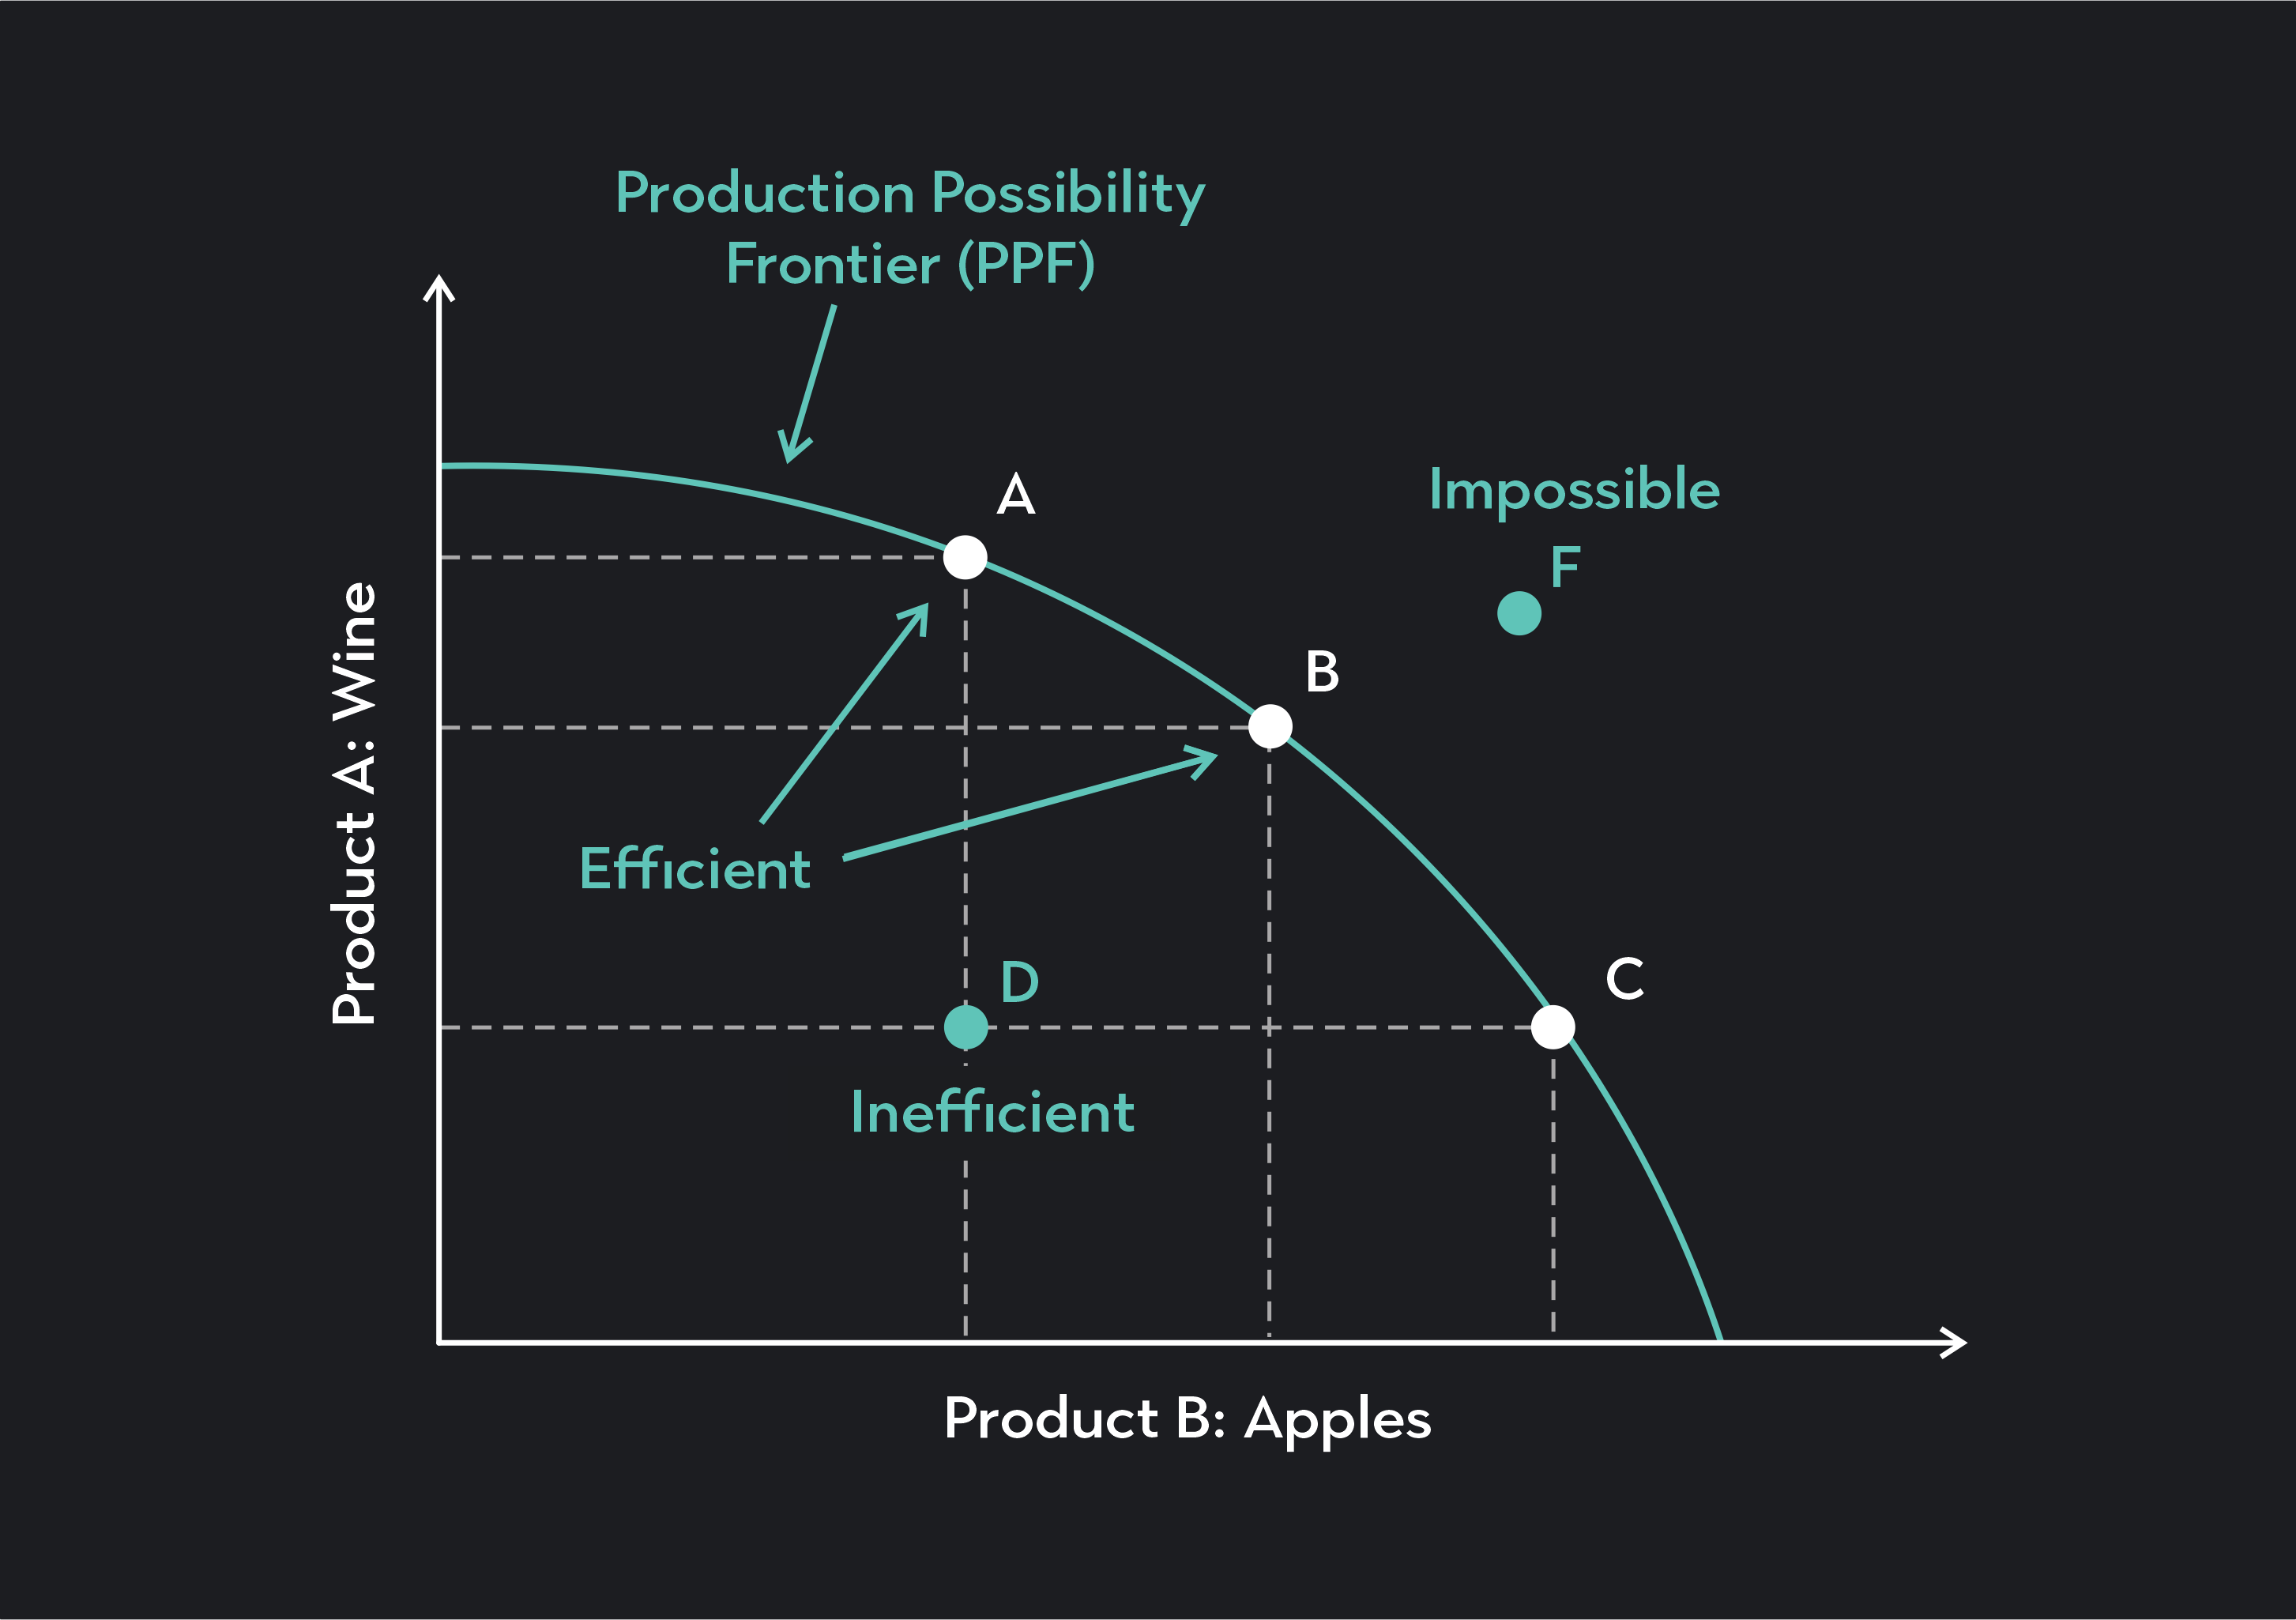
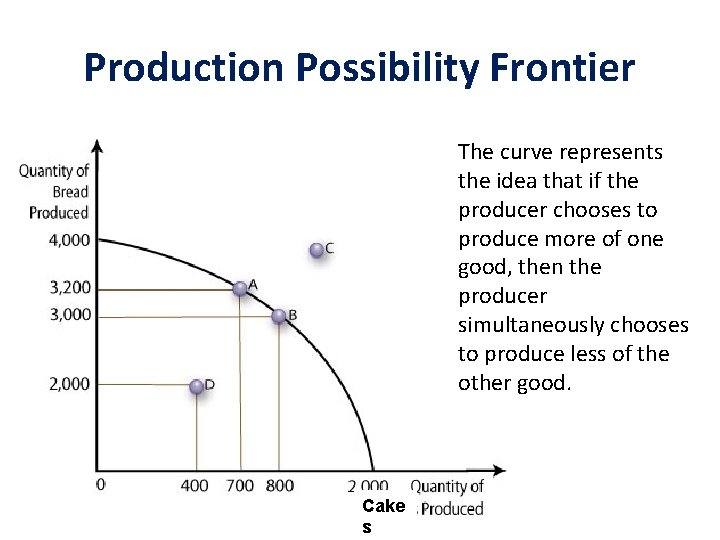
The Production Possibility Curve And Production Possibility Frontier are basically the same thing. The terms get used interchangeably in textbooks, which is annoying but not worth losing sleep over. It is a model that shows the maximum output combinations of two goods an economy can produce when all resources are fully and efficiently employed. Everything inside the curve is technically possible but inefficient. Points on the curve represent efficient production. Points outside it are unattainable with current resources and technology. Here is how I actually use it in practice rather than how the intro textbooks present it. You start by picking two goods you want to model — real-world example, let us say it is consumer goods versus capital goods, or maybe it is healthcare spending versus education spending. Then you list your constrained resources: labor, capital stock, land, technology. The key assumption most people skip is that resources are fixed in the short run. If you relax that assumption, the whole exercise changes completely. I build these curves in a spreadsheet. Column A is good one quantity. Column B is good two quantity. You calculate opportunity costs for each incremental shift. The slope of the curve at any point is the marginal rate of transformation. When the curve is bowed outward, it reflects increasing opportunity costs. That happens because not all resources are equally suited to producing both goods. A software engineer shifting into agriculture does not immediately produce wheat at the same rate. That bowed shape is not decorative. It is the economic reality of specialization.
One edge case that trips people up every single time is what happens when one good is produced in zero quantity. The intercept on the axis tells you the absolute maximum of that single good if you devoted everything to it. I have seen analysts ignore the intercepts and only focus on interior points. That misses half the model. Always plot the intercepts first. It takes thirty seconds and prevents stupid mistakes later. Here is the part nobody emphasizes enough: the curve assumes full employment of resources. In the real world, we rarely see that. A recession shifts your effective position inside the curve. You are producing at a point like 40 percent of good X and 30 percent of good Y when the curve would allow 60 and 50. That gap between where you are and where the frontier sits is called the output gap. Measuring it is useful. Most macro models treat it as a residual and never quantify it properly. I worked on a project once where we were modeling regional allocation between infrastructure maintenance and new construction. The textbook curve suggested we should be at a specific efficient point. But the data showed we were actually inside the curve by a wide margin. The problem was not a resource constraint. It was bureaucratic fragmentation. Different departments controlled different budgets and could not coordinate. The workaround was to model a combined agency scenario and show the efficiency gain as a shift from inside the curve toward the frontier, not as a shift of the frontier itself. That distinction matters. Moving inward or outward on the curve is about efficiency. Shifting the entire curve is about growth in resources or technology.
Another common mistake: people confuse a shift of the curve with a movement along the curve. A movement along the curve means you are reallocating resources between the two goods. The total resource pool stays the same. A shift outward means you got more resources or better technology. An shift inward means you lost resources, maybe through war, natural disaster, or institutional collapse. I see this confusion constantly in policy debates. Someone will say the economy needs to move along its production possibilities toward more green energy. But if the actual constraint is capital scarcity, you need the curve to shift first. Moving along a shrinking curve just means producing less of everything faster. There is also the issue of diminishing returns versus constant returns. Some introductory courses draw the curve as a straight line, which implies constant opportunity cost. That is only realistic if resources are perfectly substitutable between the two goods. In almost any real economy, that assumption breaks down. The bowed shape is the normal case. Do not be surprised when your empirical calibration refuses to fit a linear model. It is not a data problem. It is the theory telling you something true about the world. If you are using this for policy analysis, remember the limitations bluntly. The model is strictly dyadic. It handles two goods. Real economies produce thousands. You can collapse everything into two aggregate categories, but that aggregation hides enormous detail. A health-versus-education model will never capture the tradeoff between manufacturing and services, or between domestic and foreign production. For high-level strategic thinking the dyadic reduction is fine. For operational decision-making it is dangerously reductive.
Get the Full Details
Another limitation is the static nature. The standard curve is a snapshot. It does not show the path of adjustment. If you move from point A to point B on the curve, the transition can be painful. There are unemployment periods, retraining costs, stranded assets. The model assumes frictionless reallocation, which is never true. I learned this the hard way when modeling a region transitioning from coal mining to renewable energy. The curve suggested a smooth reallocation. The reality was a decade of depressed output before the new industries absorbed the displaced labor. The model was not wrong. It was just incomplete. For anyone actually applying this rather than just passing an exam, start with a clear definition of what the two goods represent, make sure your resource constraints are grounded in actual data, and always check whether you are talking about efficiency or growth. Confusing the two leads to completely different policy prescriptions. An efficient point on a shrinking curve is still a bad outcome. That is the takeaway most people miss.