What Actually Works When You Need Proof Of Income
A proof of income letter is just a document that says how much money you make. That's it. But getting one signed and accepted isn't as simple as writing a quick email to your boss, which is why people keep running into problems at the last minute. I spent years processing these for mortgage applications, lease approvals, and visa submissions. The ones that get rejected almost always share the same issues: missing dates, vague language, or using the wrong format for the requesting party's requirements.
How to Write a Proof Of Income Letter
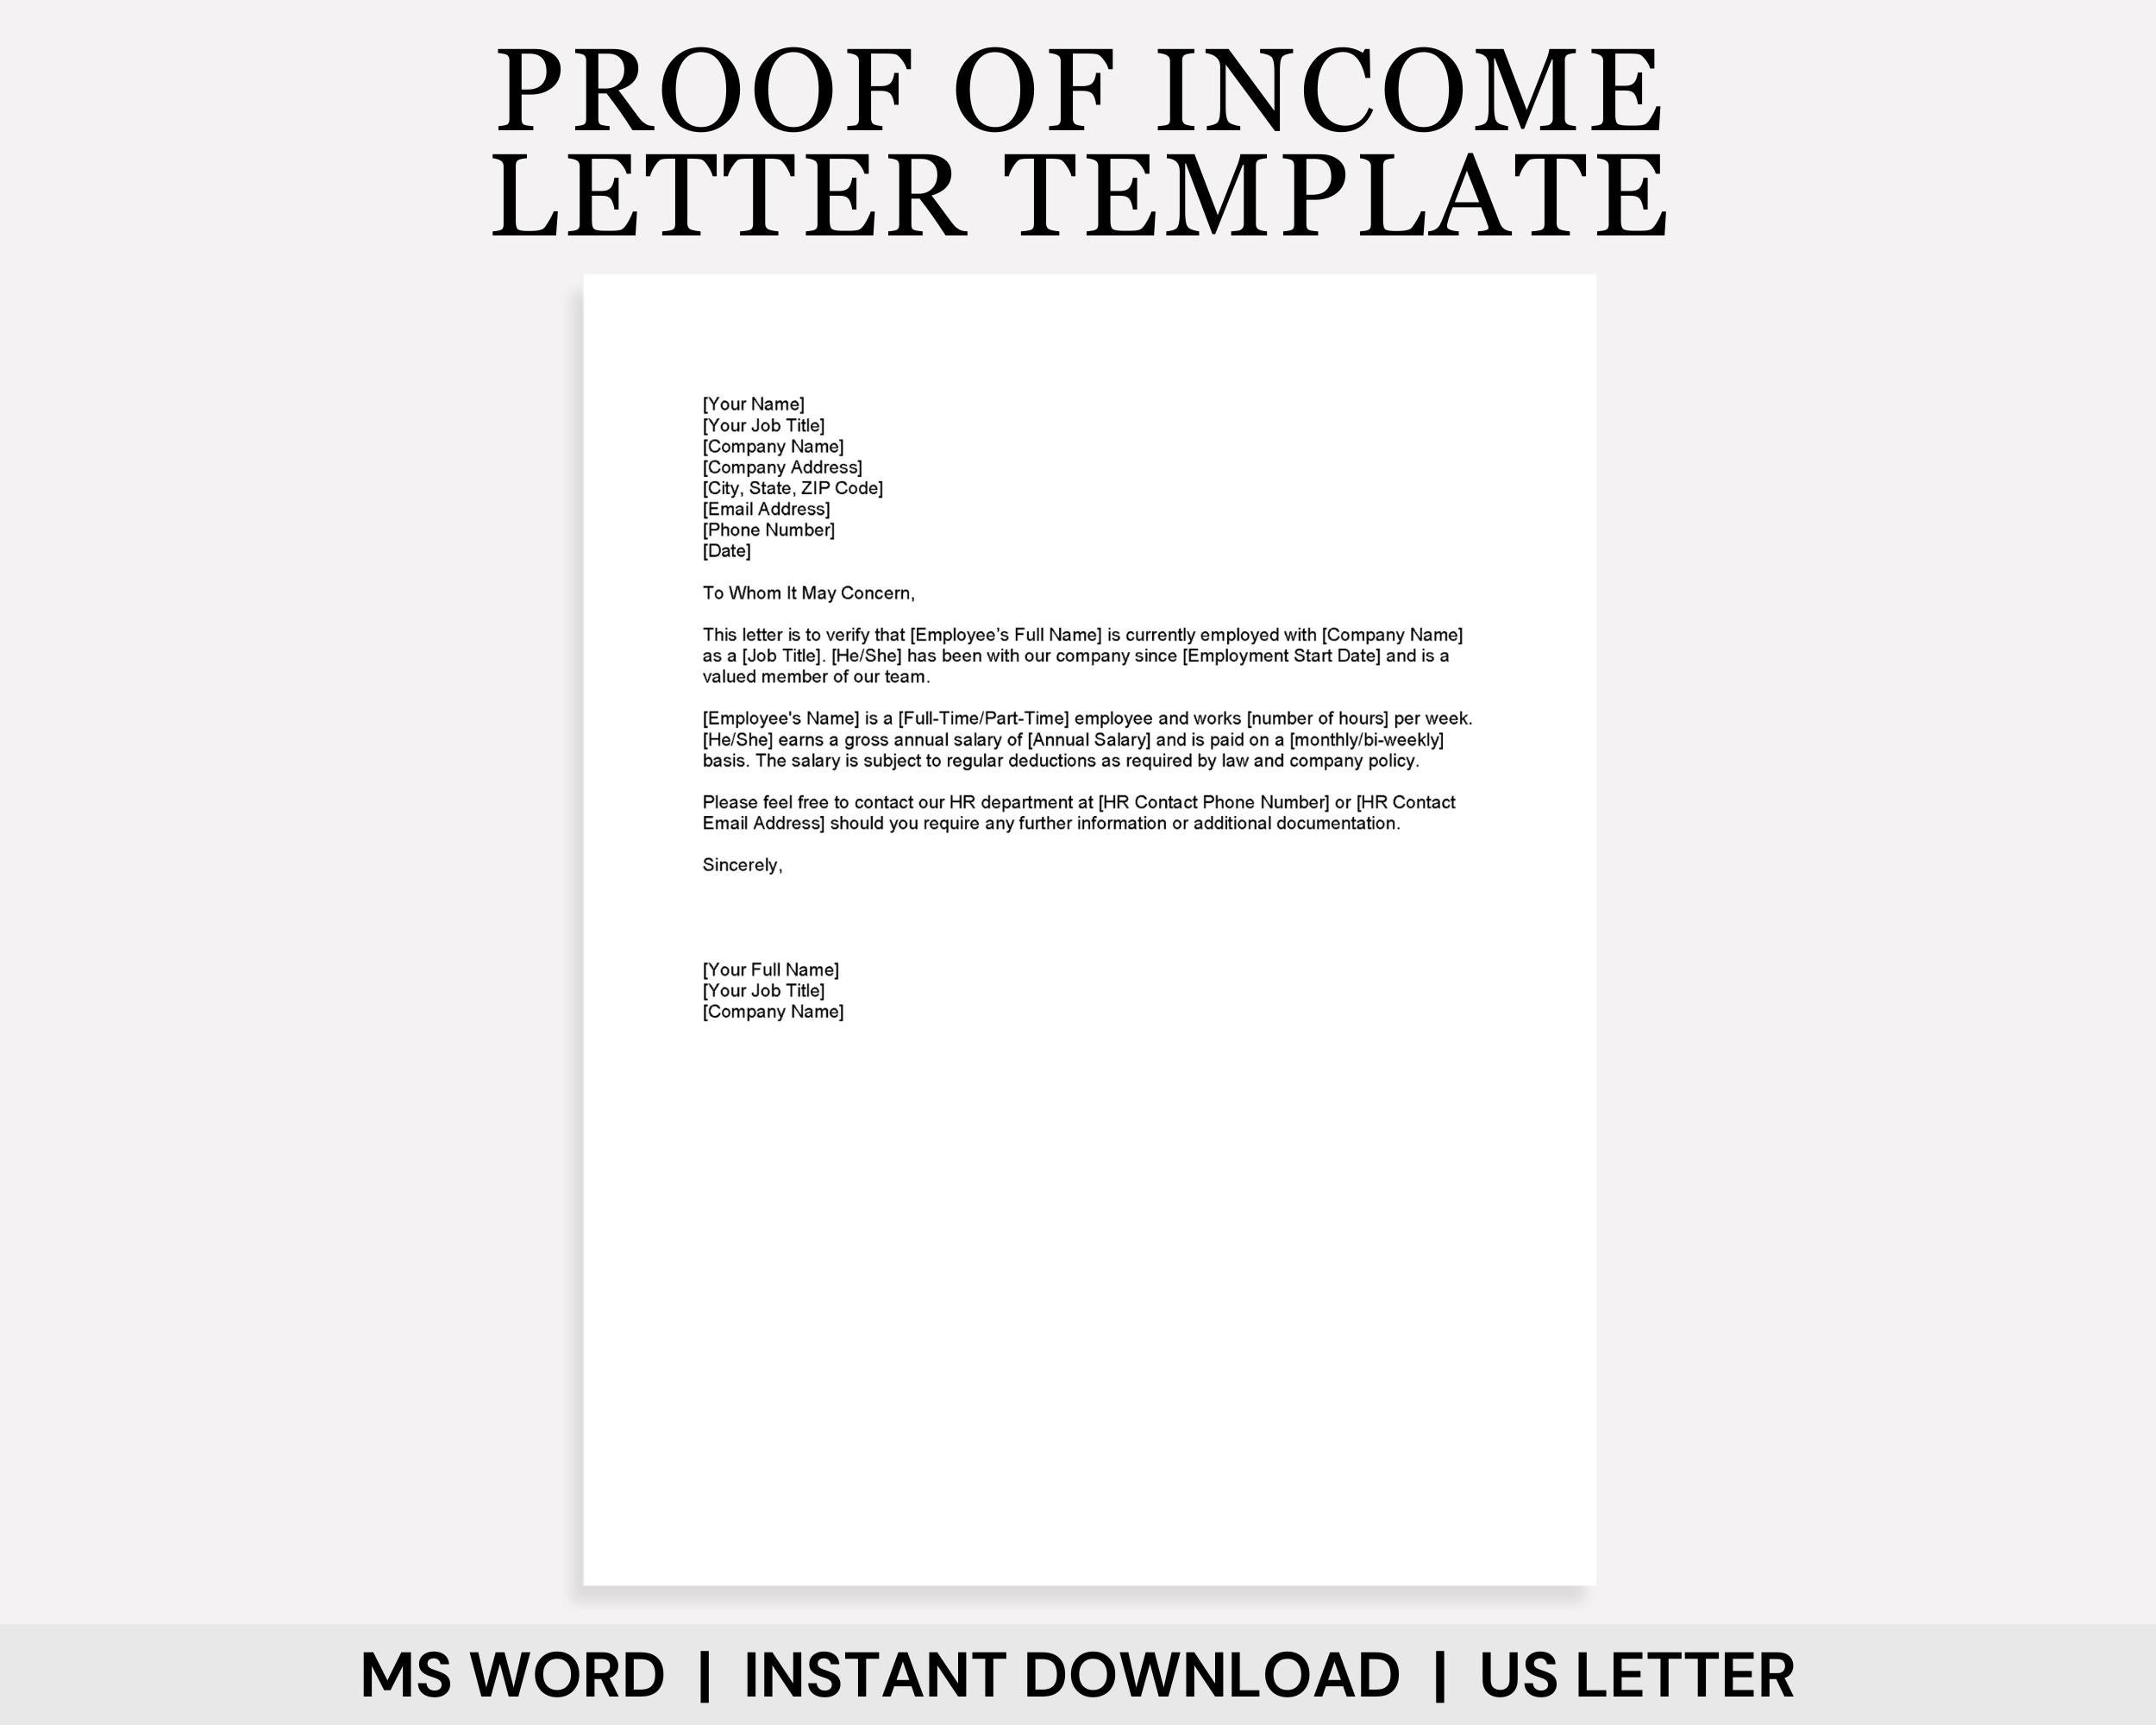
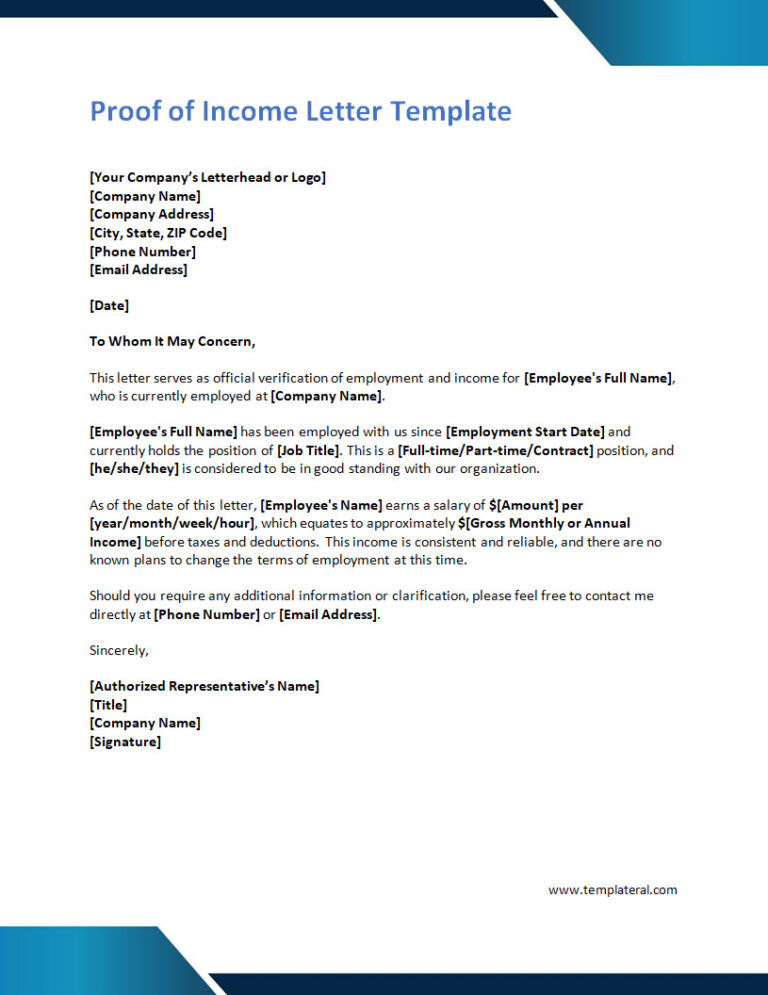
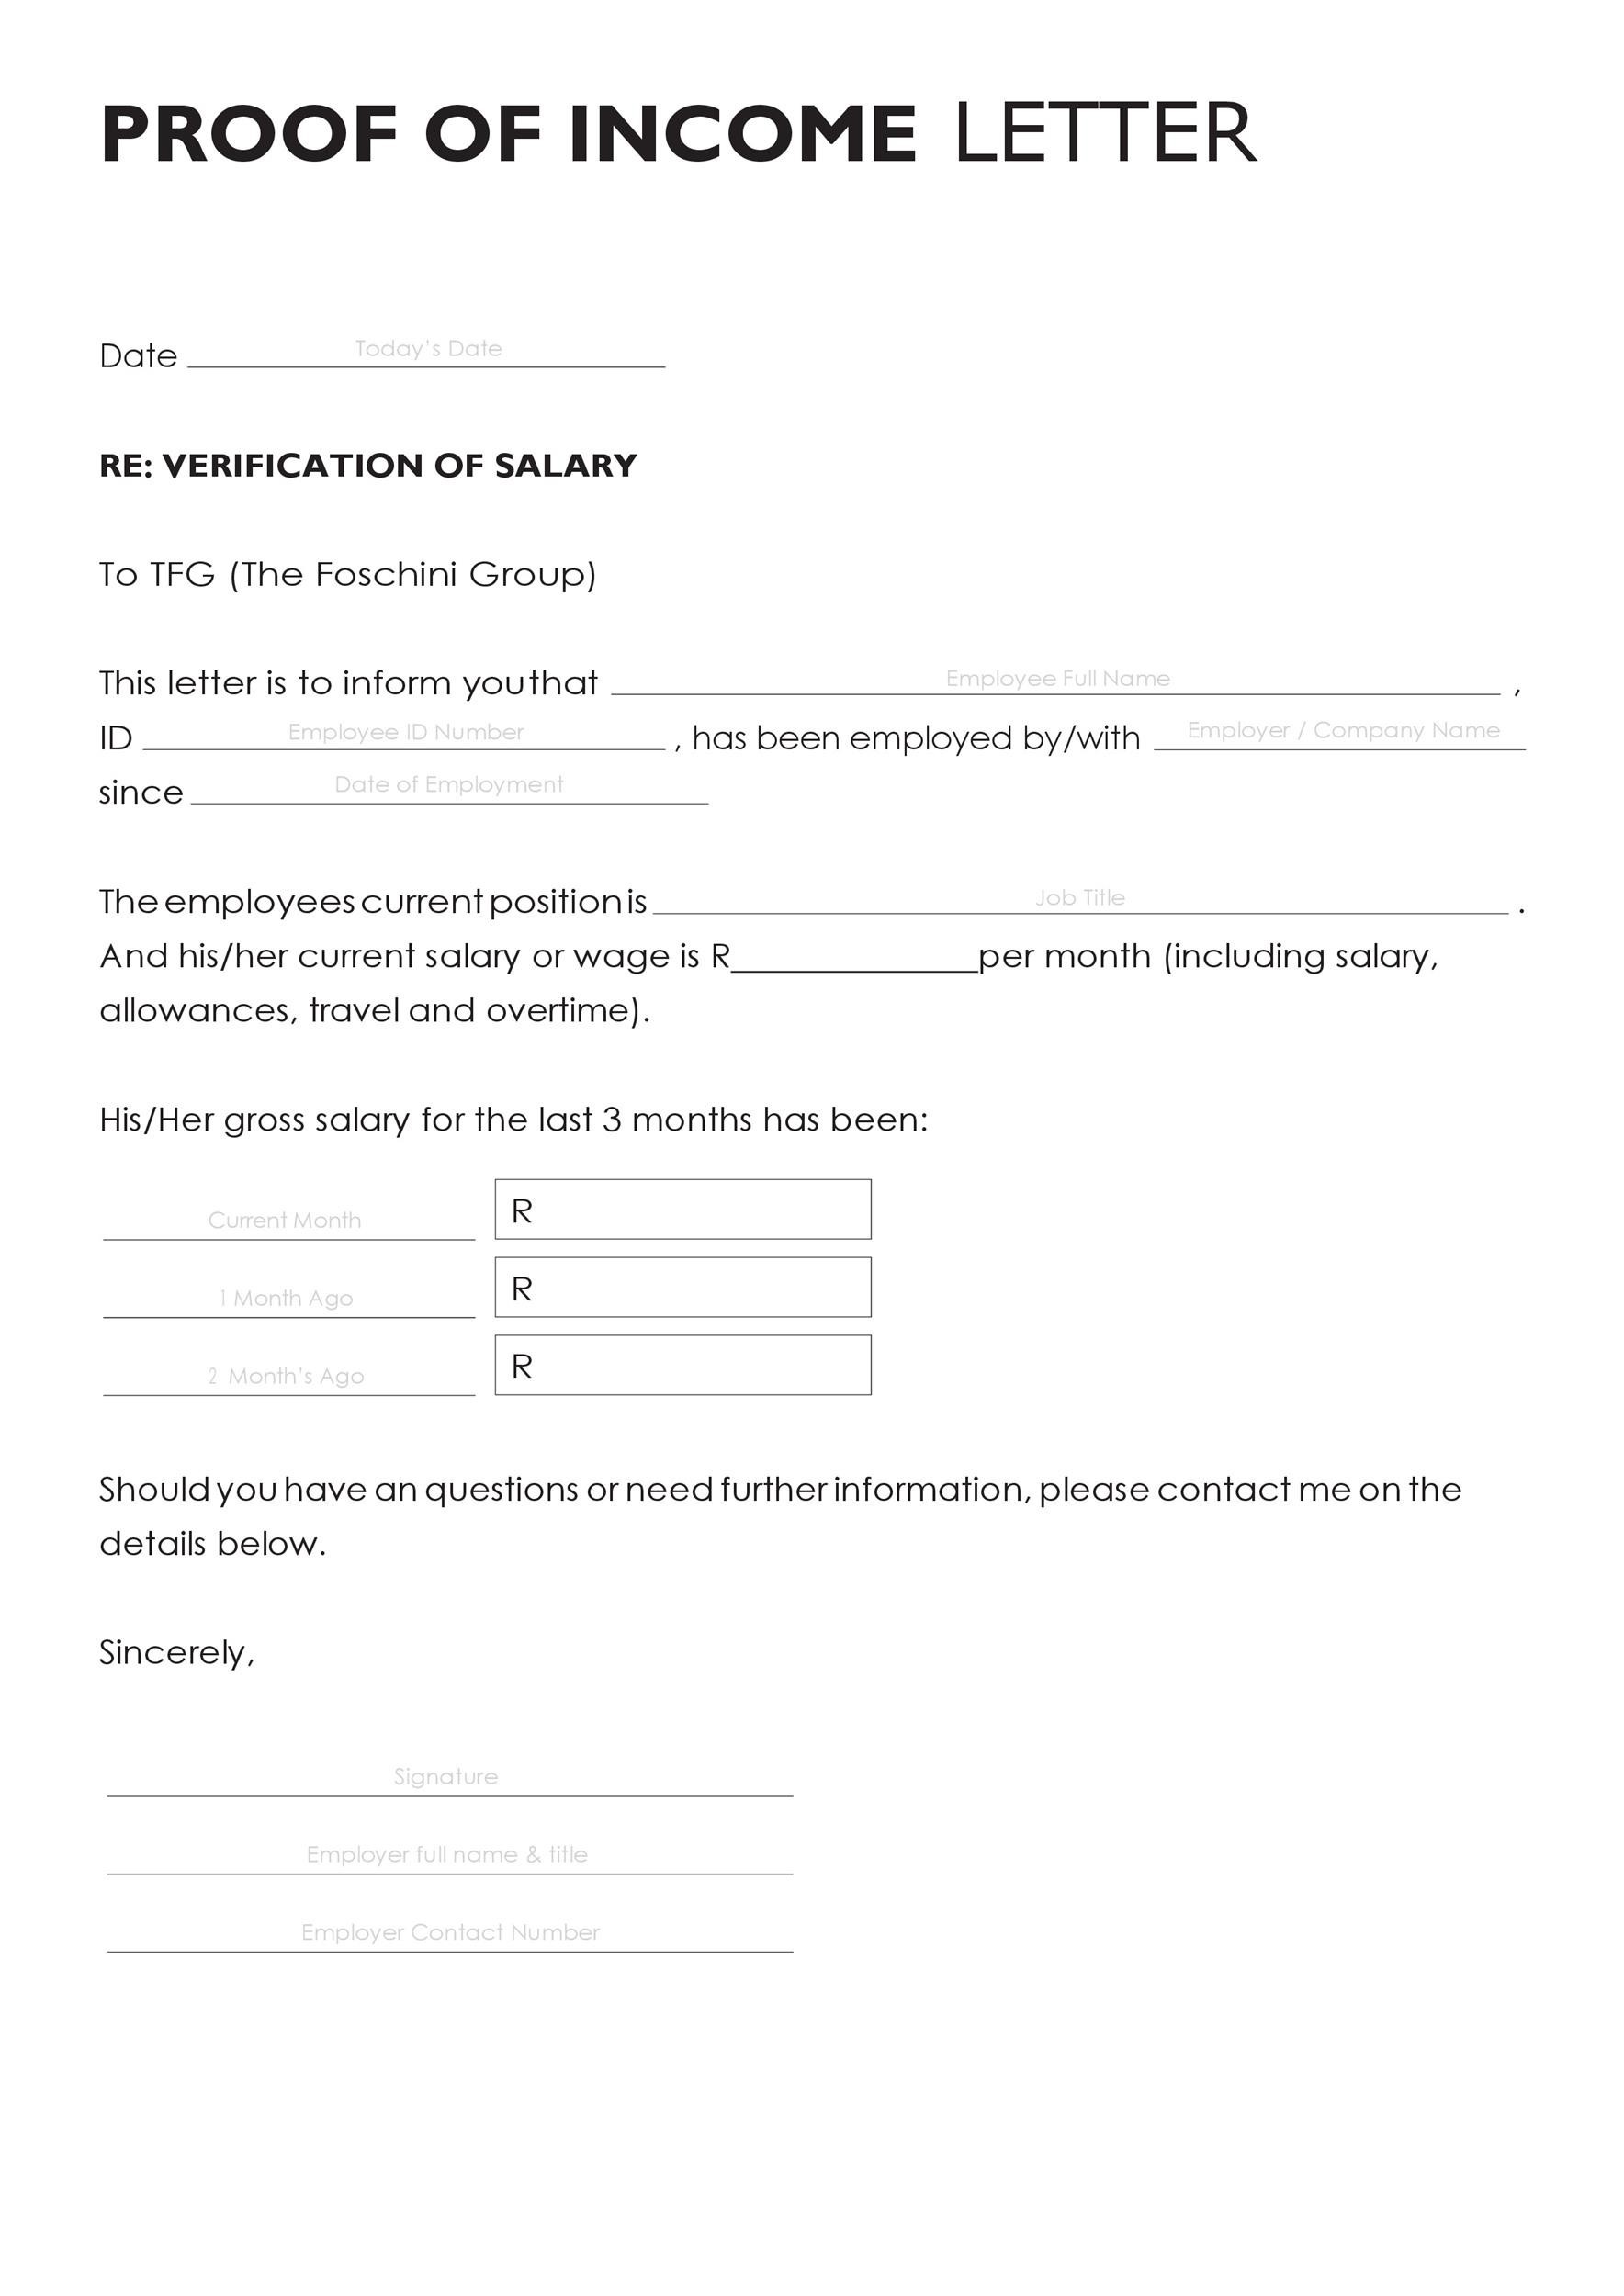
Start with your letterhead if you have one. If you're an employee, your employer's HR department typically handles these requests. They usually have a standard template, which is actually the safer route because it already includes the information banks and landlords expect to see. If you need to draft it yourself, here's what needs to be on there: Your full name and address
The date the letter is written The employer's name, address, and contact information Your job title and employment status (full-time, part-time, contract)
Get the Full Details
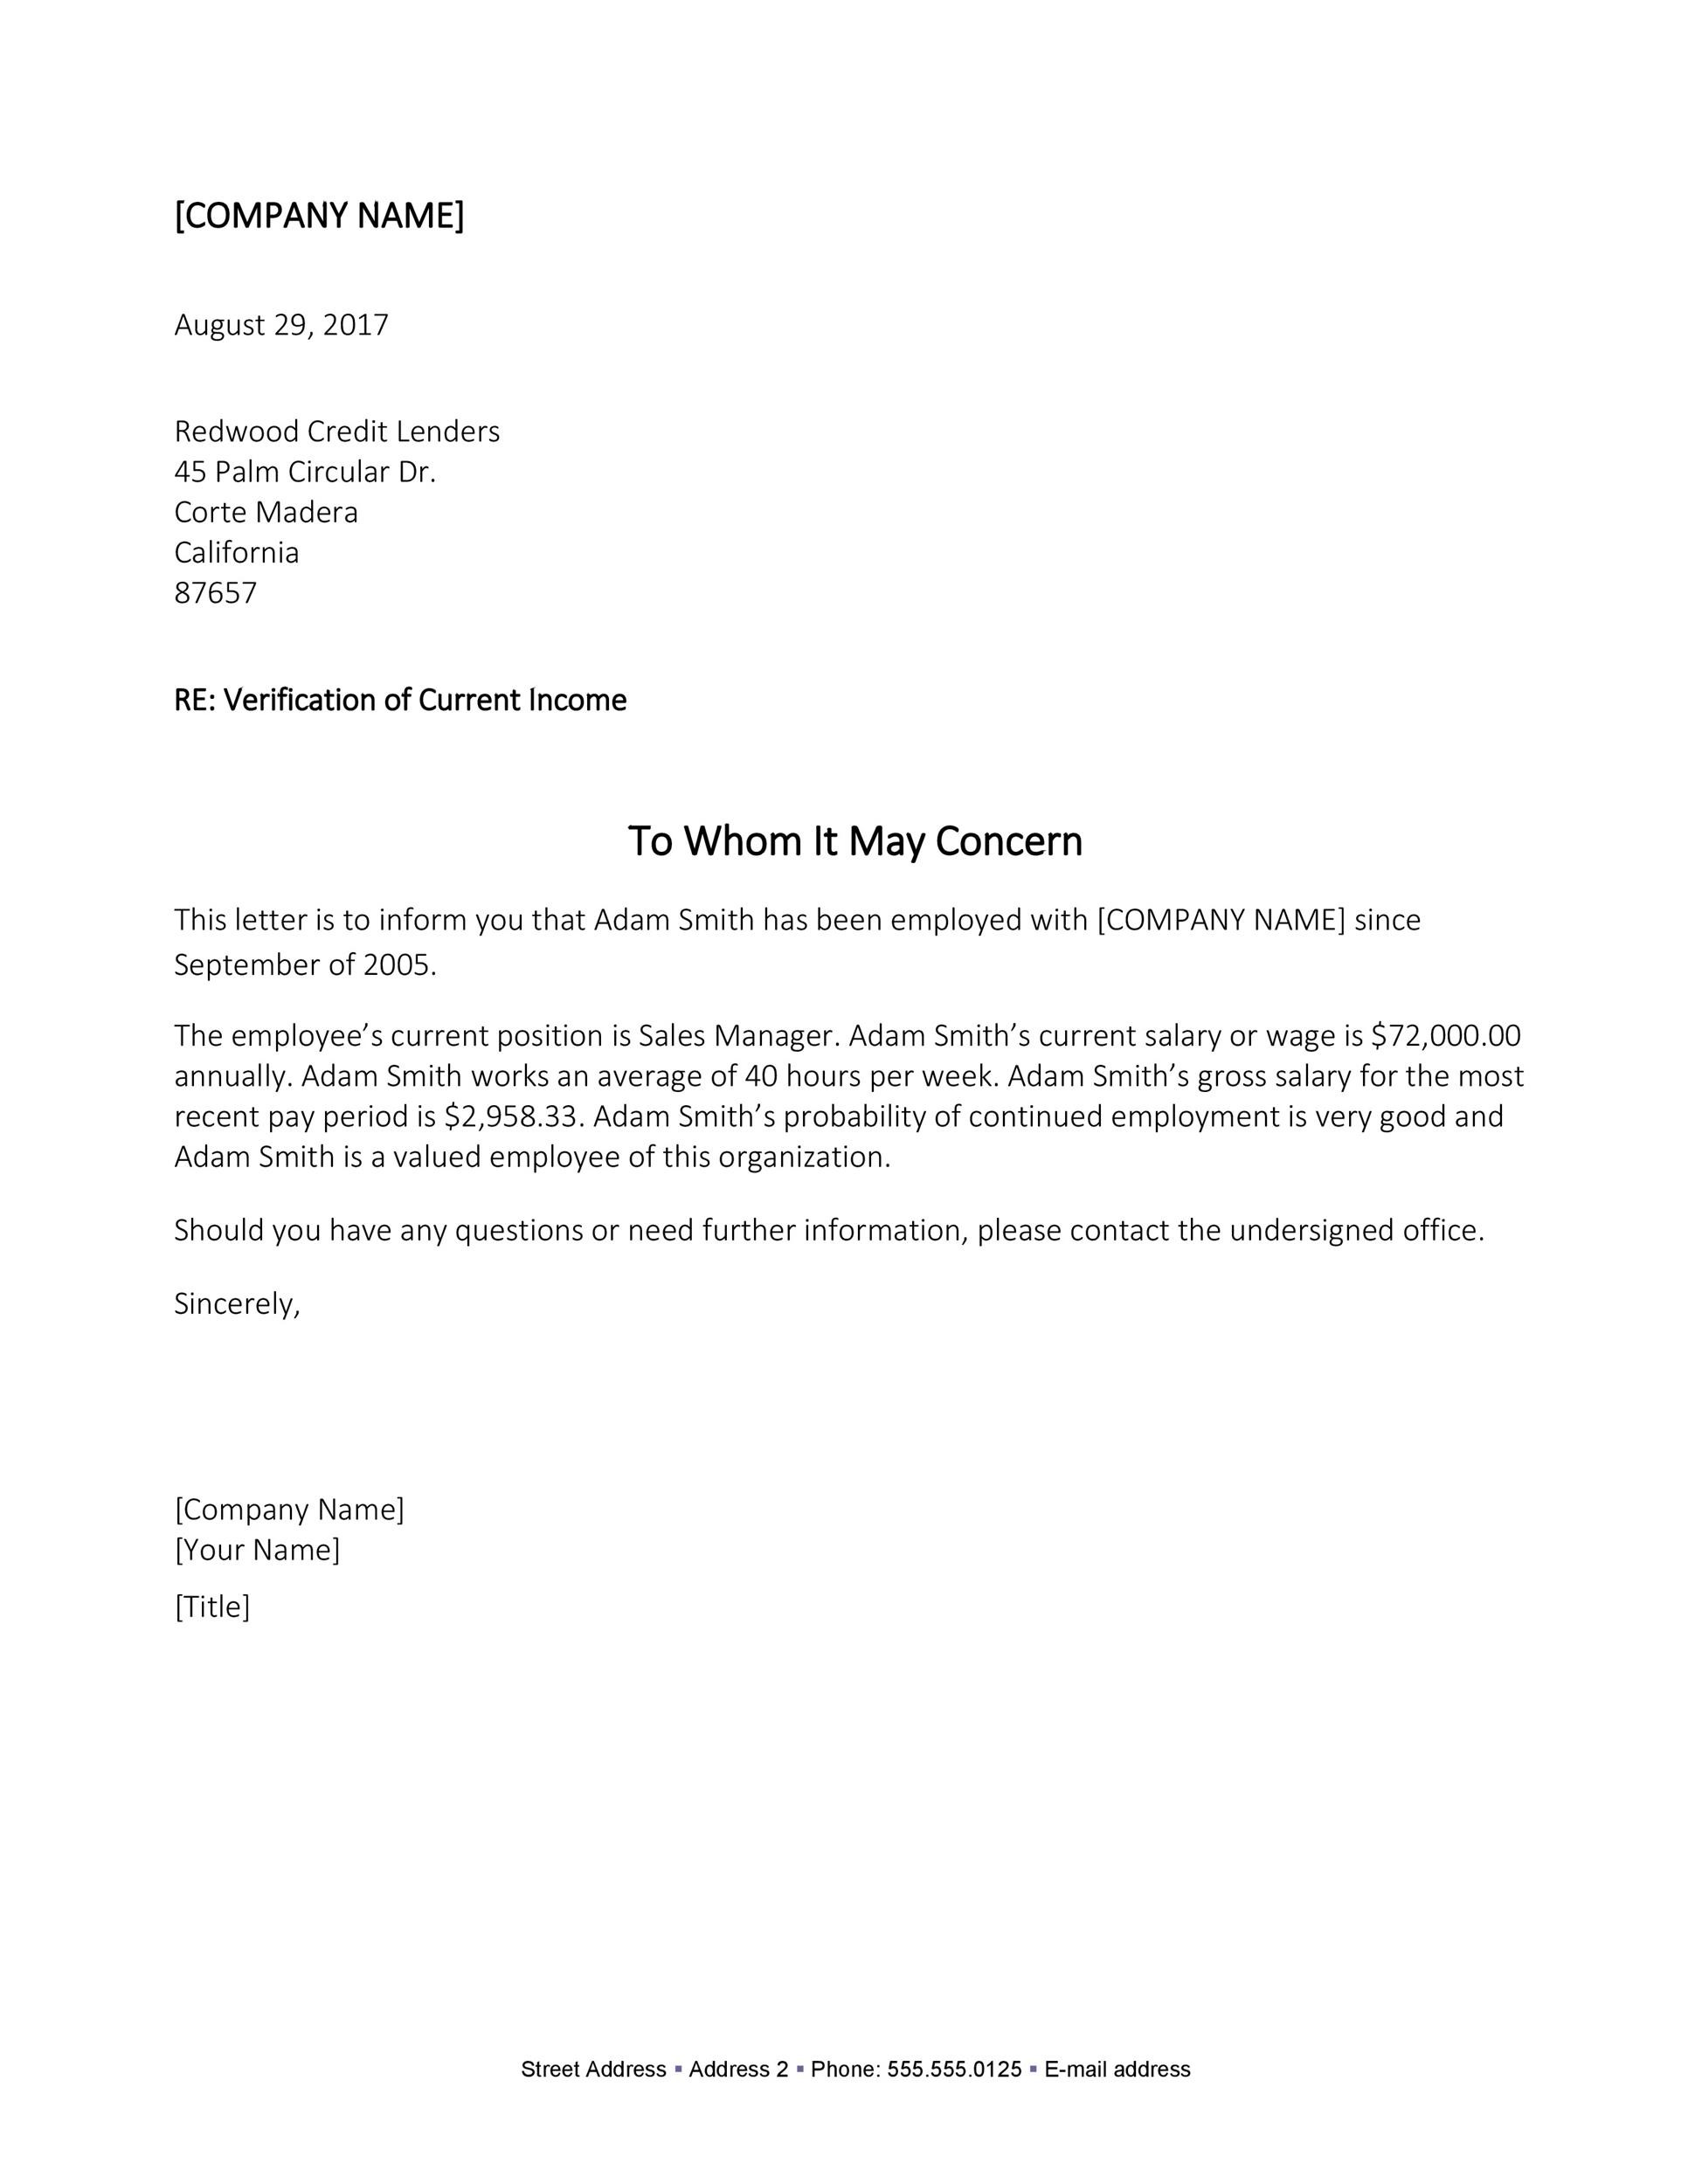
Your annual or monthly income, clearly stated A statement confirming that the information is accurate The signature of an authorized person, with their printed name and title
That last point is where most people mess up. A self-signed letter from your own employer carries very little weight with most institutions. The signatory needs to be someone who actually has the authority to verify employment — usually HR, a manager, or a certified accountant if you're self-employed. I ran into a case last year where someone submitted a proof of income letter from a small business owner who was the sole employee and had no HR department. The bank rejected it flat out because there was no independent verification. The workaround was to have the owner's CPA sign a letter on firm letterhead instead, which the bank accepted after some back-and-forth. That added about three business days to the timeline, which cost the client a potential closing window.
Self-Employed? This Is Where It Gets Messy
If you work for yourself, the standard employer-verified letter doesn't apply. Most institutions want to see tax returns, profit-and-loss statements, or bank statements covering the previous 12 to 24 months alongside your letter. A self-written proof of income letter is basically worthless on its own because you're verifying your own income, which defeats the purpose. The most reliable approach is to have your accountant prepare the letter on their professional letterhead. If you don't have one, a certified public accountant can draft and sign one based on your financial records. It's not free, usually running between $50 and $150 depending on the preparer, but it's what gets accepted without questions. Another option that works in some cases is using your most recent tax return as supporting documentation with a cover letter that states your income. This is acceptable for certain rental applications and smaller lenders, but major financial institutions tend to insist on third-party verification. Know your audience before you submit.

Common Mistakes That Cause Rejection
The biggest mistake is not asking the requesting party what format they require. Some organizations have their own specific templates. I've seen people send perfectly written letters only to be told they needed to use the landlord's form instead. Call ahead and ask. Another issue is using outdated income figures. If you got a raise six months ago, your pay stubs will reflect the new amount, but a letter based on old records won't match. Cross-check everything before submitting. Some people also forget that dates matter. A proof of income letter is only valid for a certain period — usually 30 to 90 days depending on the institution. If you're applying for something several months from now, don't request the letter too early. You'll just end up re-doing it.
Where to Find a Template
Government websites like the IRS and SBA offer basic templates you can adapt. Many law firms and accounting practices also publish free versions online. The template itself isn't the hard part — the accuracy of the information and the credibility of the signer are what actually determine whether it gets accepted. I keep a basic Word file with the standard structure that I pull up whenever someone asks me for help. It's not glamorous, but it cuts the time from idea to finished document down to about ten minutes if you have all the information on hand. If you're dealing with a particularly picky institution — banks during busy lending seasons, international visa applications, things like that — the single most useful thing you can do is ask for their specific requirements in writing. That saves you from going through the rejection and resubmission cycle, which typically adds one to two weeks to whatever process you're in.