What a Proof Of Income Letter Actually Looks Like
A proof of income letter is a straightforward document where an employer or other authorized party confirms how much someone earns. It's not fancy. It doesn't need to be. The person writing it states their name, title, the employee's name, the employee's start date, annual or monthly salary, and how the income is paid. That's it. Most people overcomplicate this because they're worried about legal liability or something, but the truth is whoever's requesting it just wants to verify earnings. A landlord needs it for an apartment application. A bank needs it for a loan. A government agency might need it for benefit verification. The format is simple enough that you shouldn't need a template, but most people prefer one anyway because it reduces the chance of forgetting something minor that still causes the whole thing to get rejected. Which happens more than you'd think.
Proof Of Income Letter Sample
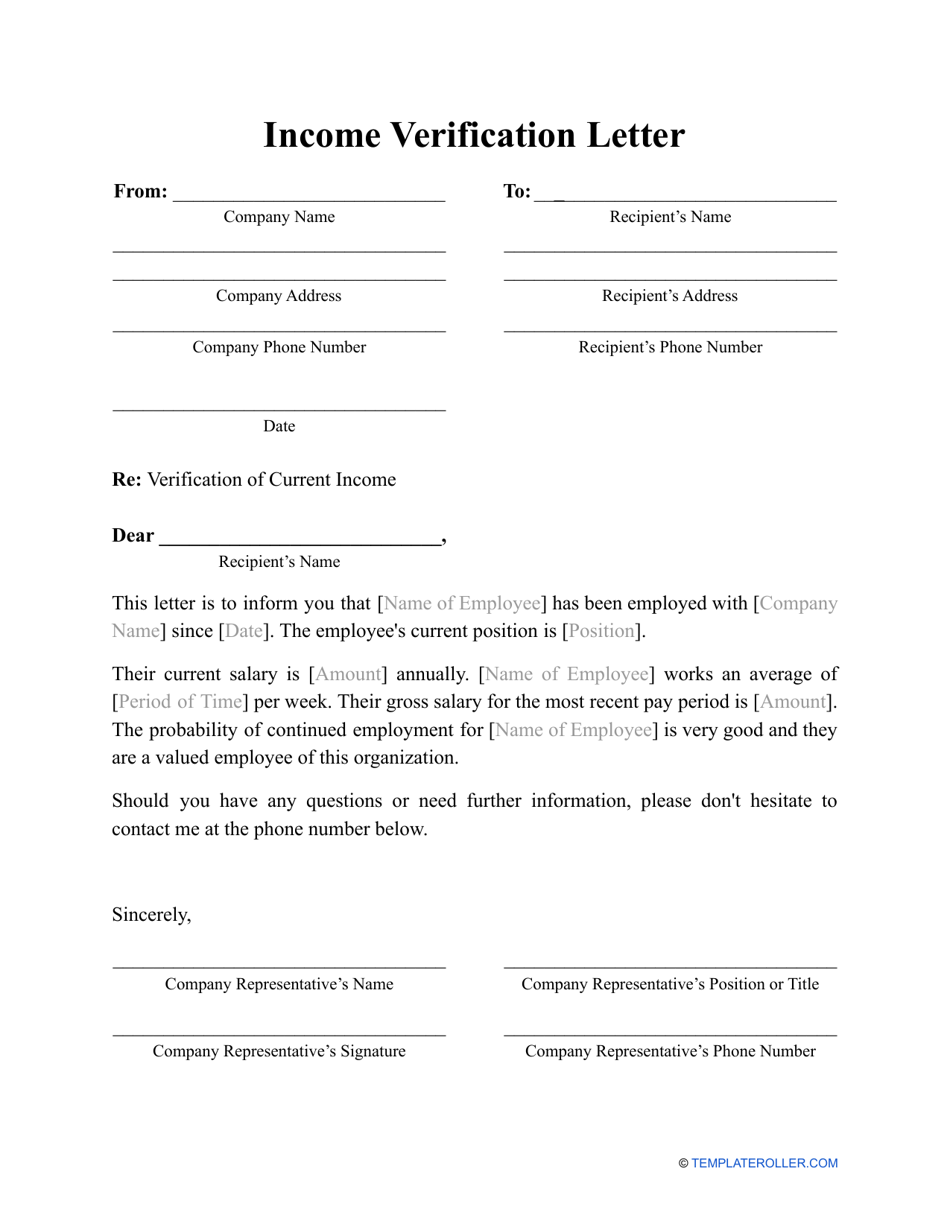
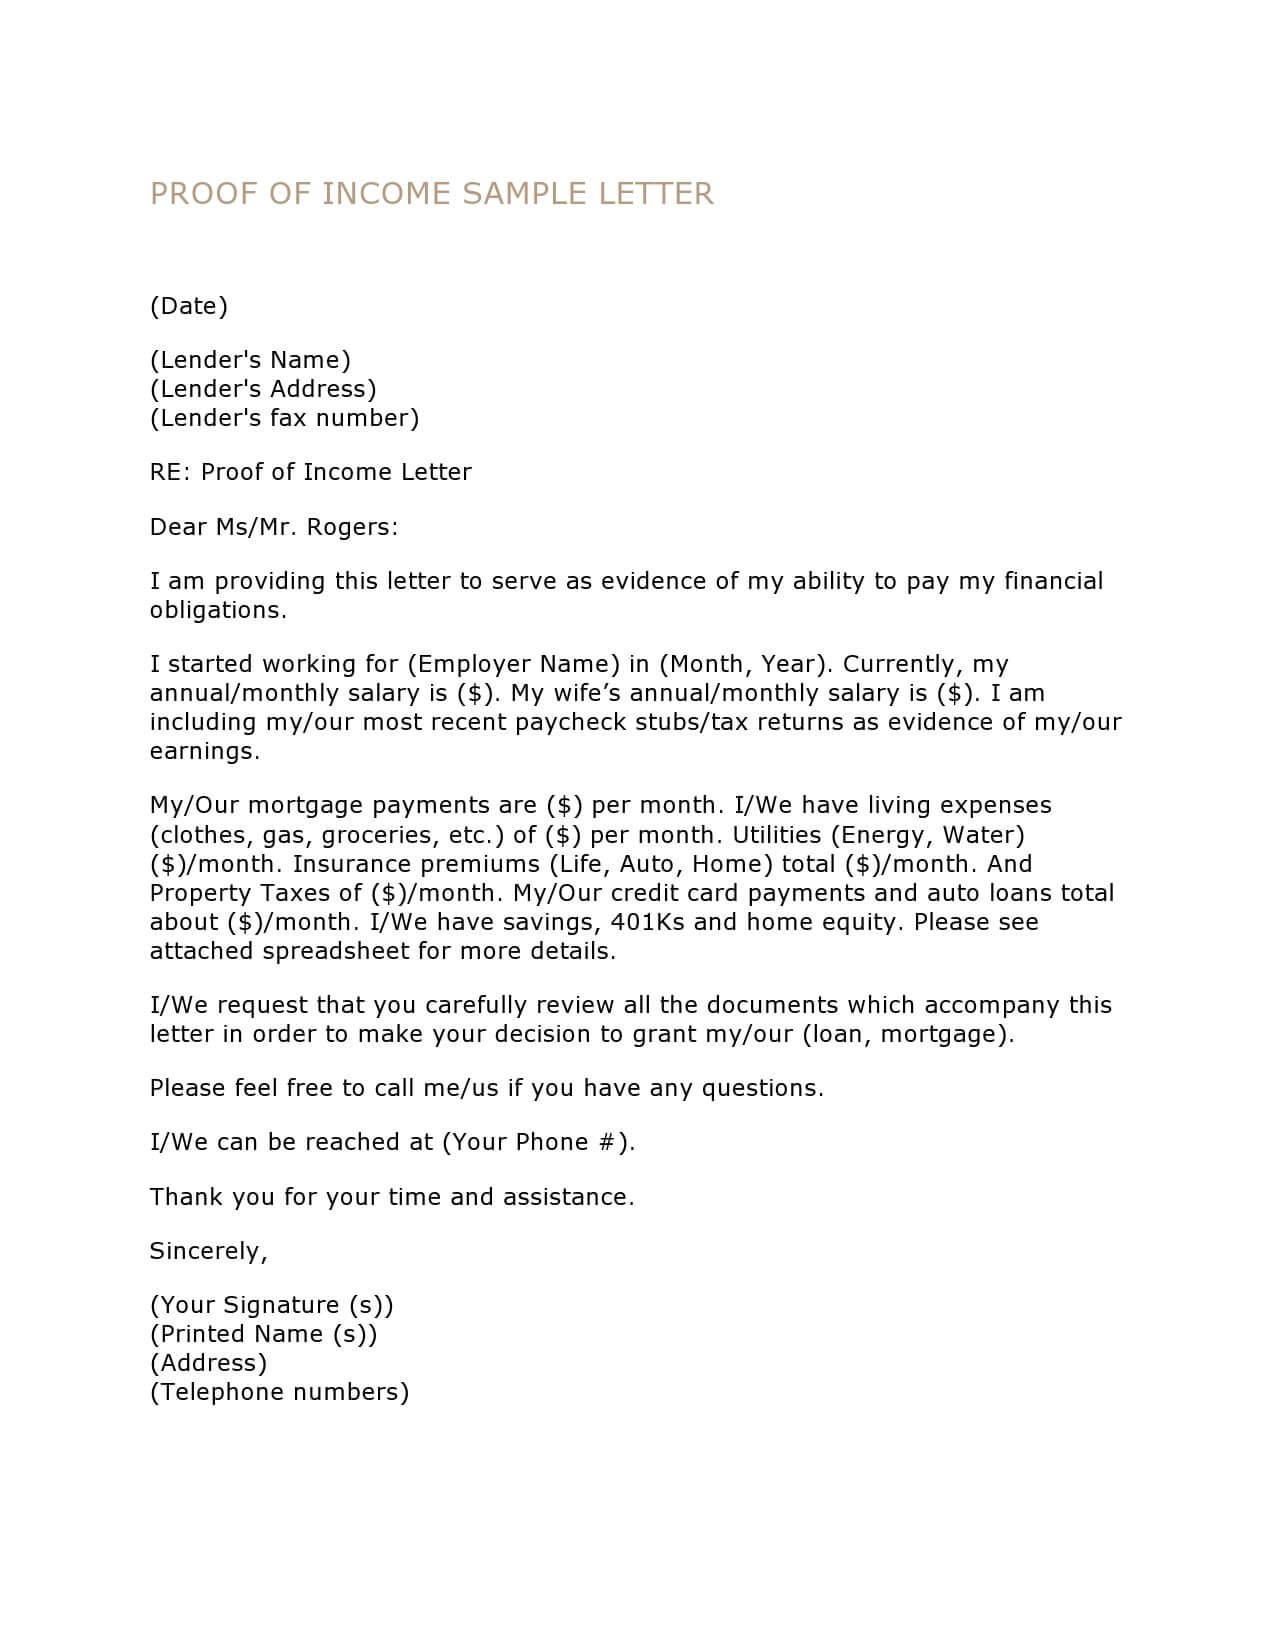
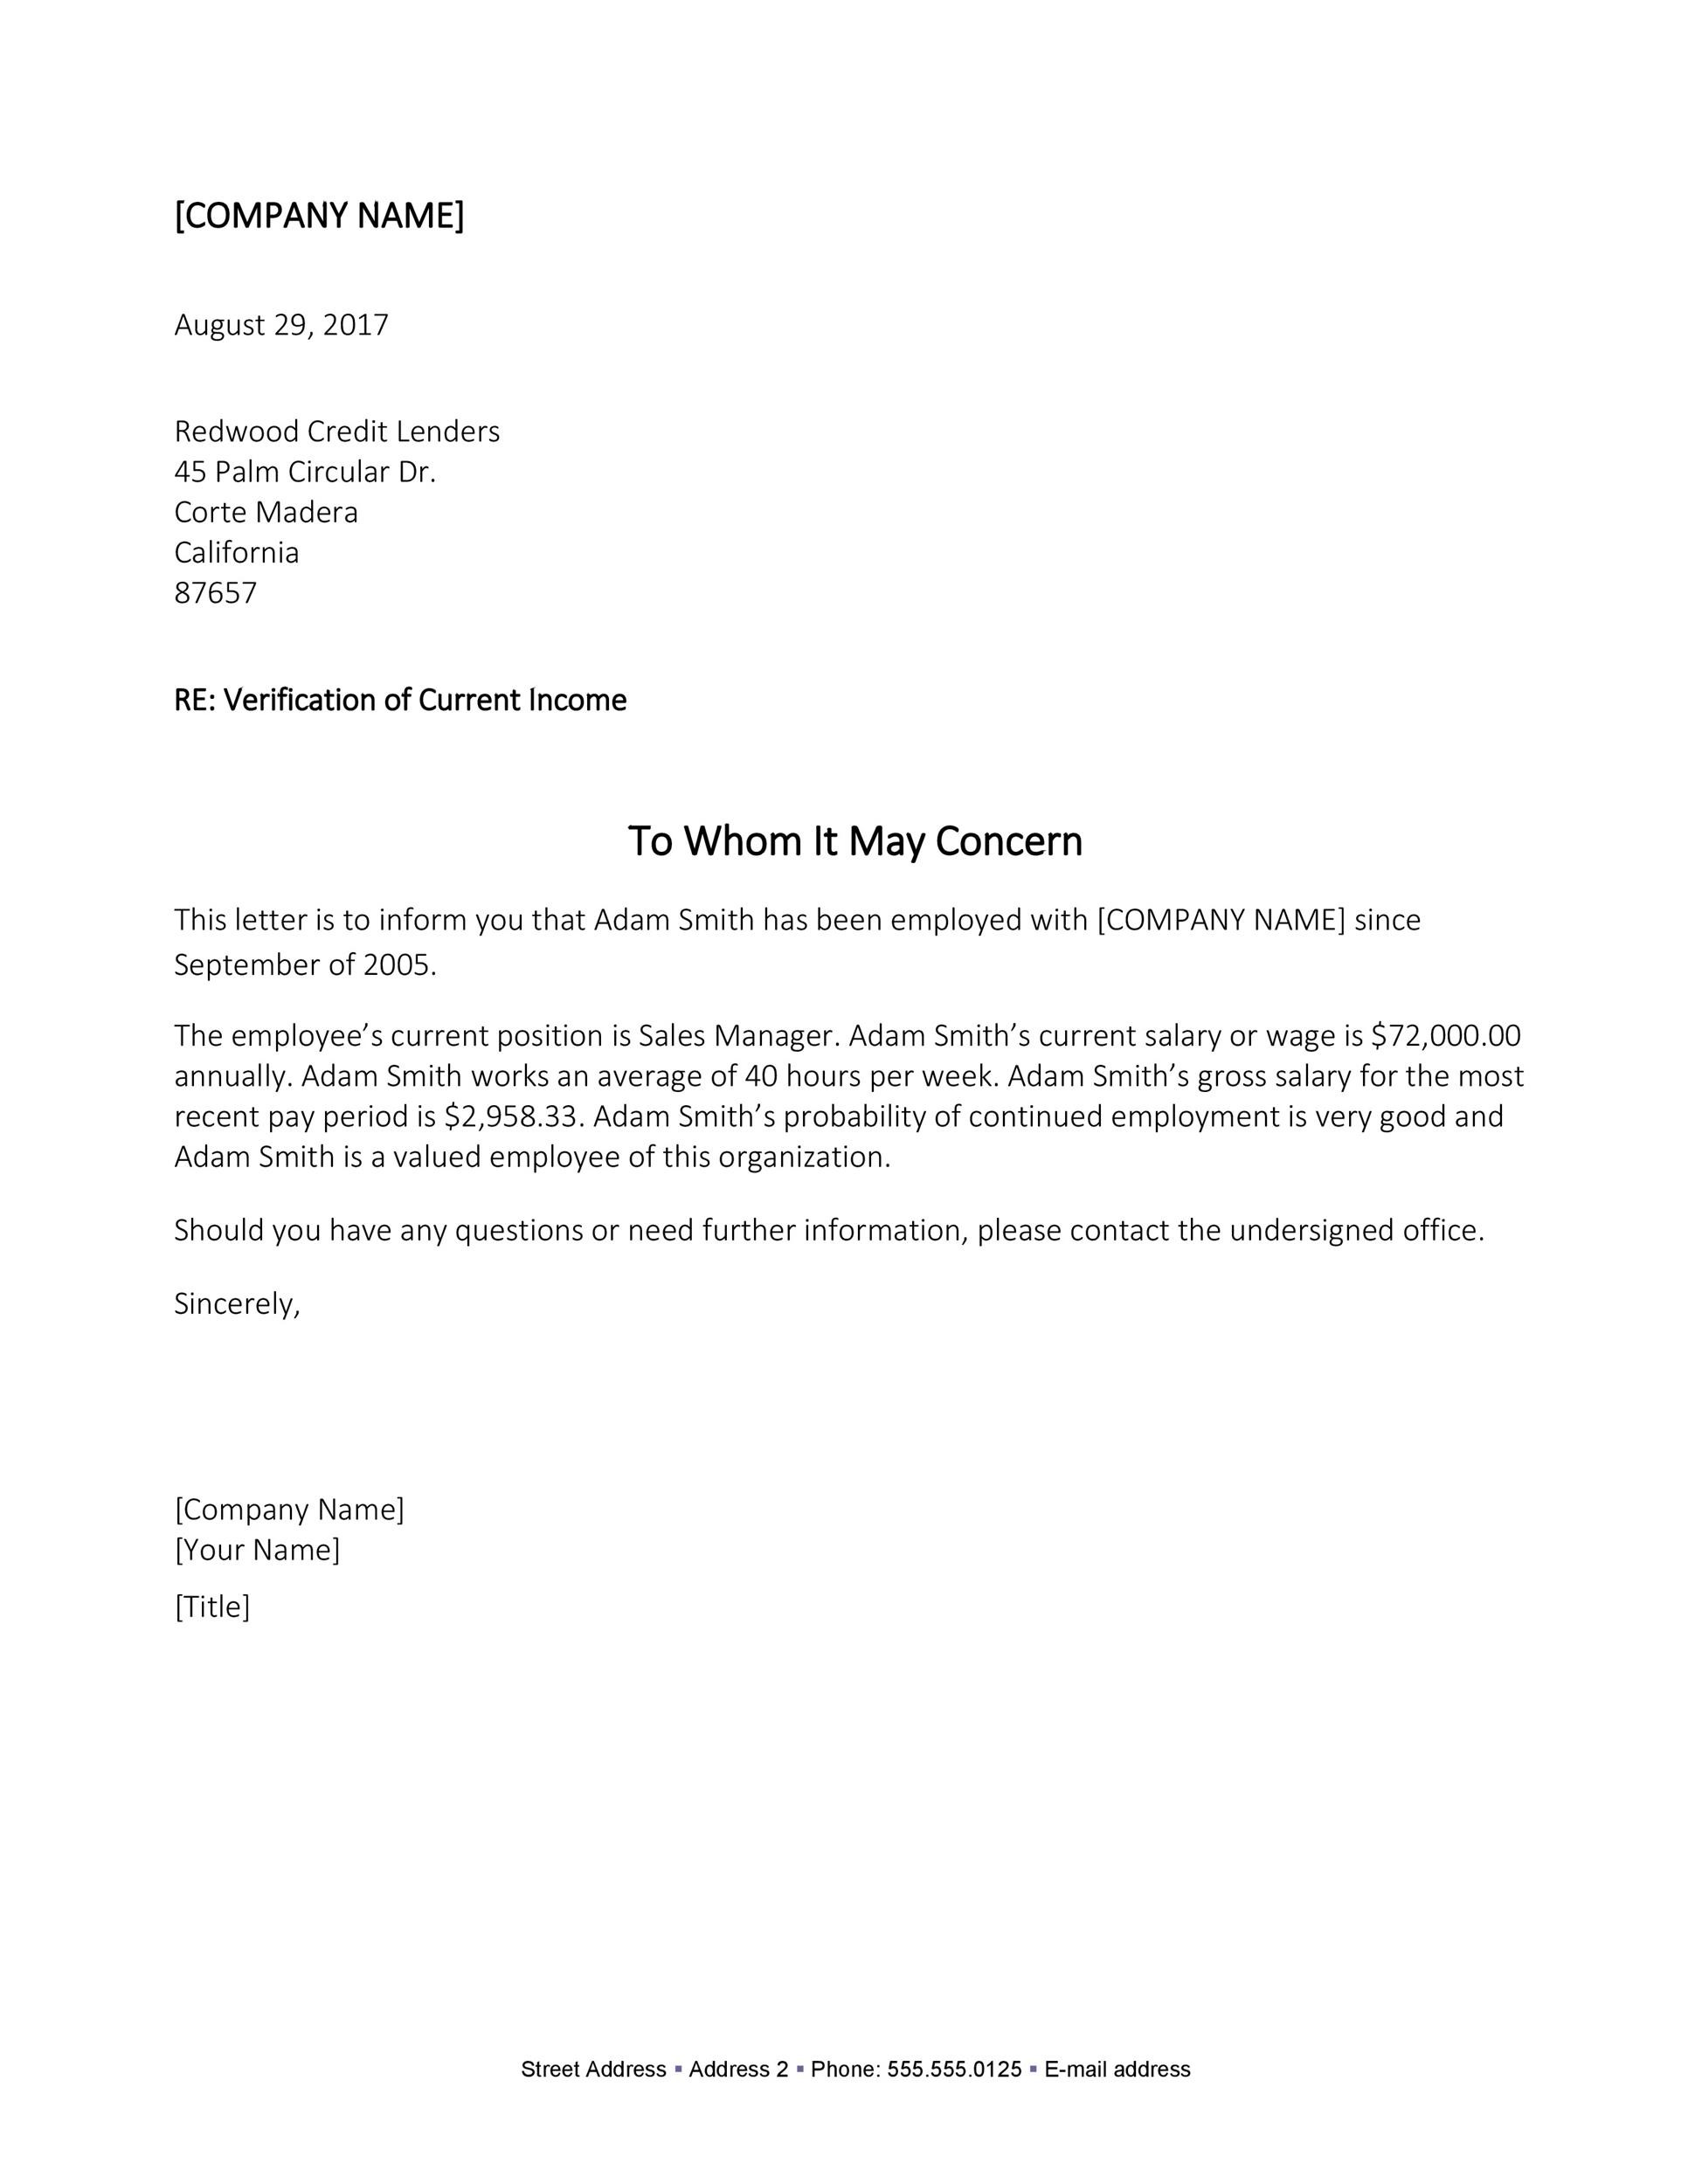
Here's what a working sample looks like in practice: [Company Letterhead] Date: [Month, Day, Year]
To Whom It May Concern, This letter confirms that [Employee Full Name] is currently employed with [Company Name] as a [Job Title]. [He/She/They] have been employed with us since [Start Date]. [Employee Full Name] earns an annual salary of [Salary Amount], paid [bi-weekly/monthly/semi-monthly]. This information is provided at the request of [Applicant Name] for the purpose of [rental application/loan application/verification purposes]. Please do not hesitate to contact me if you require any additional information. Sincerely,
Get the Full Details
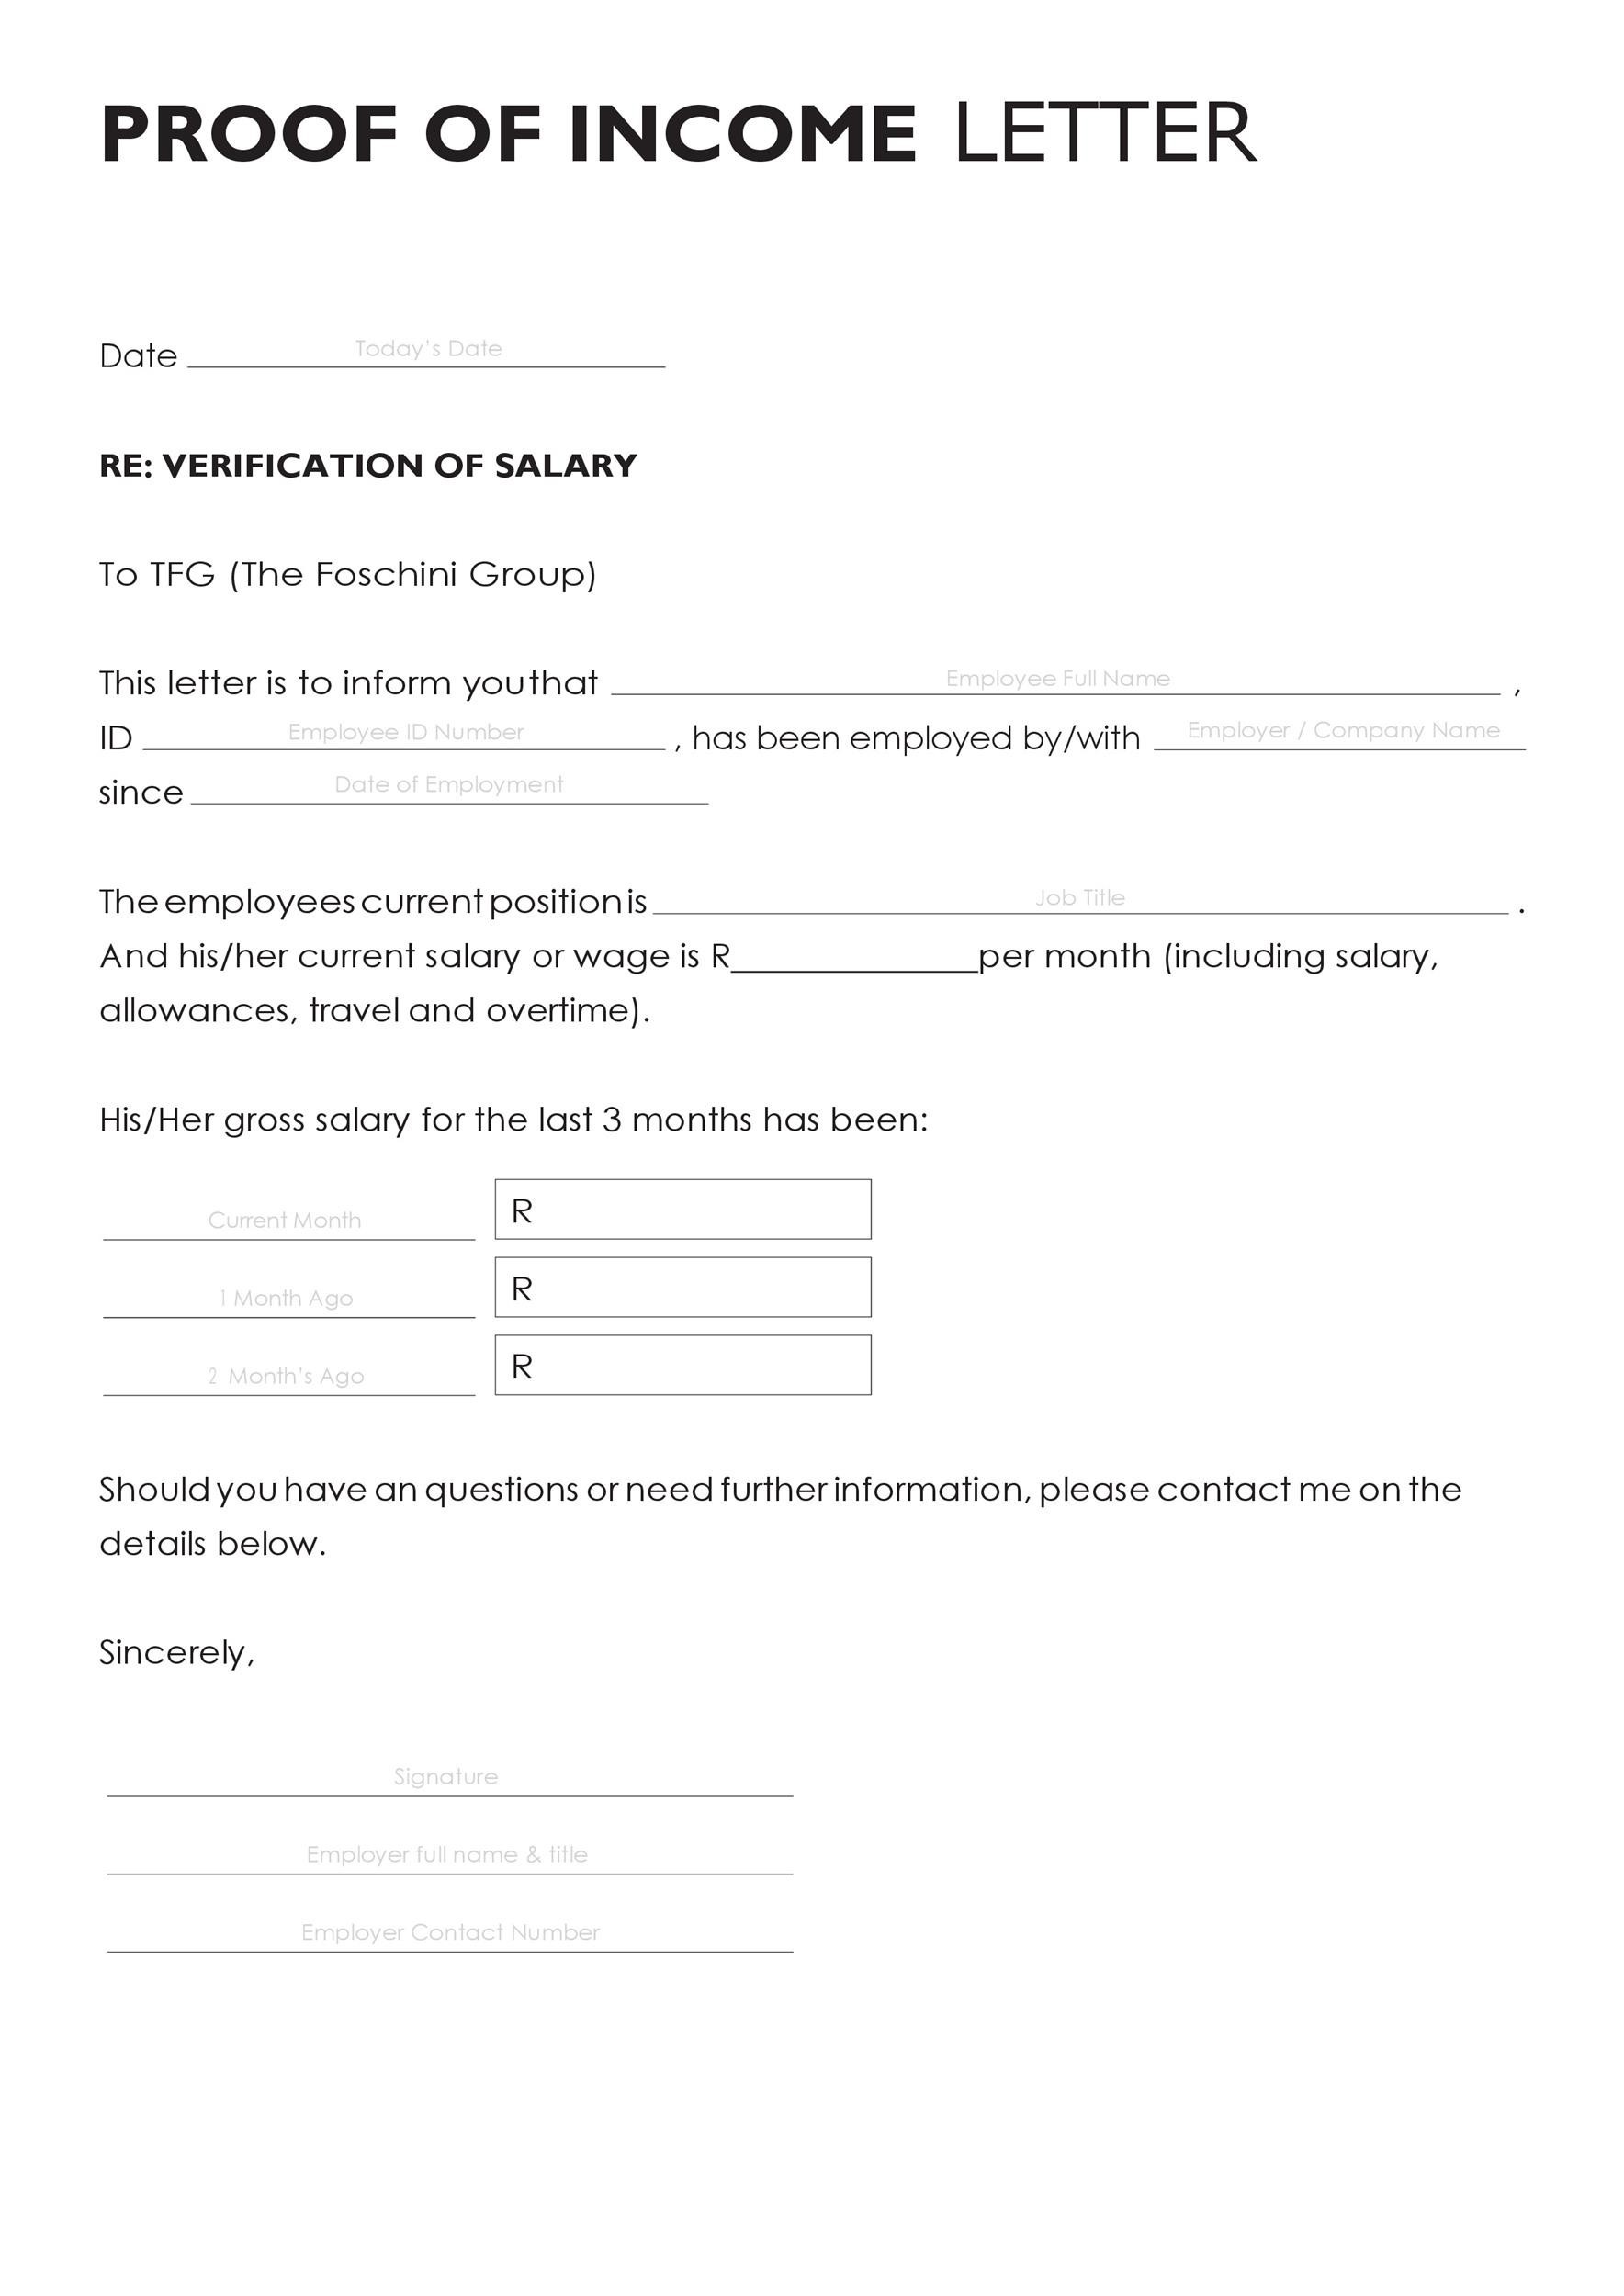
[Employer/Manager Name] [Job Title] [Company Name]
[Phone Number] [Email Address] The key thing most people miss is that the requesting party sometimes specifies the exact wording they need. I had a tenant once whose new management company sent a boilerplate rejection because the letter said "annual salary" instead of "gross monthly income." They literally asked for one metric and got the other. Two hours of back-and-forth with HR to get it reissued. Don't skip reading the request carefully before drafting anything.
Who Can Write One and When It Falls Apart
For employed people, the letter has to come from an authorized company representative — usually HR or a direct manager. Self-employed people write their own, sometimes with support from an accountant or CPA. That distinction matters because the receiving party treats them differently. A self-authored letter carries less weight on its own. If you're self-employed and applying for a mortgage, expect them to ask for tax returns anyway, and the letter becomes supplementary rather than primary documentation. Contractors and freelancers face a real gap here. There's no employer to sign off on anything. What most people end up doing is getting clients to confirm ongoing contract value, or using bank statements plus invoices as the actual proof. A letter on your own letterhead won't land well with a strict lender. Some credit unions are flexible about this, but traditional banks and mortgage lenders usually won't accept a self-written proof of income letter without the accompanying financial documents. Another thing people run into: the letter expires. Not officially, but practically. Most verifications are considered valid for 30 to 60 days from the date issued. If you draft a letter in January for a lease starting in March, nobody's going to accept it. The landlord will ask for a fresh one. I've seen this sink deals at the last minute because the applicant assumed the document was permanent. It isn't. It's a snapshot. Plan your timeline backwards from the actual submission date, not from when you first heard you'd need it.
Things That Get Letters Rejected
The letter needs to be on official company letterhead. A plain Word doc printed at home and signed in blue ink gets tossed more often than you'd expect. Letterhead can mean a header with the company logo, address, and contact info — it doesn't have to be fancy, just clearly official. If the company doesn't use letterhead, print it on plain paper and make sure the employer's contact information is complete and verifiable. The signature needs to be original, not a scanned image in most cases. Electronic signatures are increasingly accepted, but some landlords and older bureaucratic offices still insist on a wet ink signature. Call ahead if you're unsure. It saves a trip. The contact information listed has to be a real, working phone number or email. I've had to resend letters three times because the number on file was disconnected, and by that point the deadline had passed. Always verify the contact details before submitting.
A Quick Note on What This Document Can't Do
A proof of income letter only confirms what's written on it. It doesn't prove consistency, it doesn't prove future income, and it doesn't cover bonuses or commissions unless those are explicitly stated. If your base salary is fine but your actual take-home fluctuates heavily with commissions, a flat salary figure might look good on paper and still get flagged during underwriting because the lender wants to see average earnings over the last two years. In those situations, pay stubs and W-2s do more heavy lifting than the letter ever will. The letter is one piece of a verification package, not a standalone credential. Treat it like a supporting document and you'll avoid most headaches.