What a Proof of Income Letter Actually Is
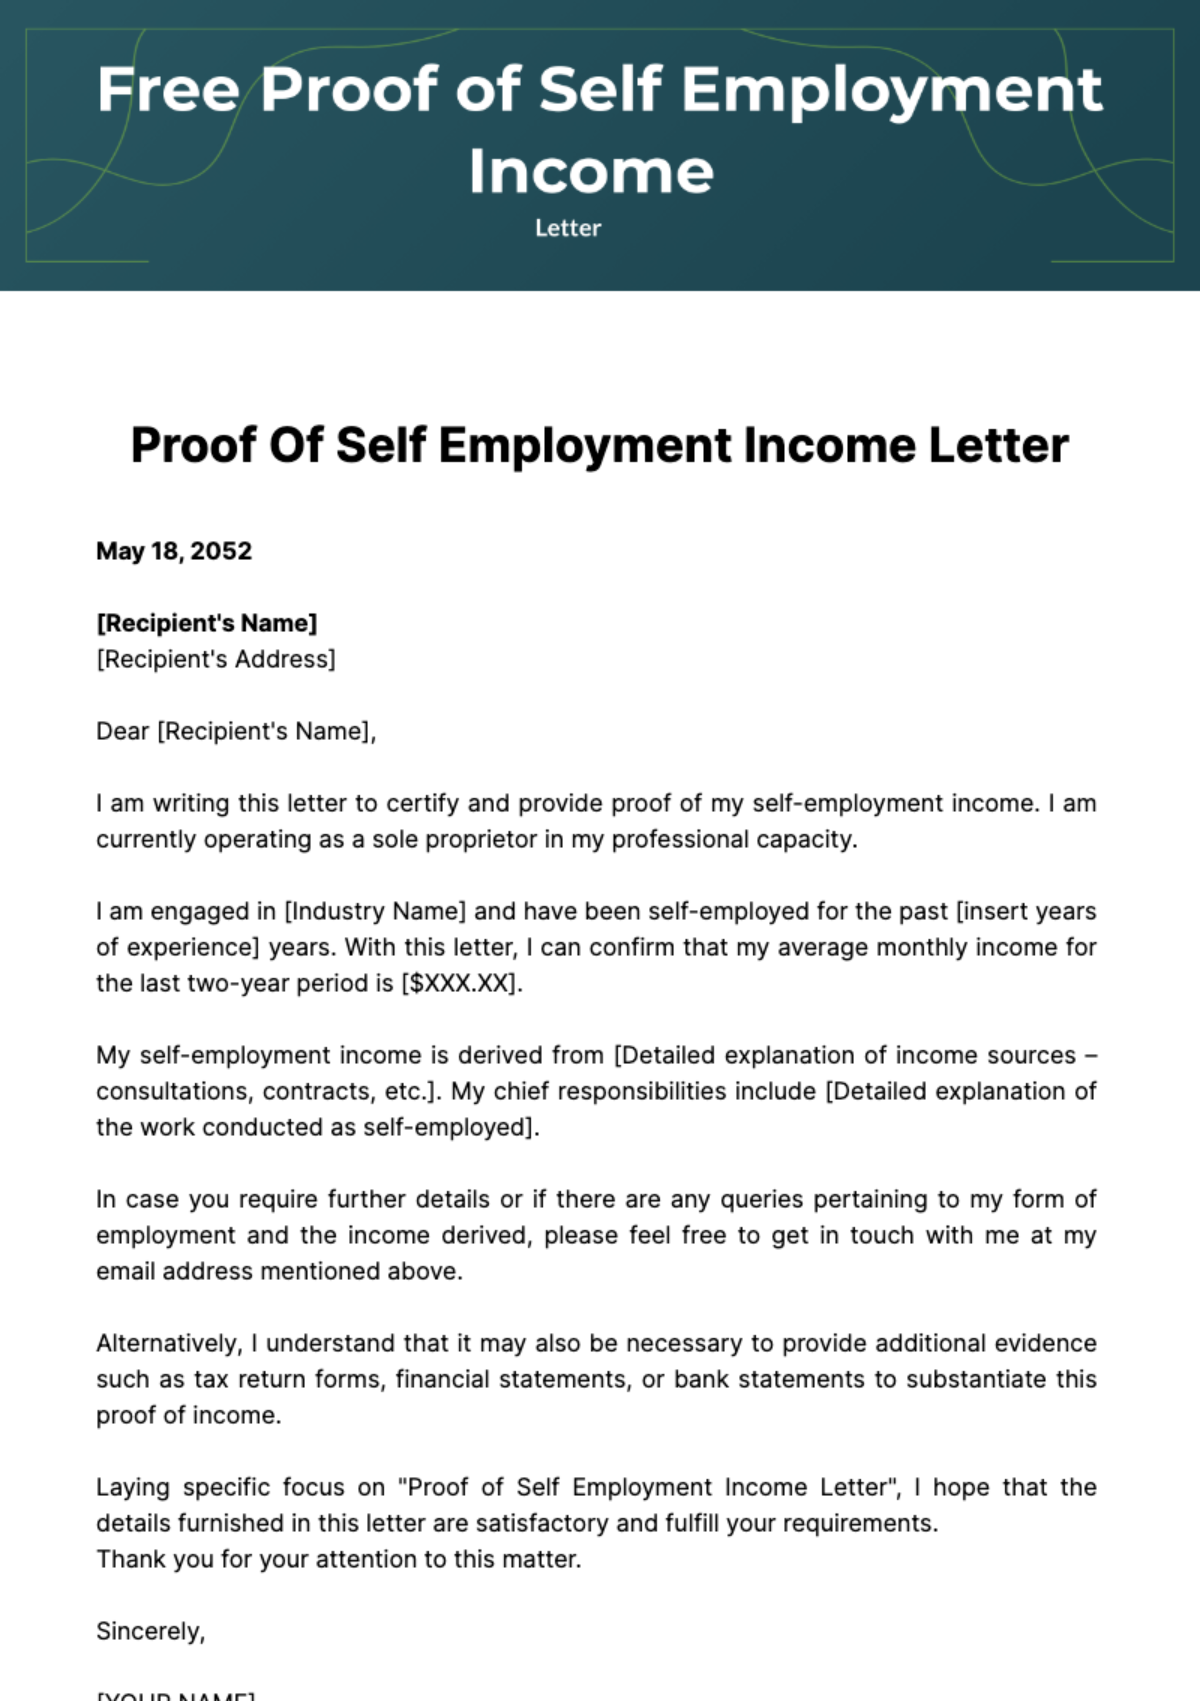
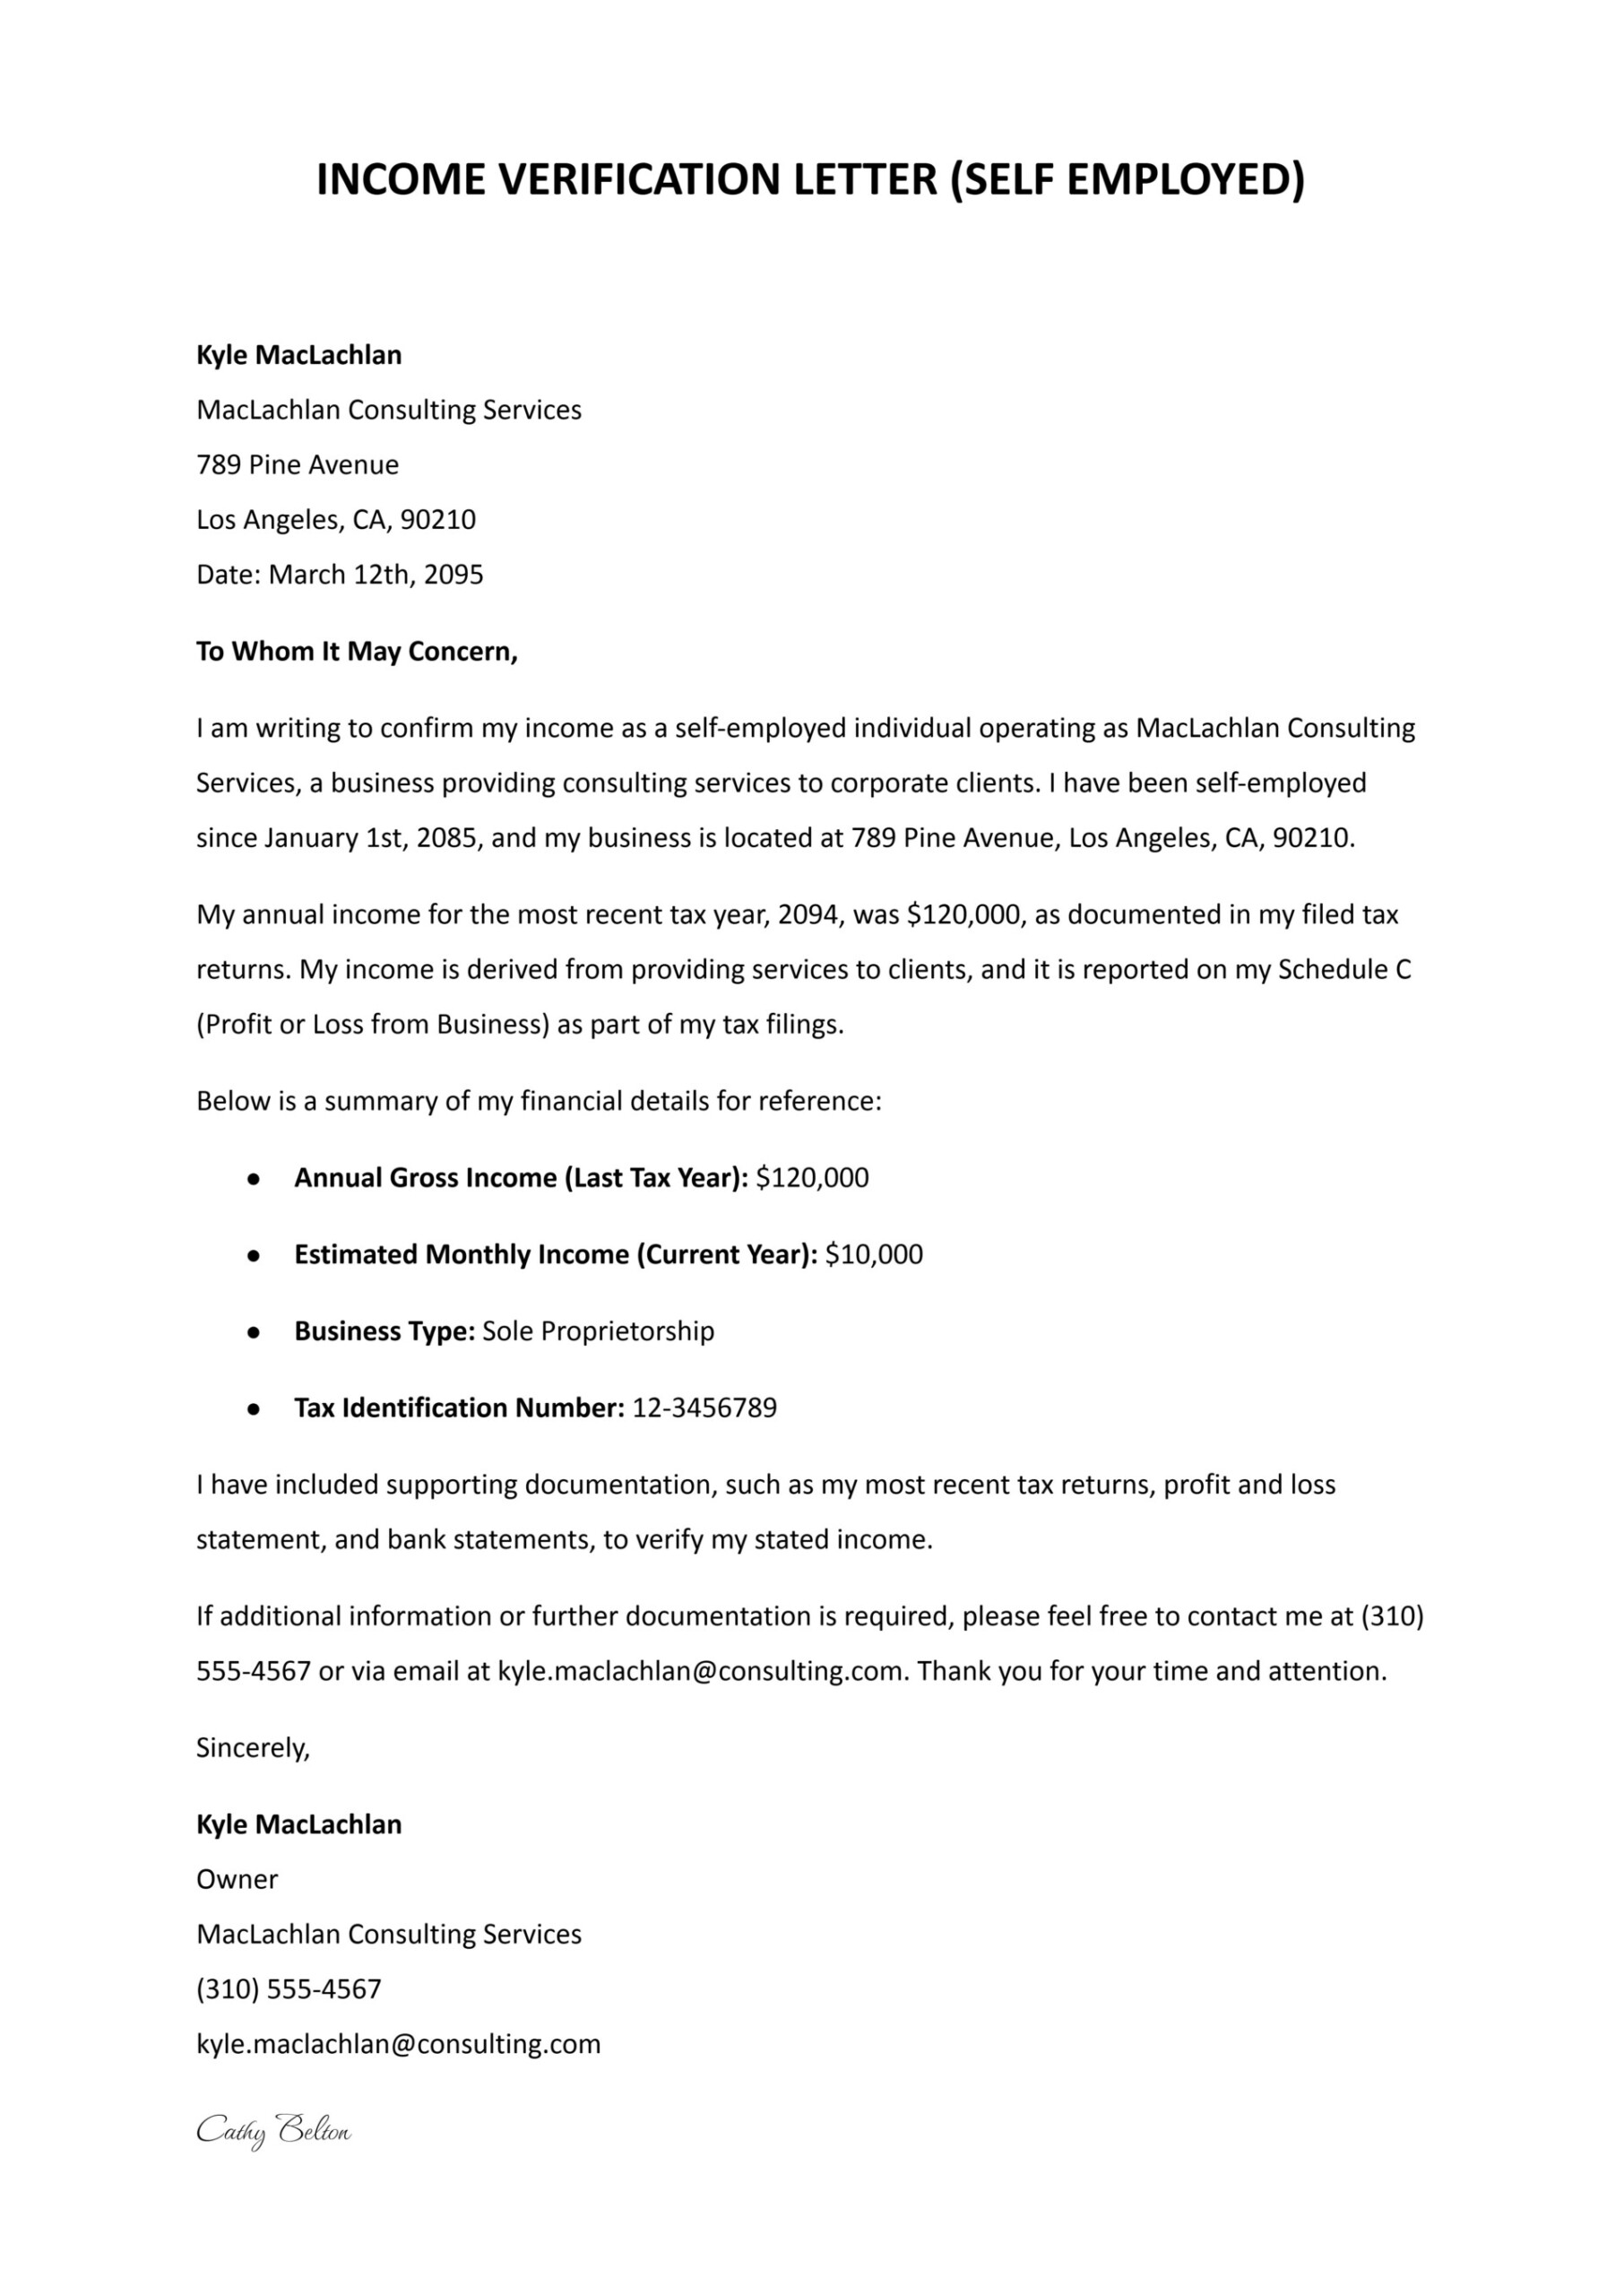
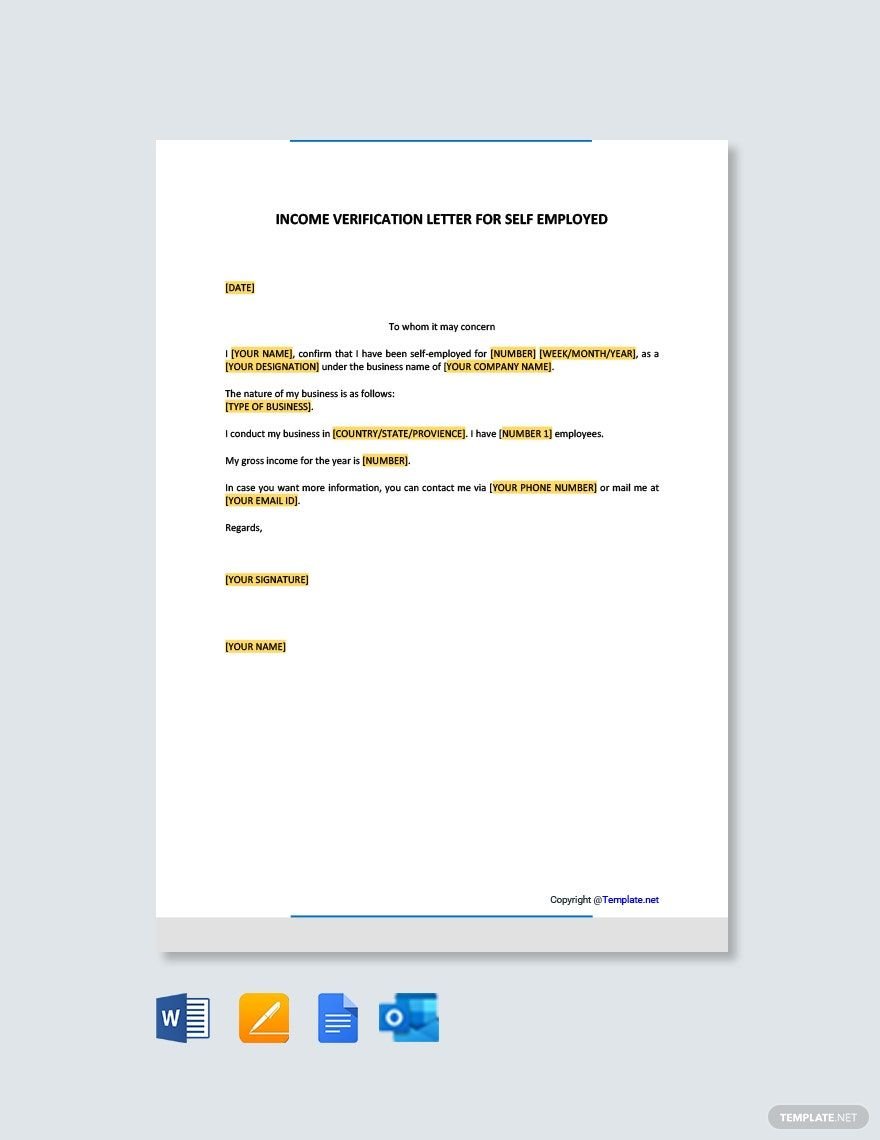
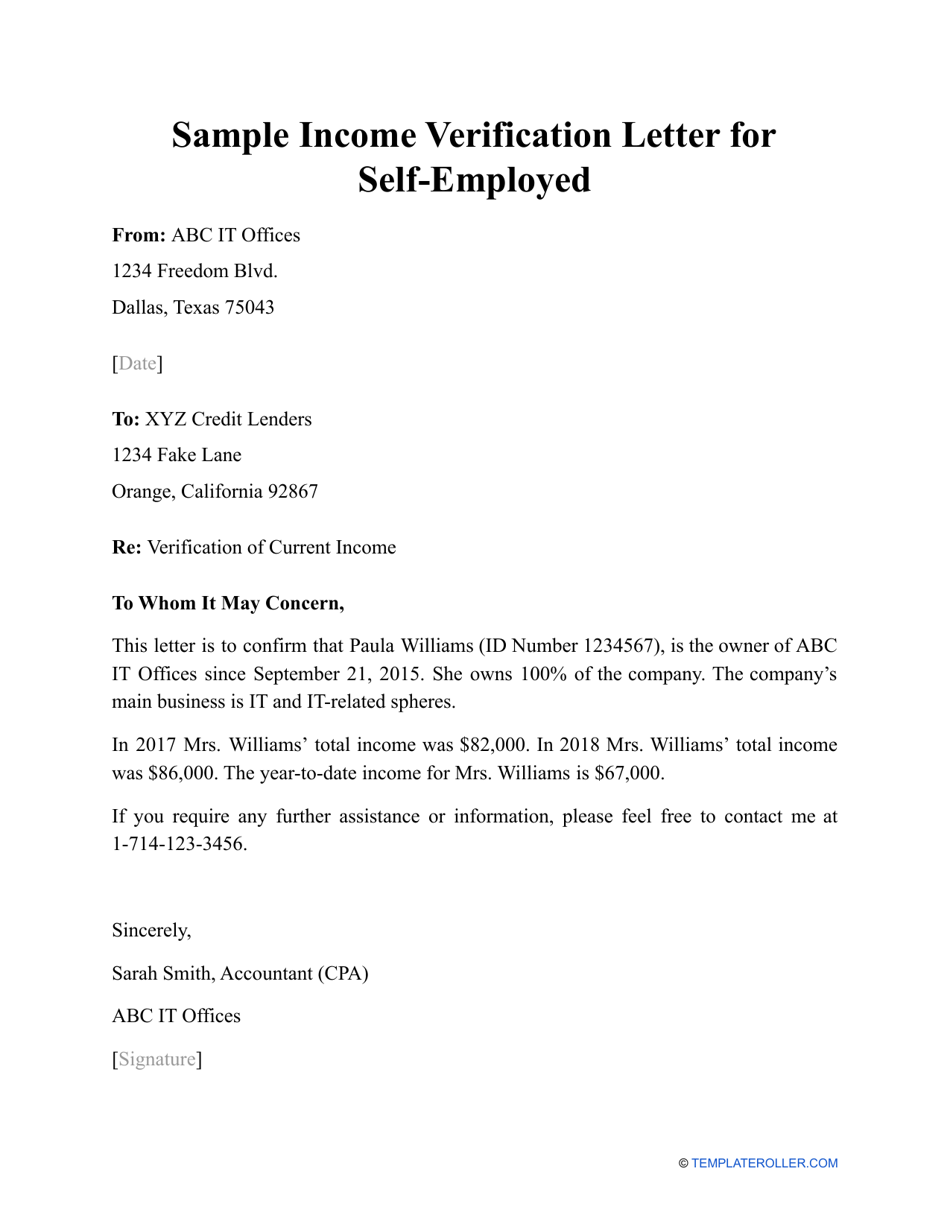
A proof of income letter for self-employed people is a document you write yourself that states your earnings over a specific period. Banks, landlords, visa officers, and some government agencies request these when they can't pull a traditional pay stub or W-2 from an employer. The burden of verification shifts entirely to you, which means the letter has to carry enough weight on its own. That's the whole problem, really.Most people assume they just need to say "I make $65,000 a year" and sign their name. That's why half of these letters get rejected. The reader needs context, not just a number. Your letter should establish who you are, what you do, how you measure your income, and where that income comes from. It should also point the reader toward verifiable documentation they can check independently. The letter itself is usually one page. You state your full legal name, your business name and structure (sole proprietorship, LLC, S-corp, etc.), your business address, and your contact information. Then you specify the time period the income covers. Next comes the income figure or range, broken down clearly. If your income fluctuates month to month, you show an average or a year-to-date total. You note how you calculate it, reference supporting documents, and close with a signature and date. Keep it factual and restrained. Here's a plain template you can adapt. I keep a saved version on my desktop because I write these at least once a month and copy-pasting saves about ten minutes each time:
[Your Full Name][Business Name]
[Business Address]
[Phone Number]
[Email Address]
Date: [Date]
To Whom It May Concern,
I am writing to verify my income as a self-employed individual. I operate [Business Name], a [business structure] engaged in [brief description of business activity]. I have been self-employed since [Year].
For the period [Start Date] through [End Date], my gross income was $[Amount]. This figure is derived from my [tax returns / monthly invoices / accounting records] and is consistent with the documentation attached.
Attached to this letter, please find the following supporting documents:
- Federal tax return (Schedule C) for [Year]
- [Year]-to-date profit and loss statement
- Recent bank statements showing income deposits
- [Any other relevant documents]
Please do not hesitate to contact me at [phone] or [email] if you require additional information.
[Signature]
[Typed Name]
[Title, if applicable]
I know this looks generic. That's the point. These letters aren't supposed to be creative. They're supposed to be audit-resistant. The more specifically you can tie your stated income to third-party documents, the faster the letter gets accepted. The number one reason I see for rejection is vague income presentation. A self-employed person writes "my average monthly income is approximately $5,000" without explaining how they arrived at that number. The bank officer reading it has no way to verify it. They'll ask for tax returns anyway, and now you've lost credibility before the conversation even starts. A second common failure is mismatched time periods. You state income for January through June but attach a full-year tax return. The reader has to reconcile the discrepancy themselves, and most won't bother. They'll just flag it. Match the periods exactly. If you can't because your records don't cover that span, say so and explain what you do have.
A third issue is self-employed people writing these letters on personal letterhead or plain paper without any indication of a business. It doesn't have to be fancy. But a simple header with your business name and basic contact info makes the document look like it came from an operating business rather than a Google Docs draft. That difference matters more than you'd think to someone reviewing dozens of applications a day.
Get the Full Details

My Own Experience With a Tough Case
Last year I needed a proof of income letter for a commercial lease application. I'm a sole proprietor doing consulting work, and my income in the prior fiscal year was actually lower than the year before because I took on a smaller project load while starting a new client relationship. The landlord's property management company required proof of at least $75,000 in annual income. My most recent full-year tax return showed $62,000. The obvious move would have been to pad the number or selectively cite months. I didn't do that. Instead, I wrote the letter using year-to-date income plus signed engagement letters from three active clients that would generate an estimated $84,000 for the current fiscal year. I attached the YTD profit and loss statement from my accounting software, the signed client agreements, and the prior year tax return for transparency. I also included a brief paragraph explaining the seasonal nature of my work and why the prior year was an outlier. The property manager accepted it on the second submission after asking for the client agreements, which I provided within an hour. The key move was showing forward-looking income with documentation rather than hiding behind the prior year. A lot of self-employed people don't realize you can use future contracts as supporting evidence when current income looks thin. Just make sure those contracts are real and signed. Fabricated agreements are the fastest way to get yourself blacklisted by a management company.
What You Should Attach
The letter alone is rarely enough. Build a package. The standard attachments are your most recent federal tax return with Schedule C, a year-to-date profit and loss statement from your accounting system, and three to six months of bank statements showing the deposits that correspond to your income. If you work with invoices, include copies of your most recent ones. If you have business licenses or professional certifications, toss those in too. It signals that you run a documented operation. If you use QuickBooks, FreshBooks, or Xero, export your P&L as a PDF directly from the software. Do not screenshot it or recreate it in Excel. Automated exports carry more weight because they show an auditable trail. I've had landlords reject handwritten spreadsheets before accepting the same numbers in a software export. It's not fair. It's just how it is.
When This Approach Falls Apart
Proof of income letters work well for standard applications: apartment rentals, personal loans, car leases, tourist visas. They break down when the requesting party has strict income thresholds that your variable revenue doesn't reliably meet. If you're a gig worker with income that swings between $3,000 and $12,000 per month, a single letter won't smooth out that volatility for a lender underwriting a 30-year mortgage. In those cases, the better path is to build a two-year income history on your tax returns and let the averages speak for themselves. A proof of income letter is a supplementary tool, not a replacement for consistent documentation over multiple years. If your income has been declining for two straight years, no letter is going to convince a qualified lender otherwise. You'd be better off securing a co-signer or waiting until your revenue stabilizes before applying.
Quick Practical Notes
Use your actual business email address if you have one. It adds a layer of verification that a Gmail or Yahoo address doesn't. Keep the tone professional and avoid phrases like "I work really hard" or "I'm very good at what I do." Nobody asks for a character reference here. State the income, point to the evidence, offer to provide more. That's the entire job of the letter. If you're sending this electronically, PDF is the standard. Print it on plain paper if mailing. Sign it with a pen and scan the signature. Electronically typed names get flagged more often than you'd expect by automated screening systems used by larger institutions. I save a master document with my business details pre-filled so I only have to update the income figures and date range for each new request. It reduces a fresh draft from about twenty minutes down to roughly five. Five minutes is all you should need if your information is organized.