Most people approach the P&C licensing exam wrong
I spent five years training adjusters and agents before I realized the actual problem wasn't studying more — it was studying the wrong things. The exam covers a massive amount of material: insurance contracts, general principles, property coverages, commercial lines, surety, garages, vehicles, liability, and much more. Going through 600 pages of a textbook cover to cover will waste roughly three to four days of your time with very little return. A focused Property And Casualty Insurance Exam Cheat Sheet approach gets you to the same point in about twelve hours. Here is how I actually build and use one. Not the version sold on random websites. The version I tell new producers to construct for themselves.
What a Property And Casualty Insurance Exam Cheat Sheet Actually Is
It is not a list of answers you memorize. It is a condensed reference document that maps the exam's most tested concepts to their simplest form so you can retrieve them quickly under time pressure. A real cheat sheet is one to three pages maximum, written by you, organized by topic, and packed with definitions, formula shorthand, coverage limits, exclusions, and deductible structures that show up repeatedly across every state exam. The reason this works is simple. The P&C exam tests recognition more than deep analysis. You are rarely asked to derive something from scratch. You are asked to identify which coverage applies, which exclusion voids a claim, or what the correct premium calculation is given a set of parameters. A well-built cheat sheet preloads those recognitions so you are not reconstructing knowledge from memory during the test. I built my first real one in 2014 while prepping for the Florida license exam. I had failed the first attempt because I kept second-guessing myself on HO-3 vs HO-5 distinctions. I ended up writing out a side-by-side comparison of all homeowners forms, the causes of loss, the named perils vs open perils structure, and the standard deduction and coinsurance formulas that show up on almost every question. That single page cut my review time from three days down to four hours. I passed on the retake.
How to Build One That Actually Works
Step one is getting the exam content outline from your state's department of insurance website. Every state publishes it. It tells you the exact weight of each topic area. If you skip this step, you are guessing about what to prioritize. Do not skip it. California weights liability differently than Texas. New York has its own no-fault structure questions. The outline is your map. Step two is reading through your textbook or online course material once, slowly, and pulling out every definition, form number, coverage type, and formula that appears in bold or is repeated across chapters. I use a highlighter and a separate notebook. I do not organize anything yet. I just pull. Step three is organization. Group everything by major category: insurance principles, property coverages, liability coverages, commercial lines, surety, and miscellaneous. Within each category, order by frequency of exam appearance. Put the high-yield topics first. Coinsurance, valuations, causes of loss forms, and the ISO forms portfolio always come up. Deductibles and premium calculations are near-universal. Build your cheat sheet in that priority order so you review the important stuff first.
Get the Full Details
Step four is writing. Keep each entry to one line. If you need more than one line to explain a concept, you are overcomplicating it for exam purposes. Use abbreviations. Use arrows. Use tables where they make sense. A table comparing HO-1, HO-2, HO-3, HO-4, HO-5, and HO-8 side by side is worth a dozen paragraphs of bullet points. I do the same thing for auto coverages: liability, medical payments, collision, comprehensive, uninsured motorist, and hit-and-run. One table per major section. That is how you fit it all on two pages. I ran into a specific problem once that nobody warns you about. The exam sometimes asks questions using state-specific statutory language rather than the ISO standard forms. For example, the standard ISO fire policy says the insurer must pay within sixty days after receiving an authenticated proof of loss. But some states modify that timeframe in their statute. If your cheat sheet only lists the ISO standard, you will get tripped up on that question. The workaround is simple: add a small section at the back of your cheat sheet called state-specific modifications and fill it with whatever your state's DOI publishes about policy period changes, grace period adjustments, and valuation method overrides. Ten minutes of research saves you from guessing on three to five questions.
Formulas and Calculations That Appear Every Time
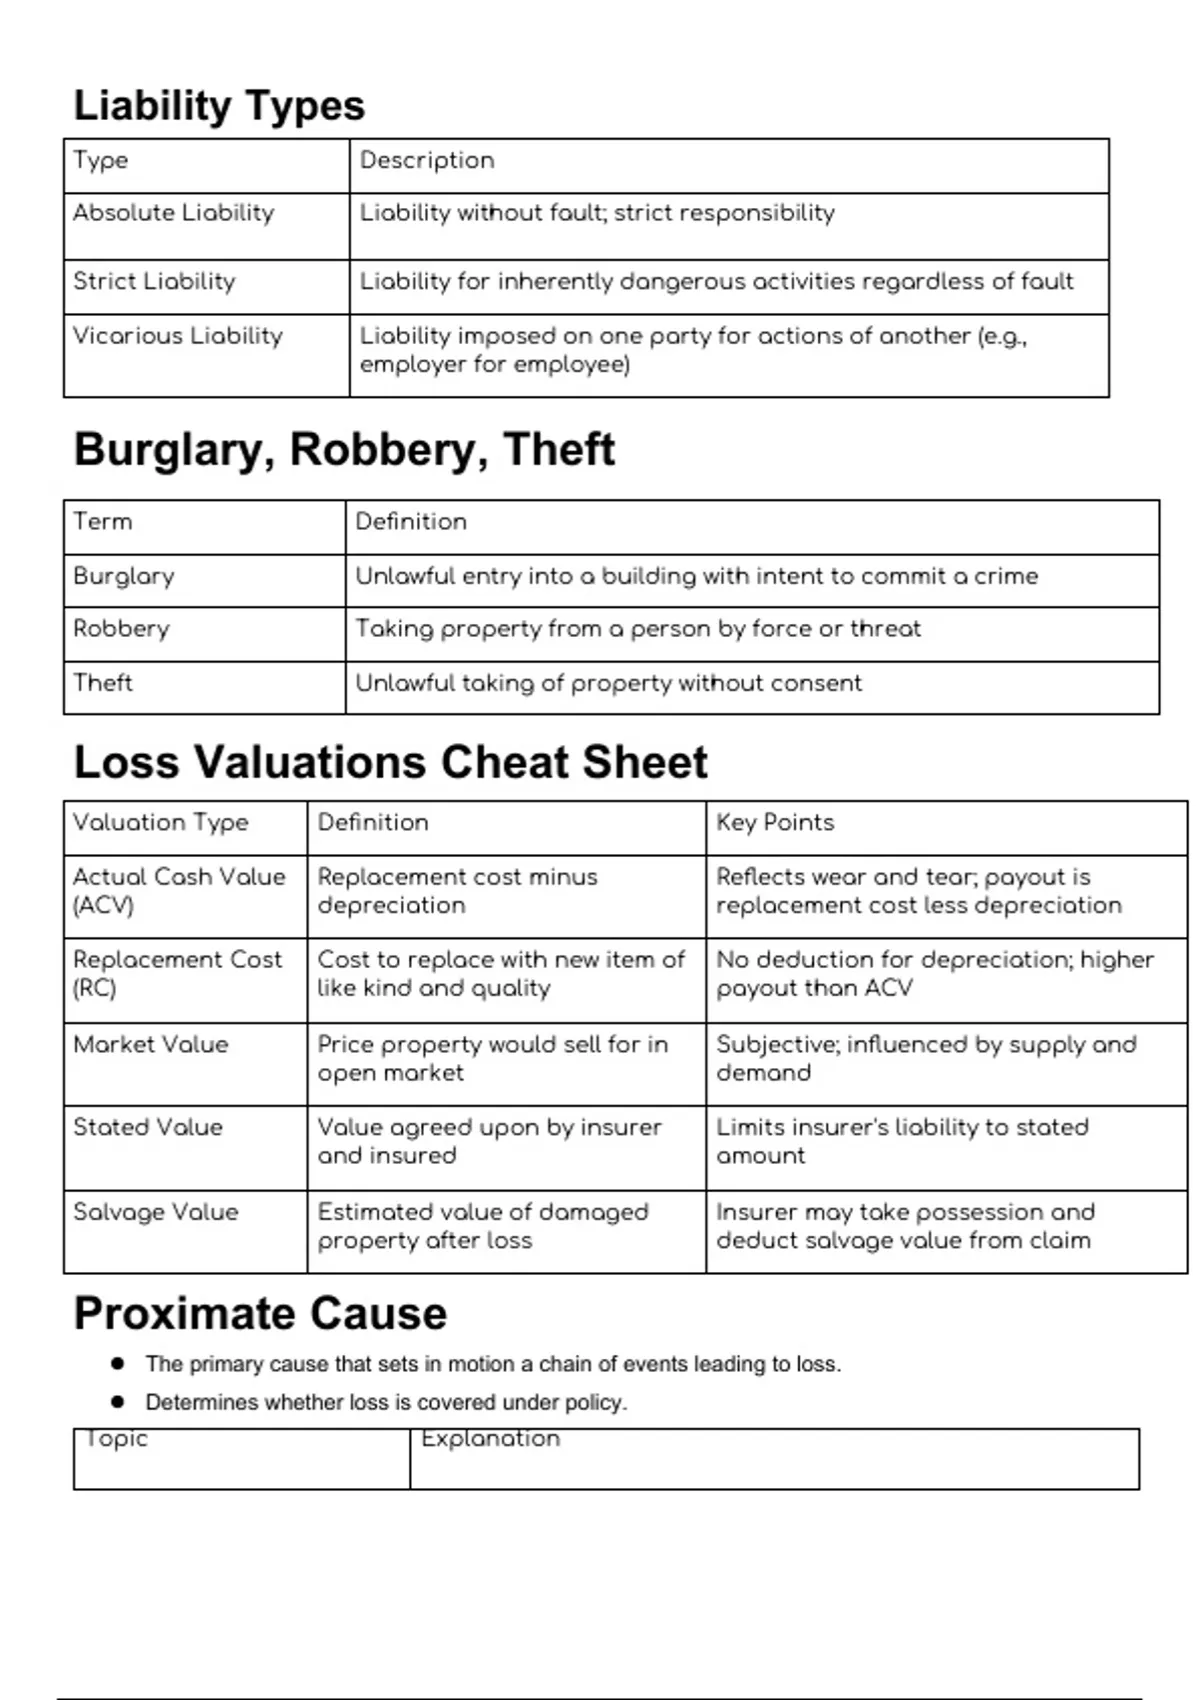
You will not be allowed to bring a calculator on most state exams. Some allow basic four-function devices. Either way, you need these formulas memorized cold because they appear in multiple questions and sometimes compound across two or three items in a row. Coinsurance formula: (Amount of insurance carried / Amount of insurance required) x Loss = Payment, subject to the policy limit. The amount required equals the property value multiplied by the coinsurance percentage stated in the policy. If the policy requires 80 percent coinsurance and the property is worth $200,000, you need at least $160,000 in coverage. Below that, you become a co-insurer and the payment is reduced proportionally. This shows up constantly. Actual cash value: Replacement cost minus depreciation. Depreciation is usually calculated as age divided by useful life multiplied by replacement cost. A roof with a fifteen-year lifespan that is ten years old has two-thirds of its value depreciated.
Premium calculation: Rate per $100 of coverage multiplied by the exposure unit, then adjusted by class rating factors. Commercial property rates are often expressed per $100 of building value and per $1,000 of contents value. You will see questions that give you a rate and ask for the premium on a $75,000 building at a rate of $0.45 per $100. The math is straightforward but the trap is usually the decimal placement or forgetting to apply the class factor. Deductible applications: Understand the difference between per-occurrence deductibles and aggregate deductibles. Per-occurrence applies each time a loss happens. Aggregate caps the total deductible across all claims in a policy period. This distinction matters on commercial policies and is a common source of wrong answers.
High-Yield Topics You Should Not Skip
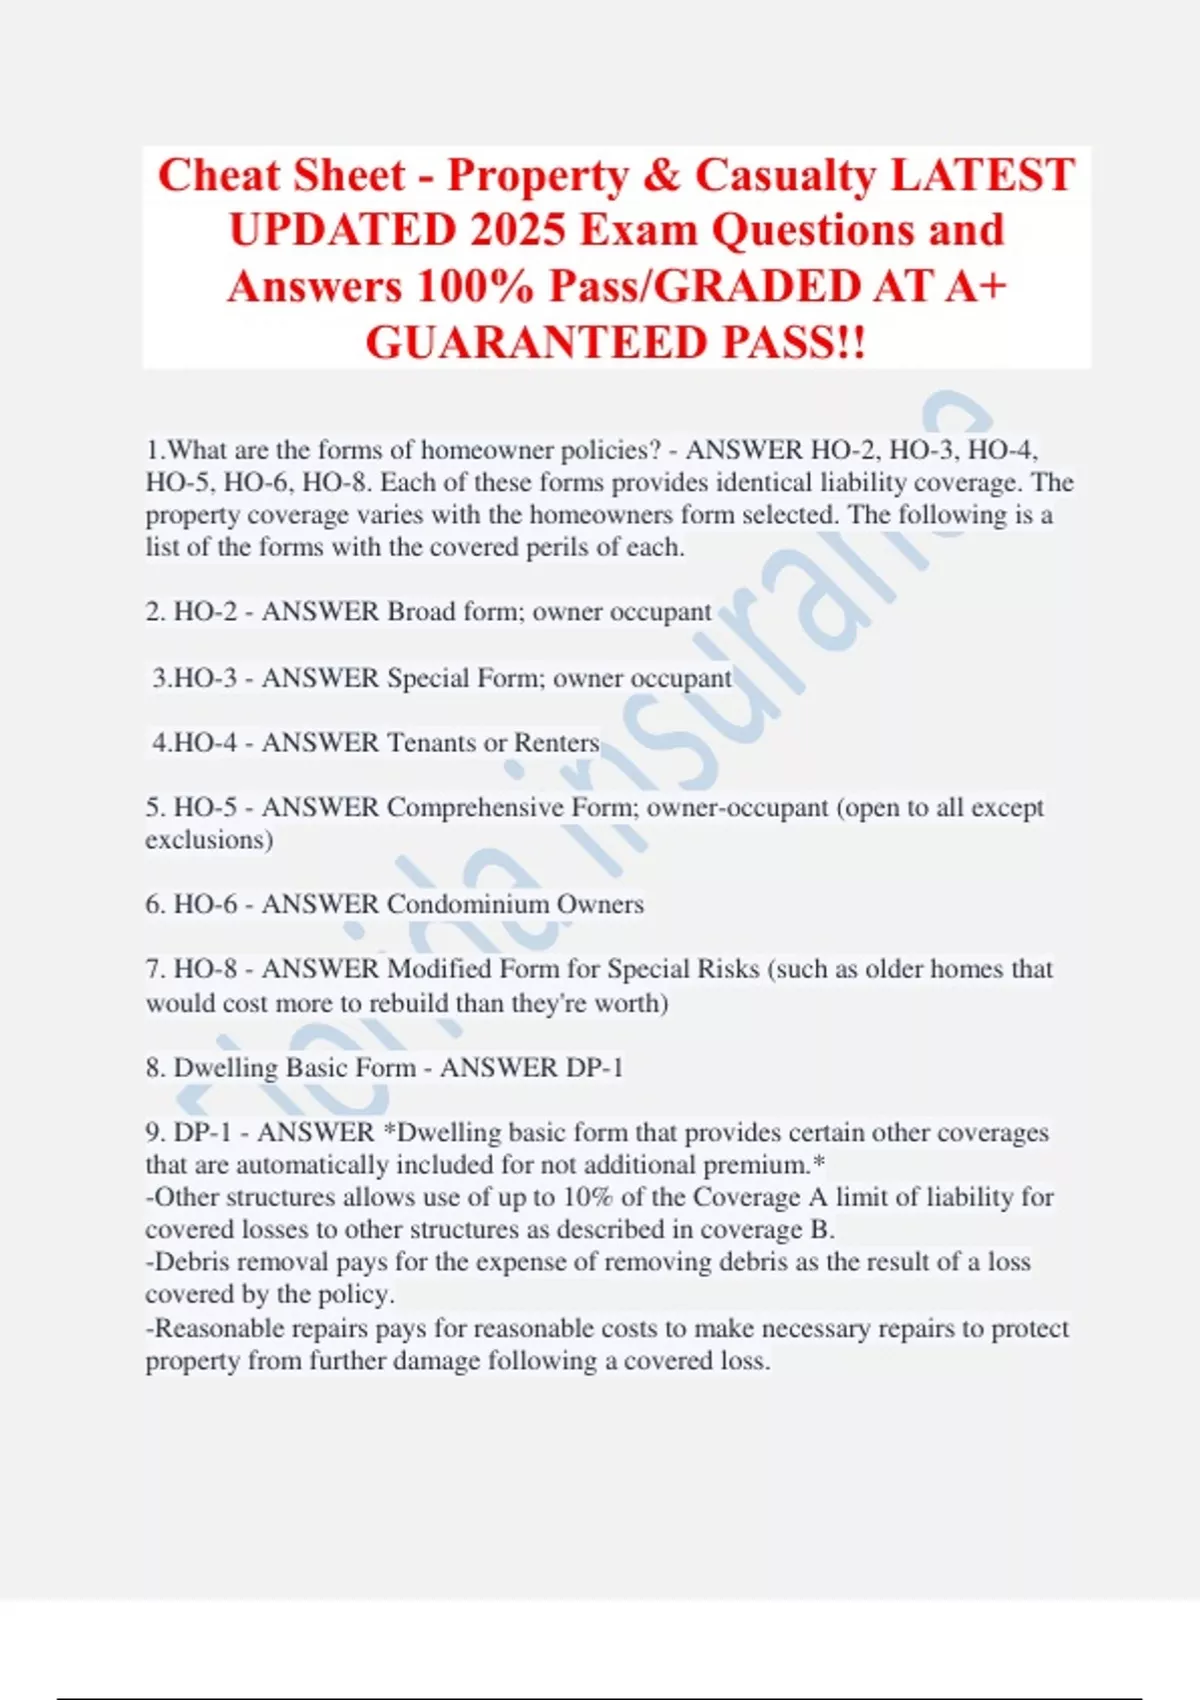
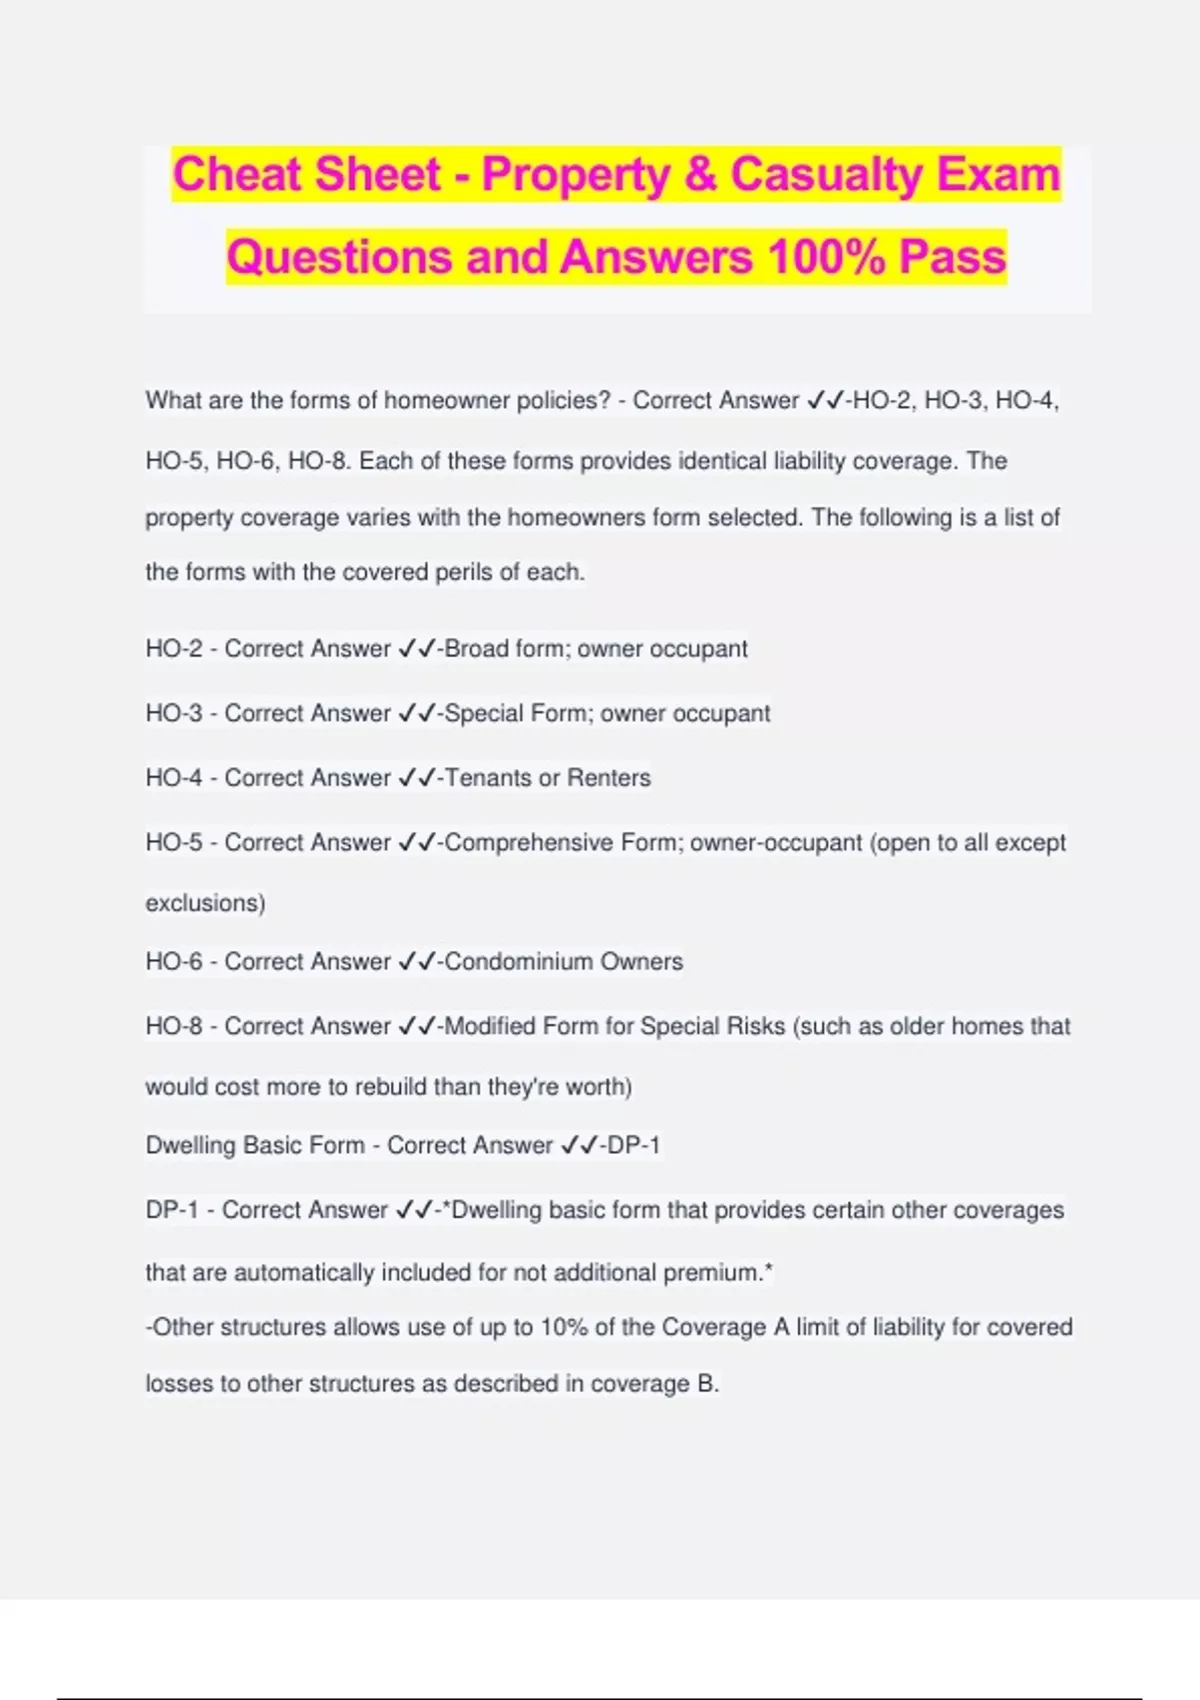
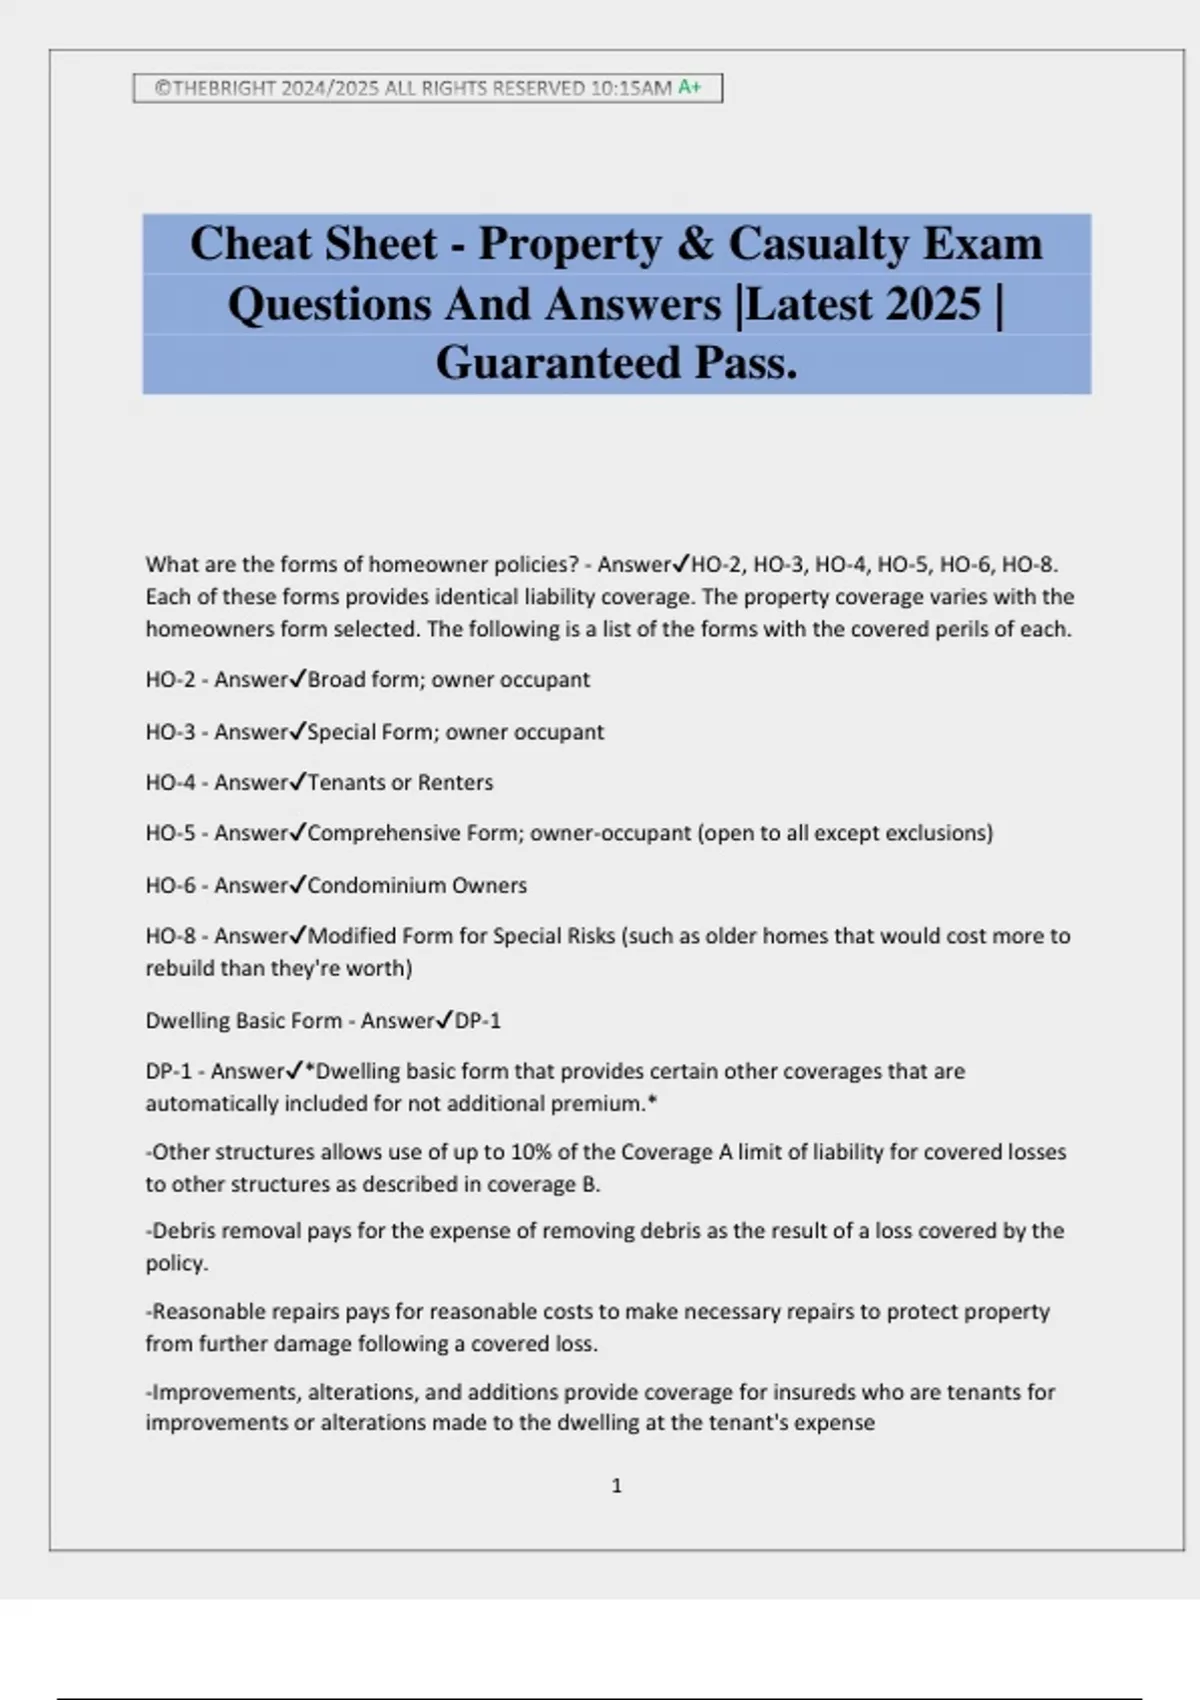
Insurance principles come first because they underpin every other question. Utmost good faith, indemnity, subrogation, contribution, proximate cause, and the eight characteristics of insurance are foundational. If you do not understand subrogation, you will struggle with recovery questions in both property and liability sections. Subrogation is the insurer's right to pursue a third party who caused the loss after the insurer pays the insured. The insured cannot do anything to prejudice that right. Waiving a claim against the responsible party before the insurer pays can void coverage. I have seen this tested directly. Contract law is heavily weighted. Offer and acceptance, consideration, legal capacity, and lawful object are required for a valid contract. A policy is a contract of adhesion, which means it is drafted by the insurer and any ambiguity is construed against the drafter. That is called the contra proferentem rule. It comes up on almost every exam. Memorize that term and what it means. Property coverages need the most attention. The ISO homeowners forms are the backbone. HO-3 is special form on the dwelling and broad form on personal property. HO-5 is special form on both. HO-4 is renters insurance with named perils on personal property. HO-6 is condo unit owners form. HO-8 is older homes with actual cash value Dwelling Coverage. The differences between these forms account for a large portion of the property section. I used to mix up HO-4 and HO-6 on practice exams until I wrote a dedicated comparison table. After that, those questions stopped being wrong answers.
Causes of loss forms are another trap. Basic form covers fire and lightning, external explosion, strike by lightning, explosion of a household appliance, smoke damage from a boiler or furnace, windstorm and hail, vandalism and malicious mischief, and aircraft or vehicles. Broad form adds collapse, freezing of plumbing, weight of snow and ice, ice dam overflow, and a few others. Special form is open perils on the covered property. The distinction between broad and special matters because the exam will describe a loss scenario and ask which form would cover it. A collapsed chimney due to weight of snow is covered under broad form but not basic. A wind-driven rain injury depends on whether the wind first created an opening, which is a common fact pattern. Liability coverage is equally important. CGL is the commercial general liability form and it covers bodily injury, property damage, personal and advertising injury, and medical payments. The operations versus products-completed operations distinction is tested frequently. Operations liability covers injuries happening during active operations. Products liability covers injuries after the product has left the insured's possession. The separation matters for claims made versus occurrence policies. Commercial auto is another area where people lose points. Business auto coverage forms have different structures than personal auto. You need to know Schedule A, B, C, and D and what each covers. Coverage A is owned vehicles. Coverage B is hired vehicles. Coverage C is non-owned vehicles. Coverage D is coverage for employees' automobiles. This is not intuitive and it does not appear in most casual study guides. I found it in the ISO form descriptions and added it to my cheat sheet as a simple table.
What Your Cheat Sheet Should NOT Include
Do not include lengthy paragraphs or full policy language. The exam is multiple choice and the questions are written to test quick recognition. Long-form study material slows you down during review. Do not include state-specific statutes unless they are published in your state's exam content outline. Do not include niche endorsements that rarely appear. Keep it tight. There is also a hard limit to how useful a cheat sheet is if you use it incorrectly. If you only read it the night before the exam without having done any practice questions, you will recognize terms superficially but still miss nuanced questions. The cheat sheet is a review tool, not a substitute for practice. I always pair cheat sheet review with at least two full-length practice exams. The practice exams reveal which sections of your cheat sheet are actually weak. You then go back and reinforce those areas. This cycle takes about six to eight hours total for someone who has already read through the material once. One limitation I want to be blunt about: a cheat sheet cannot help you if the exam uses heavily revised form numbers or new endorsements that were added after your study material was published. The P&C exam gets updated periodically. If your textbook is more than two years old, check the latest edition or supplement with current ISO form summaries from the ISO website. The core principles do not change. The form numbers and specific coverage language can.
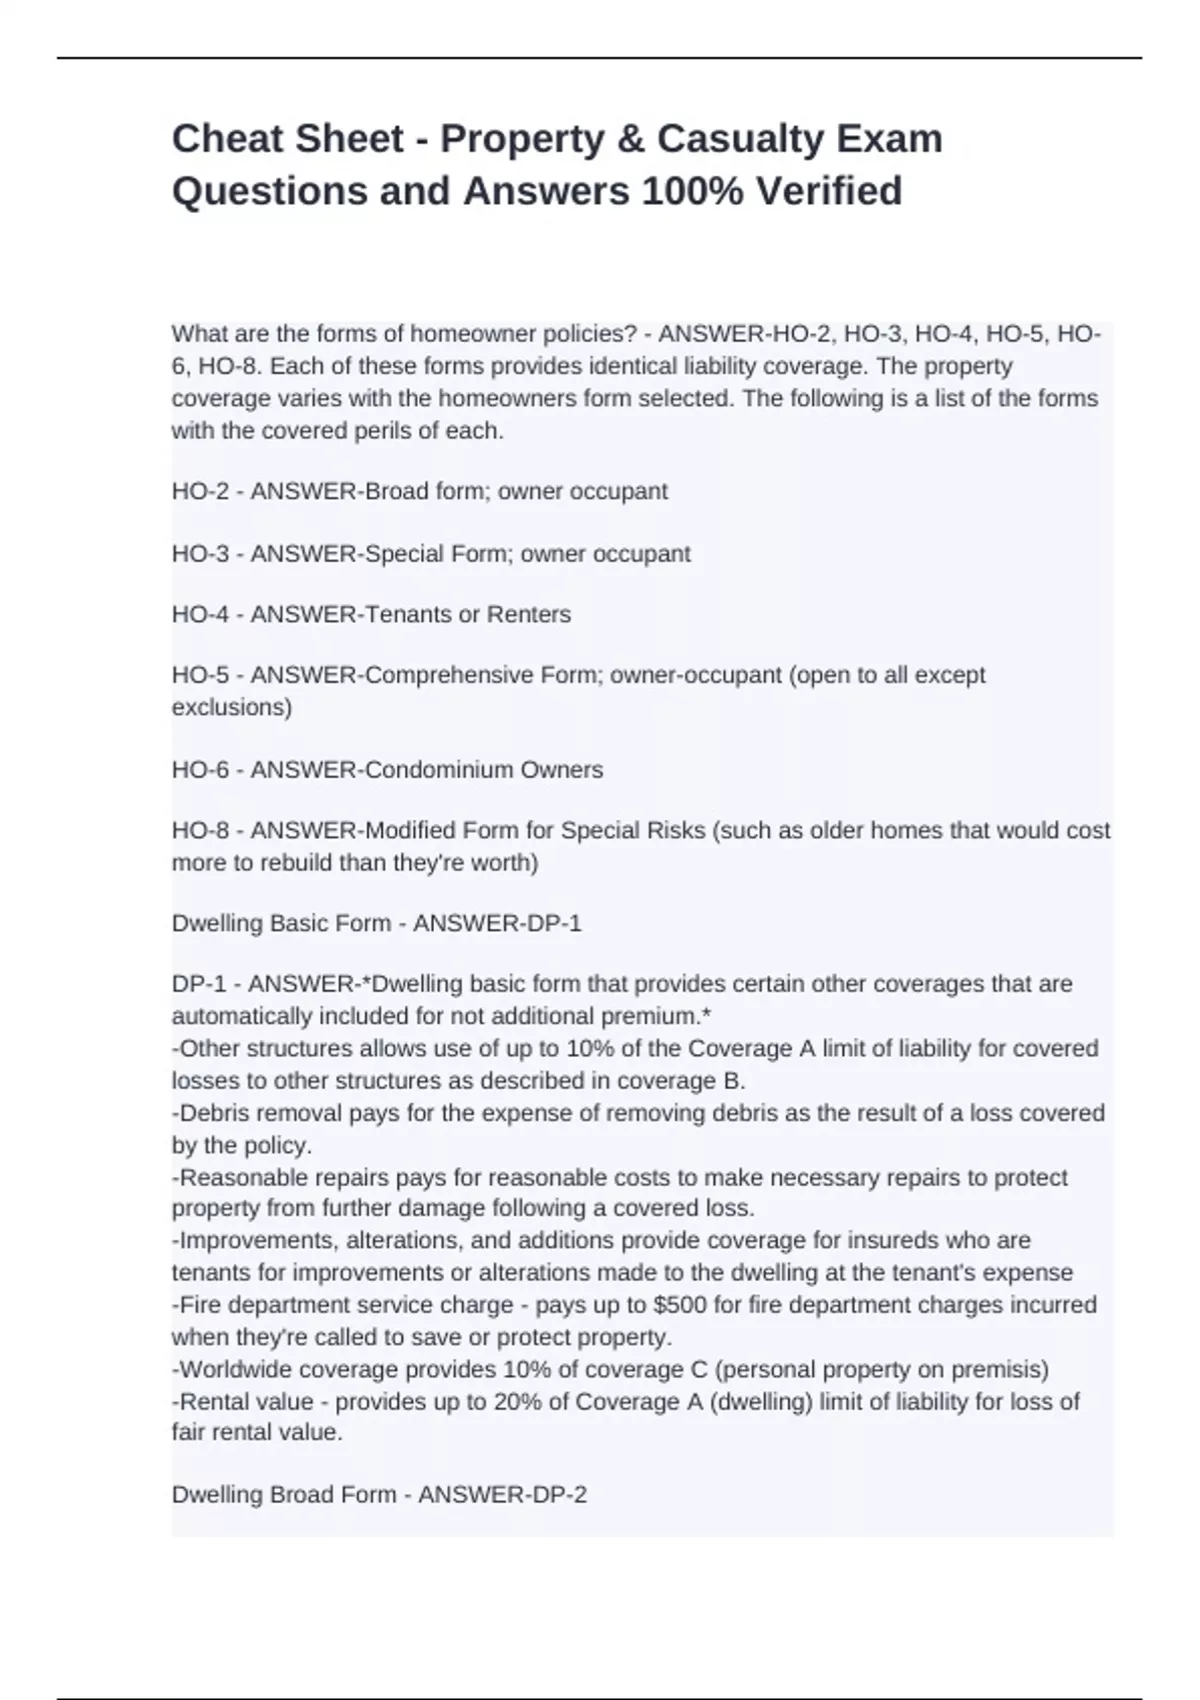
If you want a starting point, search for a Property And Casualty Insurance Exam Cheat Sheet PDF from a reputable insurance pre-licensing provider. States like Texas, Florida, California, and New York each have published sample questions that mirror the actual exam format. Work through those while building your own document. That combination of active recall and condensed reference is what actually moves the needle.