What Property Claims Adjuster Training Actually Looks Like
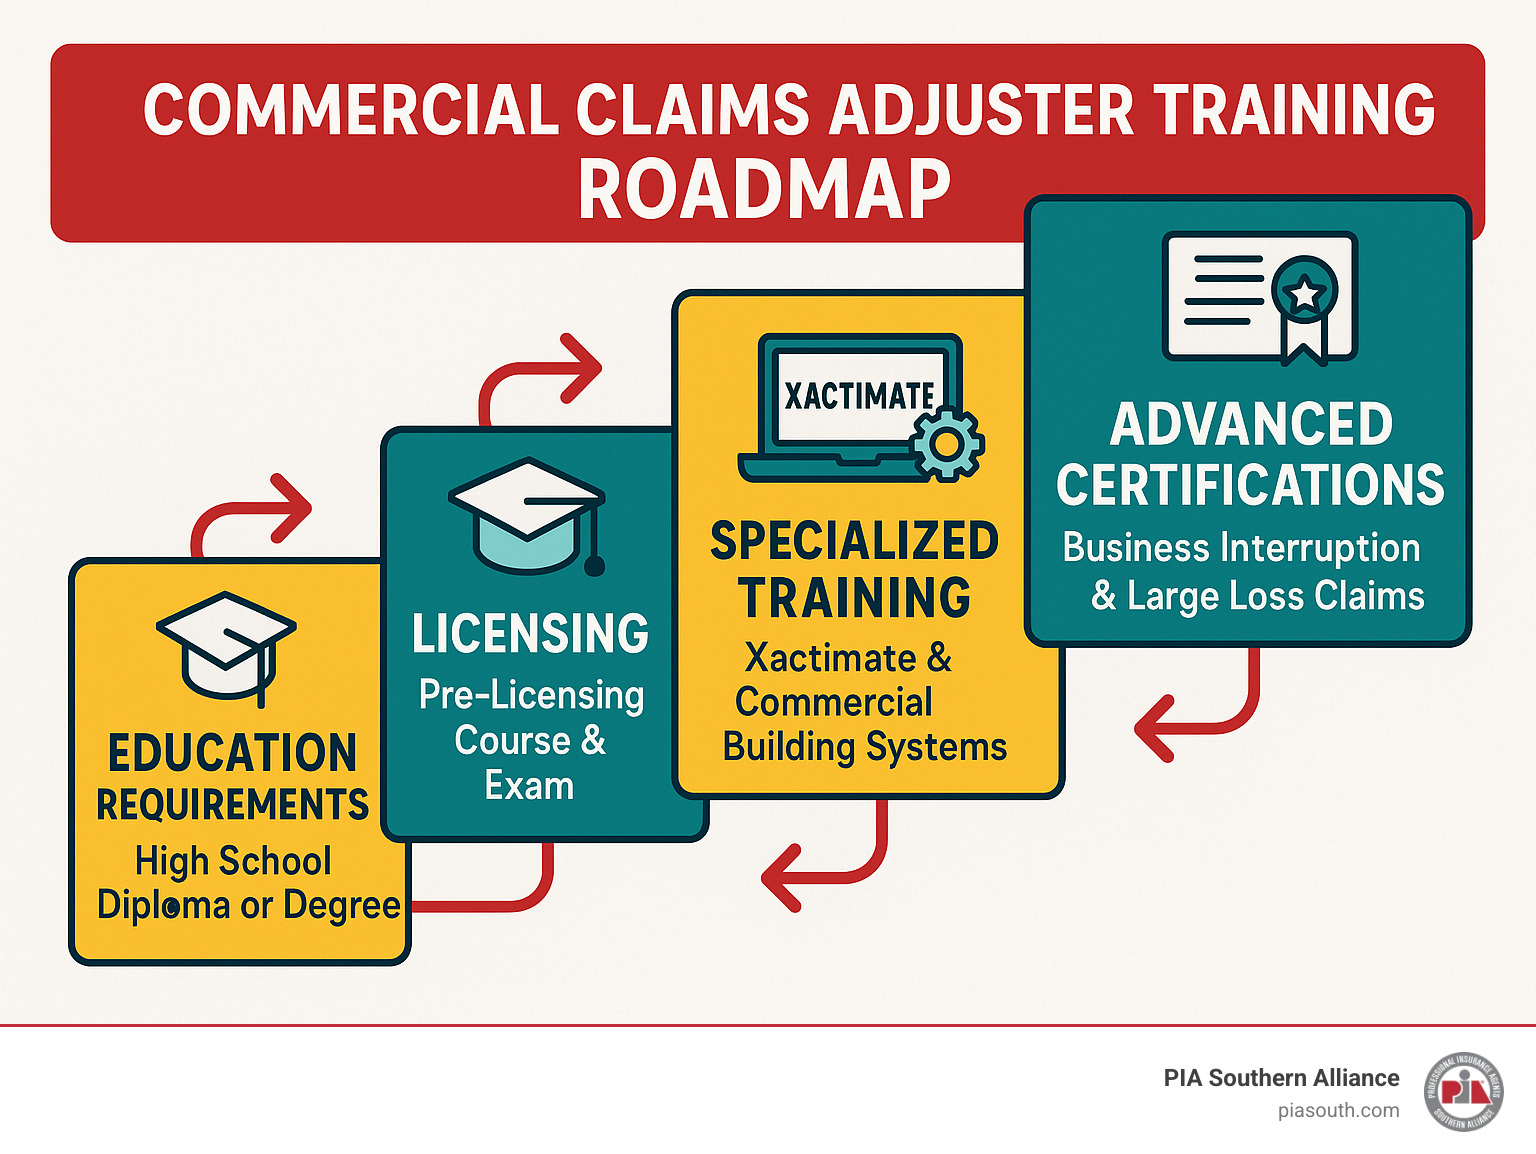
Most programs out there want you to spend three to five days learning the same four topics over and over. The good ones cut it down to two days and make you do real scope work on damaged roofs and water-damaged interiors until you can estimate blindfolded, which is literally what your supervisor expects on call day. The rest is just clicking through slides about ethics while they microwave coffee. I spent six years doing independent adjuster work out of a Honda Civic, so here is what I actually found useful in training versus what was filler. The core of the job is reading a policy, walking a property, figuring out what actually happened, and putting together a repair estimate that will survive a bad faith lawsuit if the claimant gets skeptical. That last part is the part nobody teaches you properly in the initial courses, but you will learn it fast enough when a claimant's attorney calls your office asking why your Xactimate line items don't match their contractor's quote.
Property Claims Adjuster Training Essentials
The training pipeline generally runs like this. You start with policy coverage basics, because every estimate you write depends on whether the cause of loss is covered, excluded, or buried under a endorsements page you have to read carefully. A standard HO-3 doesn't cover flood damage, and it doesn't cover wear and tear either, which means you can be standing in a kitchen with three inches of water and still deny the cabinet replacement if the source was a slow leak from the dishwasher supply line rather than a sudden rupture. The training modules usually present this as simple coverage questions, but the reality is messier, and you need to know how to document the distinction clearly in your report notes so the file doesn't get overturned later. Then you move into inspection methodology. This isn't about fancy cameras or drones, though those help. It is about learning the order in which you examine a structure. Roof first if weather is the suspected cause. Plumbing and HVAC second. Then interior finishes, then structure. You check attic ventilation, you look at the sealant around plumbing penetrations, you verify the drip loop under the sink. The people who rush this step end up writing estimates that miss the actual source of loss and the insurer pays twice because the original repair didn't address the cause. After that comes estimation software, and in residential property claims that almost always means Xactimate. You learn to build line items, apply local construction costs through the region modifiers, and attach photos to each line item so the reviewer can follow your logic without picking up the phone. The software itself is not hard to learn in a week if you already understand construction assemblies. It is harder to learn when you haven't looked at a roof truss in three years and you are trying to remember the difference between a rafter tie and a collar tie while someone watches you type.
The final piece is soft skills, because you are walking into people's homes when their worst day has already happened. You need to know how to explain an approval, a partial denial, or a reserved file without making the claimant feel like you are gaslighting them. The training videos make this sound easier than it is. Here is a problem I ran into repeatedly during my adjusting career that the training materials never really prepared me for. I was handling a water intrusion claim where the ceiling collapse looked like a roof leak, but the moisture meter readings in the attic told a different story. The insulation was dry above the drywall, and the framing members near the plumbing stack showed elevated moisture. The visible damage was in the bedroom ceiling directly below the bathroom, but the source was a pinhole leak in the PEX line that had been weeping slowly for months. My training said to estimate the visible damage and move on. What actually saved the file was taking thermal images of the framing, noting the temperature differential along the stack, and documenting the weep path in the scope so the insurer understood why the estimate included replacing sixteen linear feet of drywall and insulation rather than just patching the ceiling. If I had just followed the basic inspection checklist, the claimant would have come back three weeks later with mold growth and asked why I didn't catch the source. I learned to carry a Fluke pestle meter and use it methodically rather than relying on visual inspection alone, which cut my callback rate down noticeably. There are a few counter-intuitive things about this work that beginners miss. First, the largest settlements rarely come from the most dramatic damage. They come from the claims where you caught something subtle, like missing asbestos abatement in an older home before estimating the drywall replacement, or forgetting to include code upgrade requirements when the municipality has updated their plumbing code since the house was built. Second, your estimate doesn't have to be perfect on the first draft. It has to be defensible, which means every line item should have a photo reference, a source in the cost database, and a note explaining why a particular assembly was selected. Third, depreciation is where most new adjusters lose their margin. Actual cash value policies require you to calculate depreciation on every building component, and if you skip it or apply the wrong age schedule, the file gets flagged during QA. Learn the depreciation tables cold before you ever go on call.
Get the Full Details
The honest downsides of most training programs are worth knowing up front. They tend to over-index on residential single-family claims and under-index on commercial, which means you might finish a course and realize you have zero exposure to tenant improvement claims, landlord policies, or business income coverage, none of which are optional once you start doing larger cases. The software instruction is often shallow, usually two hours of screen recording while an instructor clicks through a prebuilt estimate. You will not retain Xactimate fluency from that alone. You need to build at least ten estimates from scratch, ideally on properties you have photographed yourself, before the menus stop looking foreign. Another limitation is that training rarely covers the administrative side of the job, which is where most adjusters burn out. File management, correspondence timelines, reserve setting discipline, and dealing with third-party administrators who change their reporting requirements every quarter are not taught in classroom modules. You pick these up by osmosis, which is another way of saying you make mistakes until someone more senior corrects you. The workaround is simple: keep a personal checklist for every phase of a claim from first notice of loss to closure, and review it before you advance the file. It takes about five minutes and has kept my QA error rate below two percent for three consecutive years. If you are looking to actually get trained, the main paths are state licensing courses, which are regulated by your jurisdiction and typically require thirty to forty hours depending on the state, followed by an exam. Independent adjuster companies like Sedgwick, ClaimAnt, and Allstar run their own training pipelines, usually two to five days of classroom plus shadowing, and they tend to be more practical than state-mandated programs because the trainers are currently doing the work. Professional organizations like the National Adjustable Adjusters Association and the Insurance Adjusters Association offer certification tracks, though those are credentialing more than foundational training.
For the software component, Xactimate offers its own training modules through Pearson VUE centers and online, which are the closest thing to a standardized curriculum in the industry. The cost runs roughly four hundred to six hundred dollars for the full residential course, and it is worth paying directly rather than hoping your employer covers it, because the certificate carries weight when you are applying to multiple carriers. The industry isn't going to hand you anything, and the training you get will only be as good as the effort you put into building real scope work outside of class. If you can spend a weekend going through your own house or a friend's house and building a complete Xactimate estimate from scratch, with photos, line items, and depreciation calculations, you will know more than half the people who pass the licensing exam on the first try.