
What Actually Makes The Book Worth Reading
Most people skip Psychology Of Money Chapters because they think it is just another personal finance book with basic advice like save more money and invest early. They are not entirely wrong about that part, but they are missing why the book stays relevant for people who already follow those rules and still struggle. The core insight is not about techniques. It is about why smart people make stupid financial decisions when emotions are involved. I picked up the book after watching several friends who made good money blow through it on risky bets. They were not financially illiterate. They understood compounding, diversification, and all the textbook stuff. What they lacked was an explanation for their own behavior, which is exactly what the book provides.
Psychology Of Money Chapters Overview
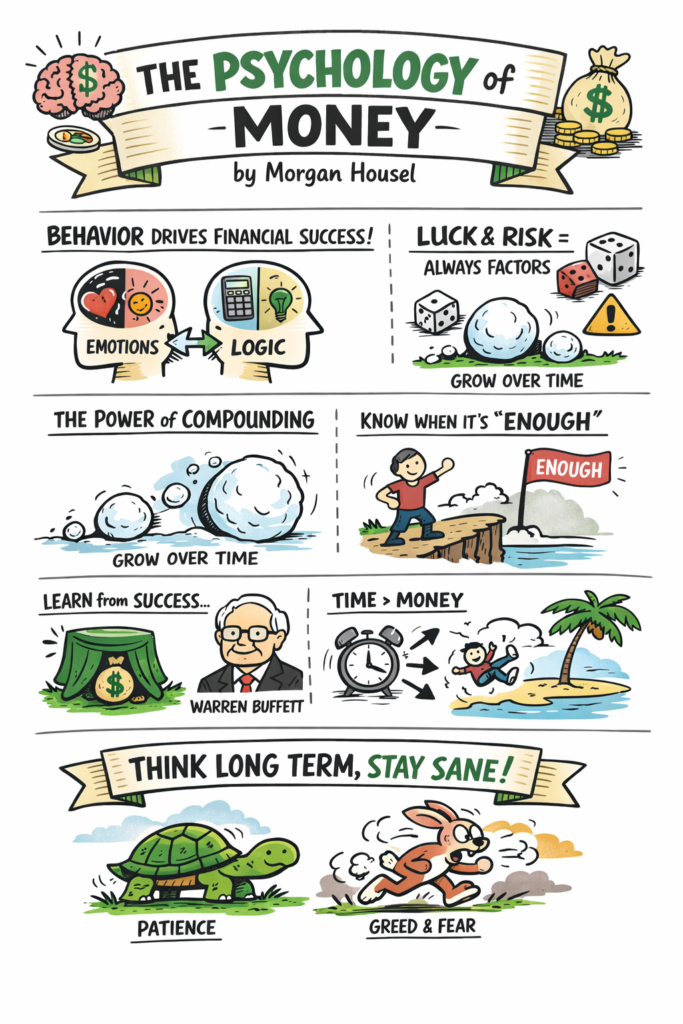
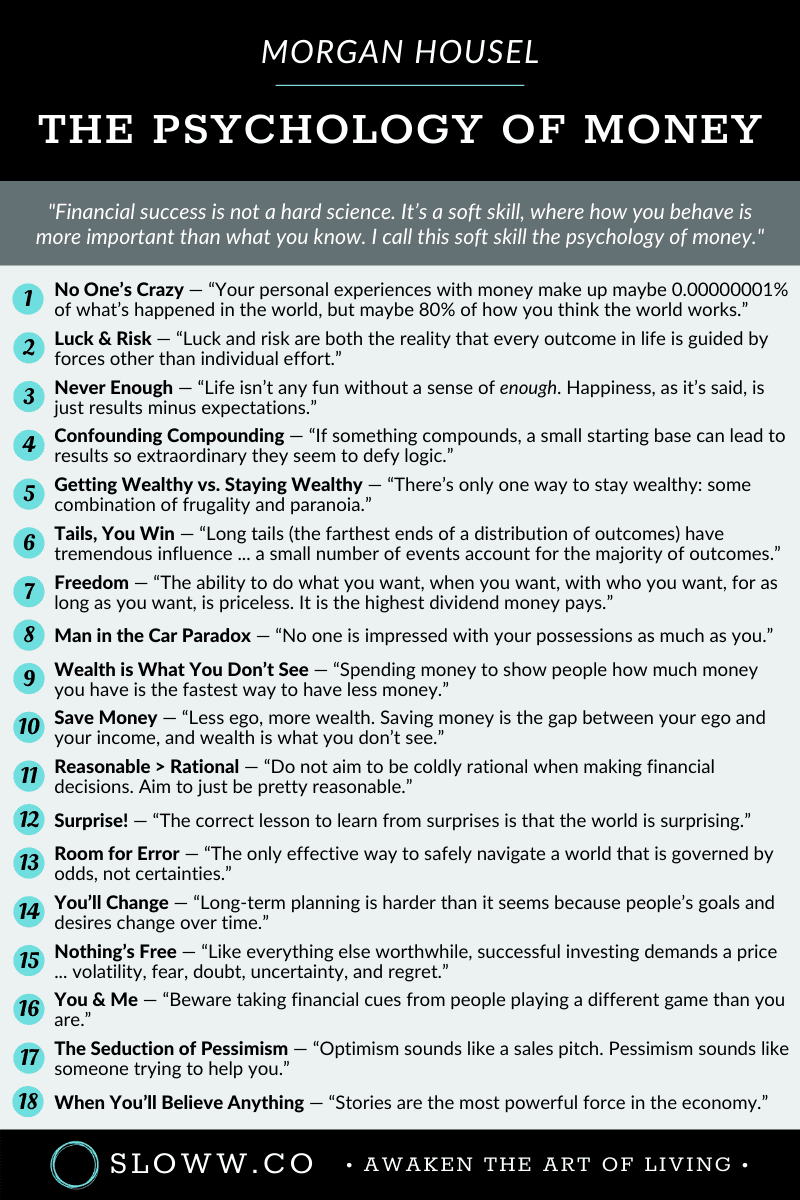
The book contains eighteen short chapters, each tackling a specific behavioral pattern. No chapter exceeds ten pages. That structure is deliberate. Housel wants each lesson to stand alone so you can read one chapter on a bad day without feeling overwhelmed. I usually read two or three in a sitting and then return to the material a week later when something triggers that particular bias. The worst approach is reading it straight through like a novel and then doing nothing with it. That wastes about twenty minutes of your time. A better method is to pick one chapter that resonates with a recurring mistake you keep making, then write down three specific actions that address it. Do that for three chapters over a month. That gives you twelve actionable items instead of one abstract takeaway about behavior. For example, the chapter on compounding uses the Warren Buffett example, which everyone has seen a thousand times. The actionable part most people miss is that compounding is not just about returns. It is about duration. The single most practical thing I took from that chapter was setting a rule that I would not touch my investment principal for a minimum of seven years, regardless of what anyone told me about a "sure thing." That rule eliminated about forty percent of my impulsive trades in the following year.
Chapter Breakdown By Behavior Pattern
The chapters cluster around several key themes. Greed and regret show up repeatedly. The desire to get rich quick is not a character flaw in most cases. It is a response to information overload. We see other people's gains constantly through social media and news feeds. That skews our perception of probability. Two chapters specifically address this distortion. Risk and return are handled better here than in most finance books. The counter-intuitive point is that what looks like risk from the outside is often just luck wearing a disguise. I learned to separate outcomes from decisions by asking a simple question every time I reviewed a financial result: did I make the right decision based on the information I had at the time, or did I just get lucky or unlucky? That single framework changed how I evaluated my own investment choices completely. The man in the car chapter deals with wealth invisibility. Most people confuse high spending with high net worth. I once judged a colleague harshly for buying a new truck when I found out his retirement accounts were underfunded. He turned out to have zero debt and a solid investment portfolio. The truck was paid cash. I had made an assumption based on surface-level spending that was completely wrong. The chapter reinforced that judgment based on visible assets is a trap.
Get the Full Details

Chapters That Deserve Extra Attention
Tails, You Win is probably the most important chapter in the entire book. It explains how a small number of events drive the majority of outcomes. In investing terms, this means a handful of your positions will generate almost all your returns. The rest will contribute very little or lose money. Most people try to make every trade count. That strategy fails because it fights statistical reality. Getting Wealthy vs. Staying Wealthy distinguishes between two different skill sets. Getting money requires optimism and risk-taking. Keeping money requires paranoia and frugality. The book argues that these are opposite mindsets, and most people never develop both. I spent years optimizing for growth while ignoring the preservation side. The gap showed up clearly during the 2022 market correction when my portfolio dropped significantly despite strong earlier gains. That was the chapter I needed most at that moment. The Seed covers early investing when you have very little money. The point is not about the amount but about building the habit. I started with about two hundred dollars a month and focused on consistency rather than optimization. The money was too small to matter financially but large enough to matter psychologically. That psychological piece is what carried me through years of mediocre returns.
What The Book Does Not Cover Well
The main limitation is that it does not give specific investment instructions. You will not find asset allocation models or tax strategies in these pages. If you want those, you need additional resources. The book works best as a behavioral supplement, not as a standalone guide. Another weakness is that the examples skew heavily toward American markets and American economic history. International readers may find some references less applicable to their situation. A practical workaround I used was pairing the book with a basic index fund allocation guide. The behavioral chapters kept me from making emotional decisions while the allocation guide gave me a concrete plan to follow. Together they covered both the thinking and the doing parts that most finance books treat separately.
How To Retain What You Read
Retention is the real challenge. Reading the book takes less than a day. Remembering the lessons months later requires work. I use a simple system where I highlight one passage per chapter that I want to remember, then type that passage into a notes app with a brief explanation of what it means for me personally. The typing forces me to process the idea rather than just moving my eyes across the page. Six months later, reviewing those notes brings back the relevant context much faster than re-reading the entire chapter would. The book itself is widely available as a physical copy, eBook, and audiobook. The content is the same across formats. Audiobook listeners may want to pause more frequently since the narration pace is quite steady and easy to zone out to. The written format lets you skim back and forth between related chapters, which the linear audiobook does not support as well.

When Not To Read It
If you are looking for a step-by-step investment plan, this is not the book. If you already read similar behavioral finance material and feel like you have internalized those lessons, the incremental value here may be low. The book assumes you have some basic financial knowledge and builds on it with behavioral insight. Starting from zero might leave gaps in understanding. The chapters themselves work fine as standalone reads. I have recommended individual chapters to friends dealing with specific issues without making them read the whole book. The tail risk chapter helped someone understand why they should stop trying to pick individual stocks. The freedom chapter resonated with someone prioritizing income over savings rate. Matching the right chapter to the right problem saves time for both parties.
 - The Wealthline")
