Working Through a Publishing Company Audit
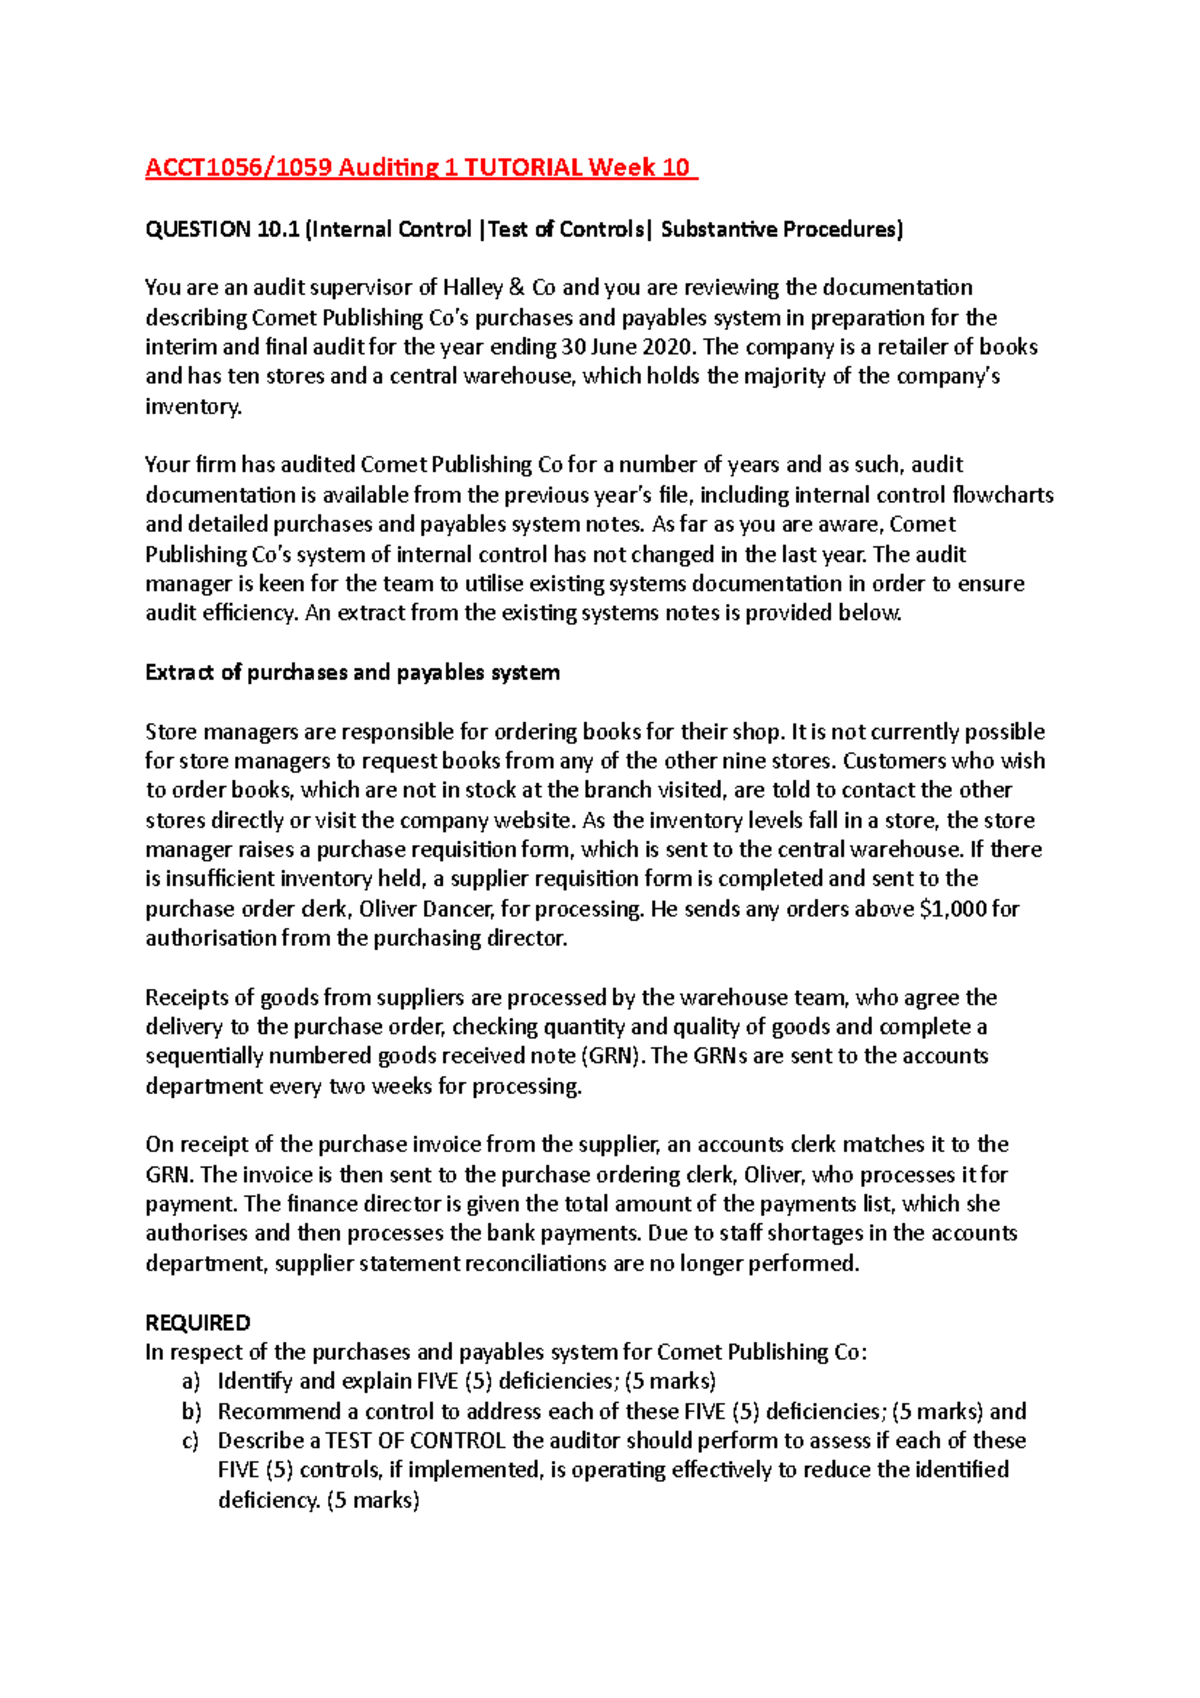
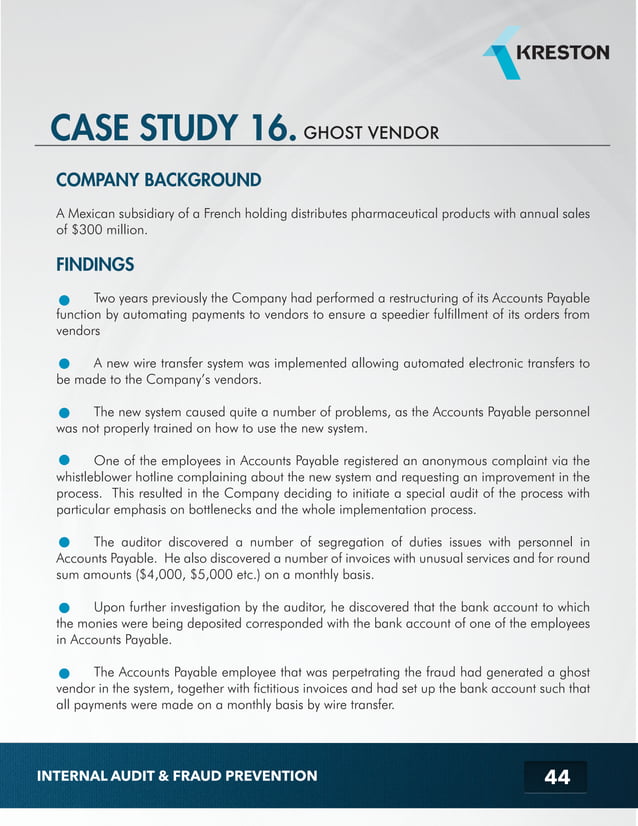
Publishing Company Audit Case Answers come up more often than you'd think, especially when your books start showing discrepancies between what the royalty engine reports and what your internal accounting says should be there. The last time I dealt with this, it was a mid-sized fiction publisher who had rolled out a new print-on-demand setup alongside their traditional warehouse inventory. Their audit flagged a $47,000 variance across twelve titles over three quarters. Took me three days to find the root cause, and it wasn't anything dramatic. The core of any publishing audit comes down to reconciling three systems that never quite agree with each other: the rights management platform, the royalty calculation engine, and the general ledger. When you pull Publishing Company Audit Case Answers, what you're really looking at is a paper trail showing where money was earned, how much was owed to authors, and whether the cash actually moved correctly. I learned early on that most audit failures happen at the interface points, not inside the systems themselves. The royalty engine trusts the sales data coming from the distributor portal. The general ledger trusts the journal entries posted by whoever handles month-end close. The rights system trusts whatever metadata was entered when the contract was first signed. When those three don't align, you get answers that look wrong even when they're technically defensible.
One thing nobody warns you about: audit cases in publishing almost always involve co-owners. A single title can have a primary author, a translator who's owed a fixed percentage, a rights holder who took a sub-license to Germany, and an estate that came into play after a death. Each of those relationships has its own payment terms, territory restrictions, and tax implications. If your audit answer sheet doesn't break out every co-owner line by line with the correct rate and effective date range, it won't hold up under review. I've seen two separate auditors reject the same perfectly good report because the translator's share wasn't tracked on its own transaction line. The practical way to handle this starts with pulling your royalty statements for the audit period and matching them to actual bank deposits. Line up the statement gross, the net after royalties, then the deposit amount. Any gap larger than two percent warrants a drill-down. In my experience, the gap usually turns out to be either an unclaimed right (a territory where you sold but didn't set up the proper author code) or a reversion that wasn't flagged before the next statement cycle ran. Here's the edge case that ate my Tuesday last year. A publisher sent me their audit file and everything looked clean until I checked the advance amortization schedule for a non-returnable advance. The system had written off the full advance against Year 1 sales, but the contract specified clawback on unearned portions if sales fell below a threshold. The clause was in the addendum, not the master agreement. The royalty engine had never seen it. I found it by cross-referencing the payment history against the signed contract PDF, not the system-generated terms summary. If you're doing an audit without pulling the actual executed contracts, you're auditing a summary, not the truth.
For the mechanics of working through your own case, here's what I actually use: Start with the title register. Every ISBN that had activity in the audit window, plus any that were dormant but still had accrued but unpaid royalties sitting in a suspense account. The suspense account is where most small variances hide. A title might have generated $312 in royalties that never got assigned because the author's banking details were incomplete and the system auto-routed it to suspense instead of issuing a check. Next, pull the distributor remittance reports for the same period. Match each remittance to your internal sales invoices. Look for returns that hit the distributor books but haven't been recorded in your system yet. Return windows create natural timing differences, but if the difference stretches beyond sixty days past the standard return period, flag it. I usually keep a running log of open return adjustments and clear them systematically. Without that log, you'll miss things.
Get the Full Details

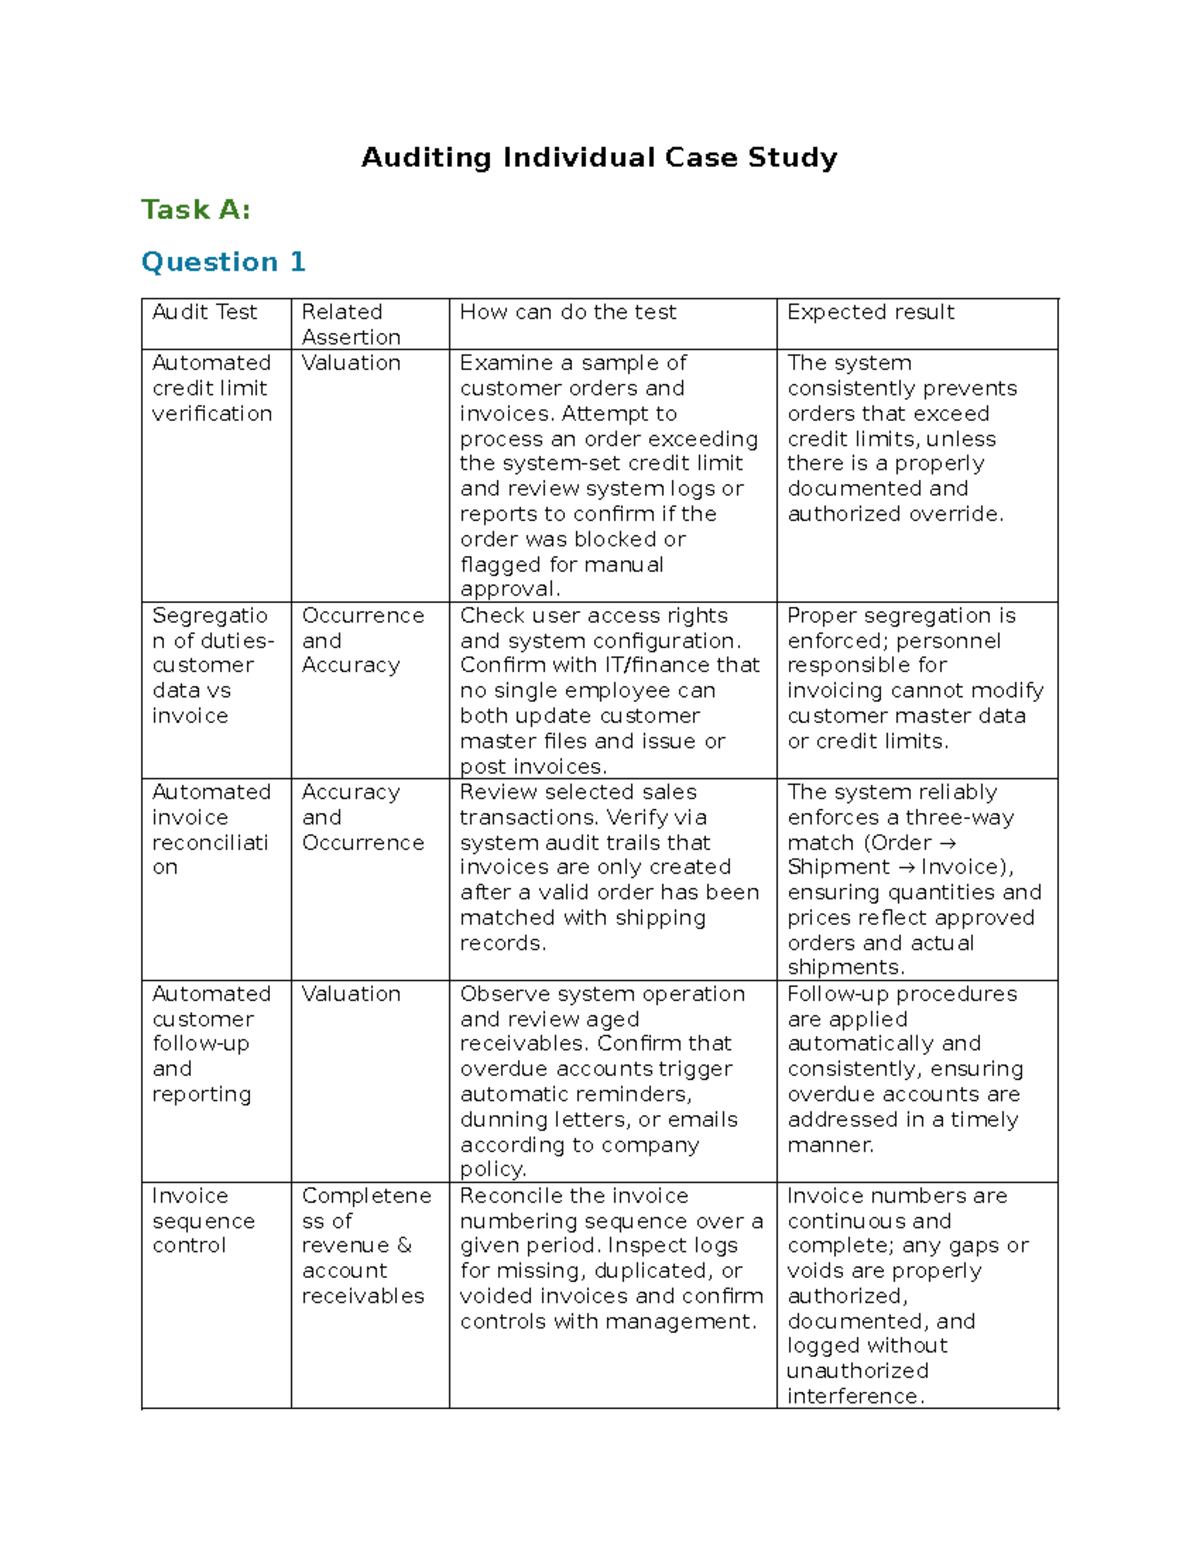
Then hit the rights matrix. This is where the work gets tedious. Go title by title and verify every right being exploited against what's actually contracted. Territory, format, language, term length, exclusivity. I once caught a case where a publisher was paying French royalties at the domestic rate because the rights system had the territory mapped to "France" but the contract granted only "Francophone Africa," which carried a different rate schedule. The answer looked correct until I compared the rate table to the actual contract terms. When you're assembling your final answer document, include the supporting schedules. Don't just state the variance number. Show the opening balance, the activity during the period, the closing balance, and a line-by-line reconciliation. Auditors skip past narratives and go straight to the math. If the math doesn't carry forward cleanly from one schedule to the next, they'll assume error rather than investigating. A few counters to keep in mind. Automated audit tools in publishing platforms tend to smooth over exceptions rather than surface them. The default behavior is to allocate unattributed royalties to a proportional pool based on existing author records, which masks missing data rather than exposing it. Run your audit in a manual or semi-manual mode at least once before trusting the automated output. Second, don't rely on the publisher portal as your sole data source. Portals are designed for reporting, not verification. If you need hard evidence, request the raw GL exports and distributor-level transaction files directly.
The downside of doing a thorough audit like this is time. A honest assessment for a publisher with fewer than two hundred active titles usually runs twenty to thirty hours depending on how clean their data is. Messy data doubles that. The alternative is cutting corners, which works until it doesn't. I've seen a publisher skip the suspense account review for three cycles, accumulate a six-figure liability, and then try to absorb it into the next audit as a single adjustment. That doesn't work. Auditors require traceability. If you're working through a specific case right now, the fastest path to solid answers is building a reconciliation template before you touch any data. Columns for ISBN, title, statement gross, remitted amount, royalty paid, variance, variance reason code, and corrective action taken. Fill it row by row. When the spreadsheet is complete, the answers are already in front of you. You just need to read them.