Reading QQQ Valuation Without Getting Fooled
The QQQ tracks the Nasdaq-100, which means its PE ratio is heavily influenced by a handful of mega-cap tech stocks. When I first started paying attention to this, I assumed the PE ratio worked the same way across every index fund. It doesn't, and that distinction matters when you're trying to make a decision. The most straightforward sources are Yahoo Finance, FRED (Federal Reserve Economic Data), and Koyfin for anyone who wants slightly cleaner charts. Yahoo gives you trailing PE out of the box. FRED has the Nasdaq-100 PE ratio series directly, which sidesteps the problem of the ETF's PE being slightly different from the index PE due to cash drag and expense ratios. The difference is usually small—about 0.2 to 0.5x—but it adds up during periods where you're making timing decisions based on percentile thresholds. My personal workflow involves pulling the FRED series (symbol NADPUK) because it's point-in-time data without the lookahead bias that sneaks into some other sources. Most charting tools show you the current PE but don't flag when they backfill earnings revisions. That backfill issue is where I got burned. In early 2023, I was looking at the five-year percentile for QQQ's PE and saw what looked like a 42nd percentile reading. When I went back and manually verified using GAAP earnings as reported at the time (not revised), the actual percentile was closer to 38th. Minor discrepancy on paper, but meaningful if you're using a 40th percentile threshold as a buy signal. I started keeping a spreadsheet that cross-references the reported PE against the earnings restatements from each quarter, and the divergence wasn't worth the complexity long-term. I just switched to using the forward PE for signals and the trailing PE for confirmation instead.
If you want raw data dumps, FRED provides downloadable CSV files for free. Morningstar and YCharts offer historical PE series but require subscriptions. The quick-and-dirty approach using Yahoo Finance involves pulling the daily PE field for QQQ and then normalizing it yourself against a rolling window. That self-rolled method works fine if you know how to handle NaN values at the edges of your lookback period. Most people skip that step and get weird readings at the start of any new dataset.
What the History Actually Shows
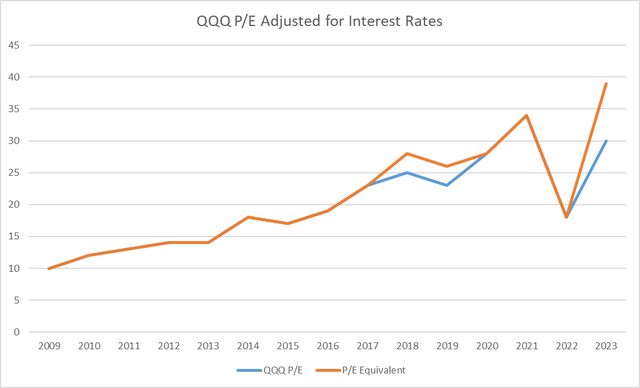
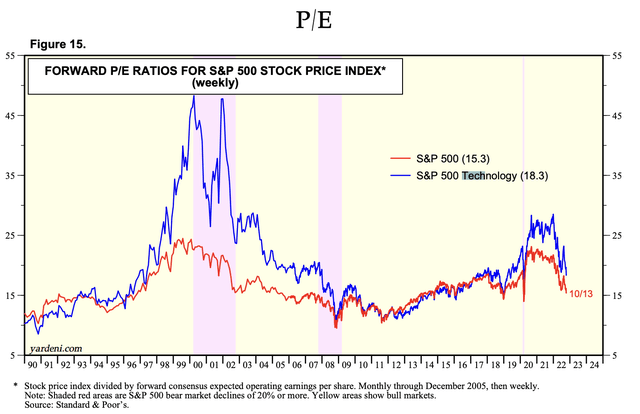
The Nasdaq-100 PE has traded in a remarkably wide band over the past few decades. During the late 1990s dot-com peak, the index PE climbed well above 60x on a trailing basis. By 2002, it had compressed to roughly 20-25x. The period from 2010 through 2020 saw it hover mostly between 25x and 35x. Post-2020, with the Fed's balance sheet expansion and the growth-stock rally, it pushed back toward the upper end of that range and occasionally above it. The important thing most people miss is that the PE of the Nasdaq-100 and the PE of the S&P 500 tell you different stories about the same market. The QQQ PE can be 15 points higher than the SPX PE during expansionary cycles because the index is tech-weighted, and tech earnings tend to be more volatile and more easily manipulated through buybacks and accounting changes. During contraction phases, that gap can compress rapidly. In March 2020, for example, the QQQ PE dropped faster than the SPX PE because growth earnings collapsed quicker on a trailing basis before the actual earnings revisions hit. Using a simple historical average like "the PE is above its 20-year mean, therefore expensive" is an oversimplification. Interest rates matter enormously for what constitutes a reasonable PE. When the 10-year Treasury was sitting at 1.5% in 2021, a 35x PE felt normal. At 4.5% in 2023, that same multiple looked stretched even though earnings had grown into it somewhat. I've seen too many people use a flat percentile threshold across changing rate environments and end up buying at peaks or selling at floors because they didn't account for the macro backdrop.
Get the Full Details
Practical Pitfalls
One thing nobody warns you about is the impact of index composition changes. The Nasdaq-100 gets rebalanced quarterly, and companies drop in and out based on market cap and listing requirements. When a heavy-weight stock like Pfizer or AbbVie gets added during a period when their earnings are depressed, it drags down the overall PE of the index temporarily. Conversely, when high-PE growth names rotate out, the PE drops without any real change in market sentiment. This isn't theoretical—I watched the QQQ PE tick down nearly a full point in one quarter simply because a few pharma stocks entered the index at low earnings multiples, and it had nothing to do with valuation compression. The forward PE smoothed that out, which is why I prefer using both metrics together rather than relying on the trailing number alone. Another issue is stock splits. The Nasdaq-100 has had several notable splits over the years, and while most modern data vendors adjust for this automatically, older datasets and some free charting tools don't. If you're pulling data from multiple sources and the numbers don't align going back more than five years, check whether someone is treating splits as price adjustments or not. The PE should be unaffected by splits since both price and earnings per share move proportionally, but broken price series can create phantom PE spikes that look like real events. The biggest limitation of the PE ratio for QQQ specifically is that the index is so concentrated. Apple, Microsoft, Nvidia, Amazon, Meta, and a handful of others make up a massive portion of the weighting. Their earnings trajectories dominate the index-level PE, which means the QQQ PE can look cheap or expensive based entirely on how those six or seven companies perform, not on broad market conditions. During the 2022 downturn, the QQQ PE looked relatively benign compared to the SPX because Nvidia and Meta had fallen harder in price than their earnings had declined, creating a statistical distortion. The trailing PE didn't reflect the incoming earnings recession that became clear later. Forward PE caught it sooner, but even that has its own lag depending on analyst estimate revisions.
Where to Get the Data
FRED: search for NADPUK or NADOFFPUK for the off-season adjusted series. Free, no signup required for downloads. Yahoo Finance: type "^NDX" for the index PE, or "QQQ" for the ETF PE. The index version is cleaner for historical analysis since it isn't affected by the ETF's cash position. Portfolio Visualizer: provides percentile rankings and rolling PE charts if you want to backtest a valuation-based approach. The free tier has limited exports but is sufficient for most people looking at quarterly data.
Macrotrends.net: aggregates the long history in a single chart, useful for getting a sense of the full timeline from the early 1990s onward without building your own dataset. The real question isn't whether the Qqq Pe Ratio History suggests the market is cheap or expensive right now. It's whether you understand what part of that history you're actually looking at and what assumptions are baked into the number. Trailing PE, forward PE, cyclically adjusted PE—they all answer different questions, and using the wrong one for your timeframe will give you the wrong signal.