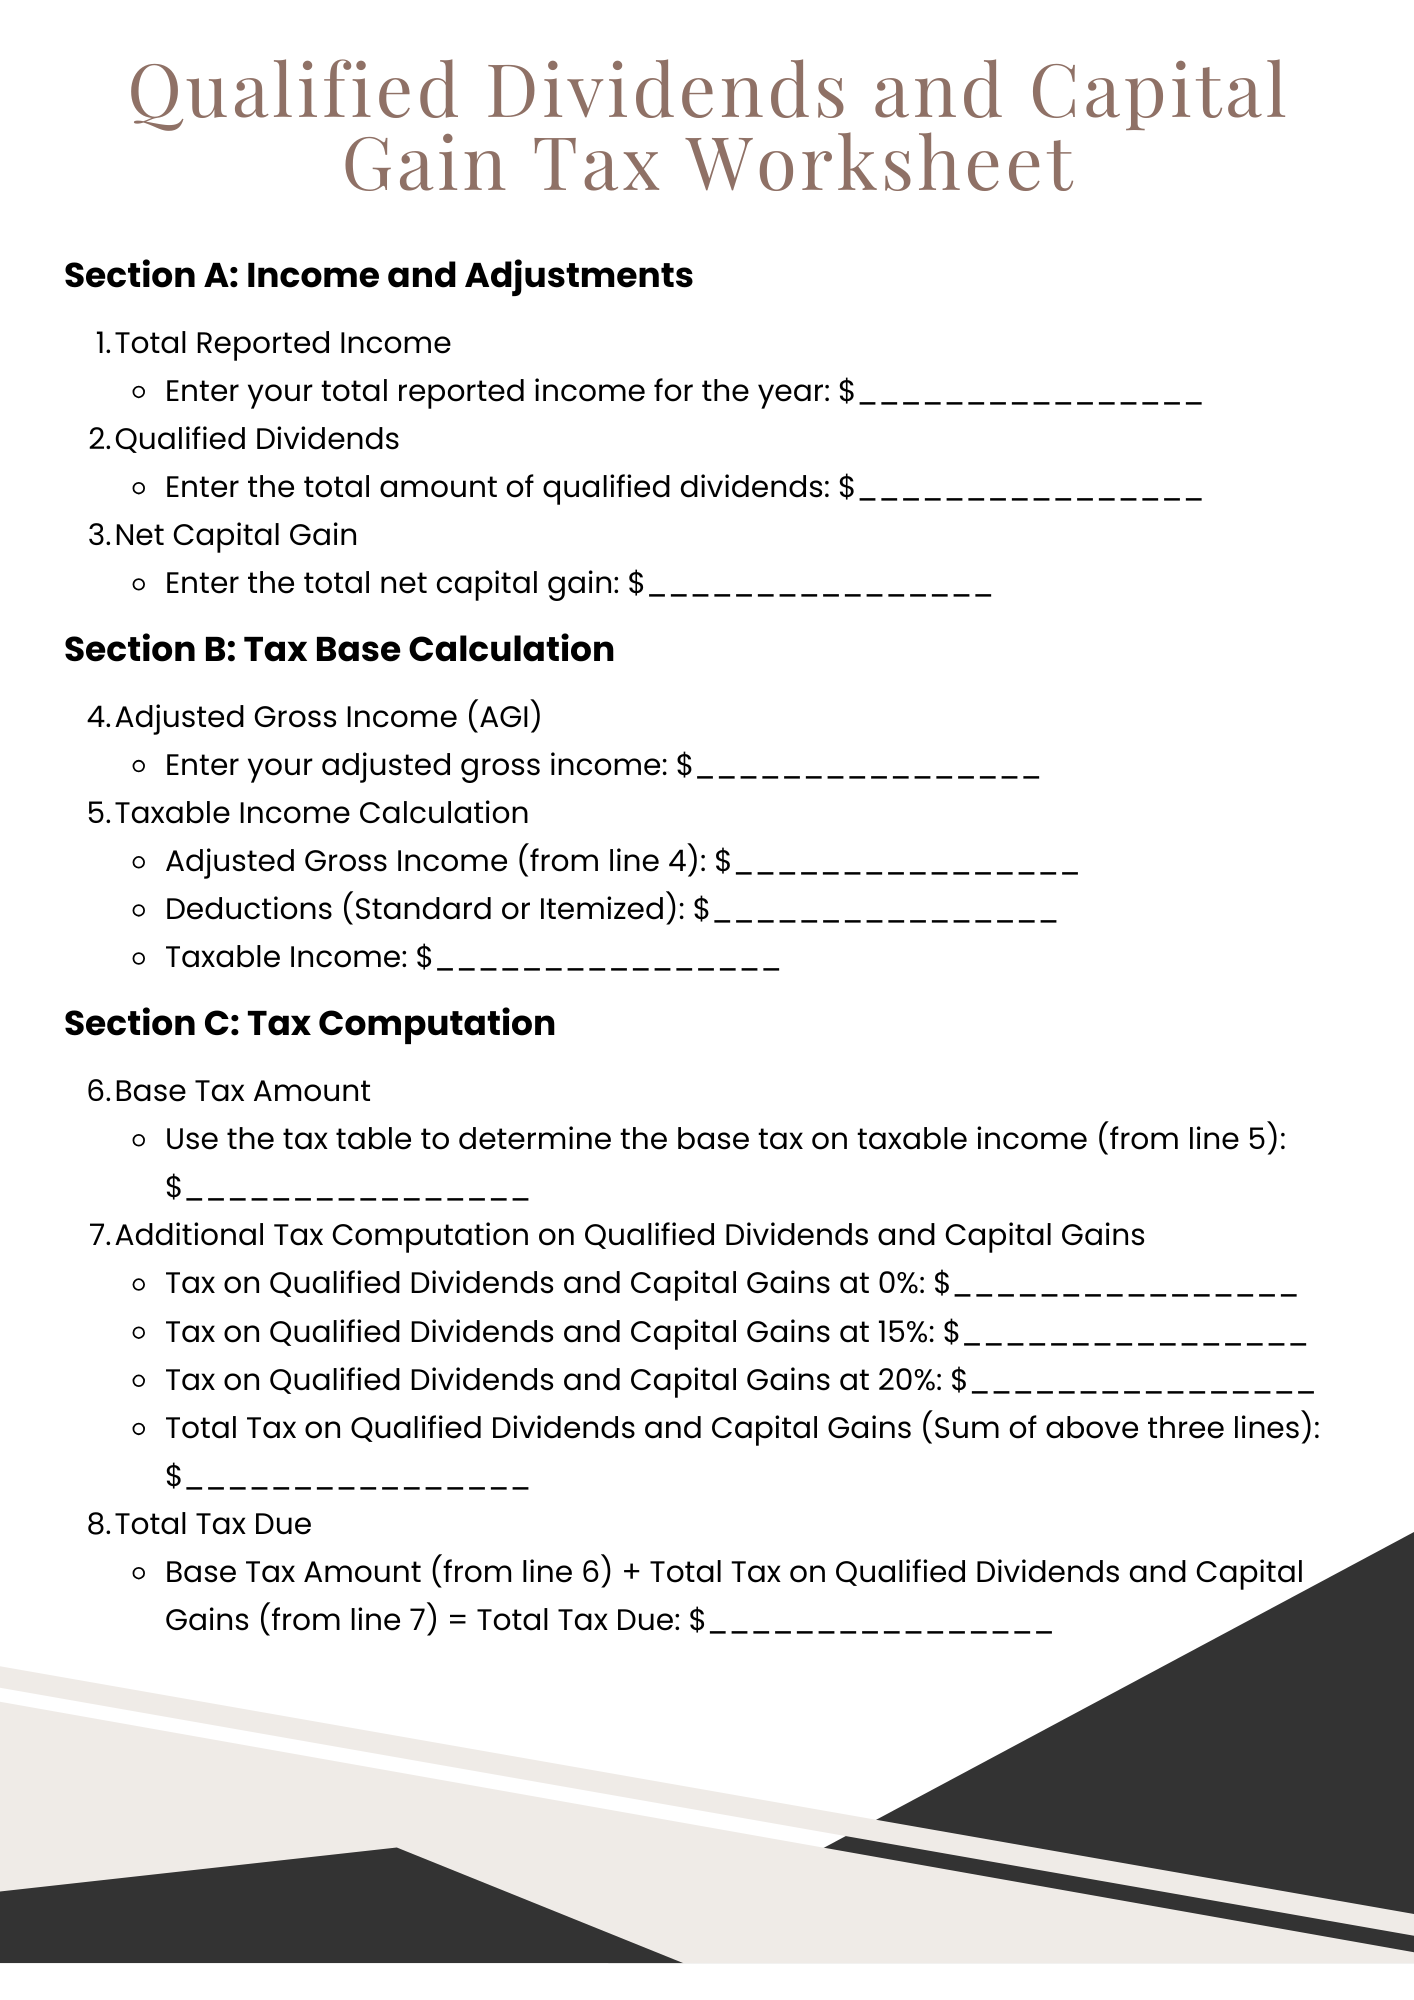
Understanding the Qualified Dividends and Capital Gain Tax Worksheet
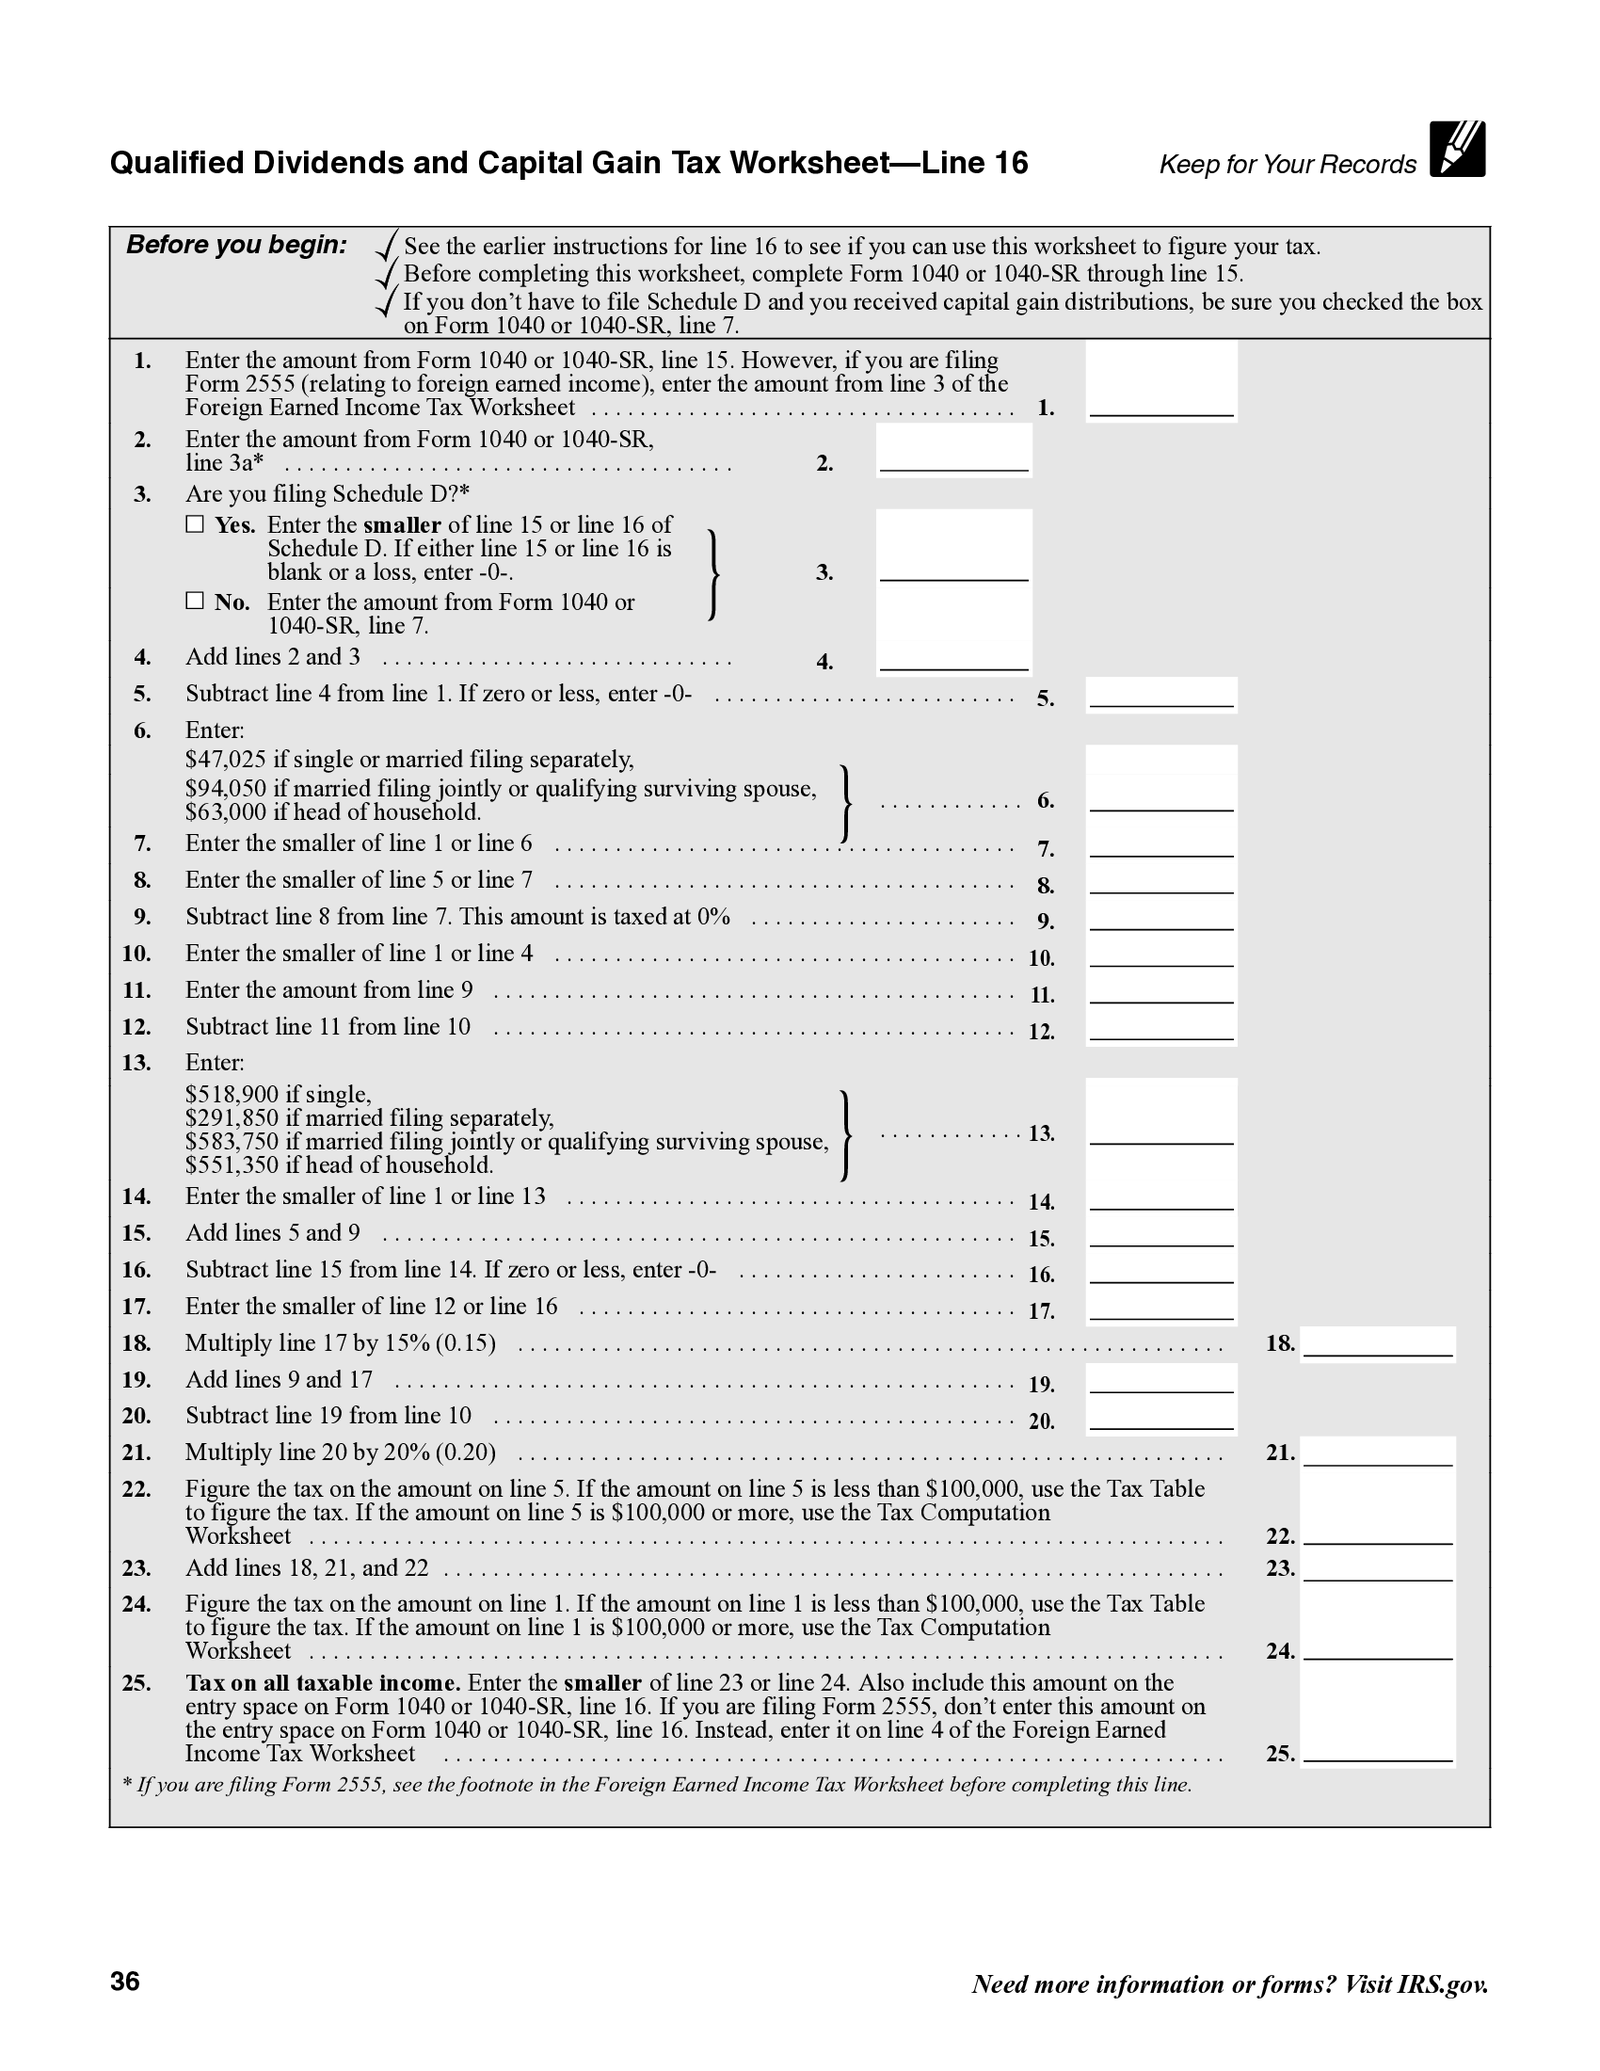
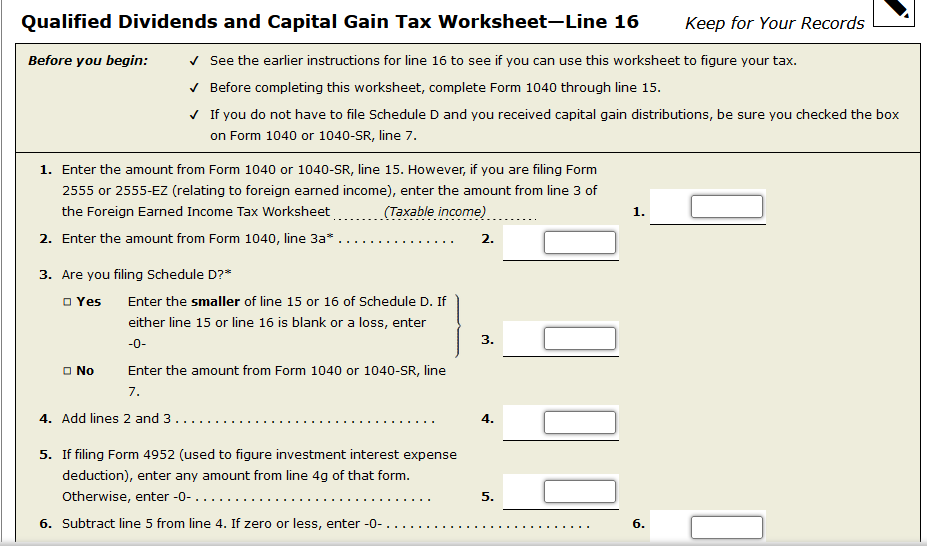
The Qualified Dividends and Capital Gain Tax Worksheet appears in the instructions for Form 1040 when you're dealing with qualified dividends or capital gain distributions. Its job is straightforward: it figures out whether your tax liability changes if you apply the preferential capital gains rates instead of your ordinary income tax brackets. Most people who see it for the first time have no idea when they actually need to use it versus just filling in the regular Tax and Credits section directly. I deal with this worksheet regularly. The triggering condition is simple enough: your Form 1040 shows qualified dividends on line 3b or capital gain distributions on Schedule D, line 13. If those boxes are empty, you skip the worksheet entirely and go straight to the main tax computation. That catches a surprising number of people off guard because they see "capital gain" somewhere on their returns and assume the worksheet applies. Here is how it actually works in practice. You start by pulling three numbers: your taxable income from line 15 of Form 1040, your total qualified dividends from line 3b, and your net capital gain from Schedule D if you have one. The worksheet then calculates a modified taxable income by subtracting those preferentially taxed amounts. You compute tax at the ordinary rates on the reduced amount, add the tax at the capital gains rates on the preference amounts, and arrive at your total tax. If that total is lower than what you would get using only the ordinary brackets, you use the worksheet result. If it is higher, you fall back to the regular computation.
The one edge case that always causes problems involves AMT. If you have the Alternative Minimum Tax to worry about, the standard Qualified Dividends and Capital Gain Tax Worksheet does not handle it. I had a situation last year where a client had both qualified dividends and AMT preferences from ISOs. Running the regular worksheet gave a number that looked right, but when I ran the AMT side calculation, the difference was over four thousand dollars. The workaround is to use the Qualified Dividends and Capital Gain Tax Worksheet (Alternative Minimum Tax) instead, which is a separate worksheet in the Form 6251 instructions. Most preparers miss this distinction. I keep a note in my workflow file now that flags any return with both Schedule D and Form 6251 so this never slips through again. Another thing nobody tells you about the worksheet: it assumes all your qualified dividends are taxed at the same rate. That is not true if you have a mix of 0%, 15%, and 20% bracket situations within the same return. The worksheet handles this by layering the income, but the ordering matters. The 0% bracket gets filled first, then 15%, then 20%. If you have small-amount capital losses that offset gains, the net effect can shift which bracket your dividends land in, and the worksheet recalculates accordingly. I once spent an afternoon tracking down why two tax software packages produced different results on a return with roughly $47,000 in qualified dividends and a $3,200 short-term loss sitting on Schedule D. The discrepancy came down to one program incorrectly applying the loss against the qualified dividends before doing the bracket layering. The other got it right by keeping them separate until the final aggregation step. There is a limitation worth noting. This worksheet only applies when you are filing Form 1040. If you are on Form 1040-SR, the equivalent worksheet exists but has slightly different line references. If you are filing Form 1040-NR or using Form 1040-SS, you do not use this worksheet at all. And if your qualified dividends exceed your taxable income, which sounds impossible but happens more often than you would think with large deduction carryforwards, the worksheet produces a negative preference amount and you need to handle that in the final line rather than ignoring it.
For most people, the practical takeaway is to check your forms first, not jump into the worksheet blindly. If line 3b on your Form 1040 is zero and Schedule D line 13 is zero, you are done. If either is nonzero, pull up the worksheet and follow it line by line. Do not skip the AMT check. Do not assume the software did it correctly if your refund feels off by a couple hundred dollars. Verify the bracket layering. The worksheet takes about eight minutes to complete once you know what you are looking for, and it prevents a much larger headache when the IRS notices a mismatch on the back end.
Get the Full Details