Working Through the 2021 Qualified Dividends and Capital Gain Tax Worksheet
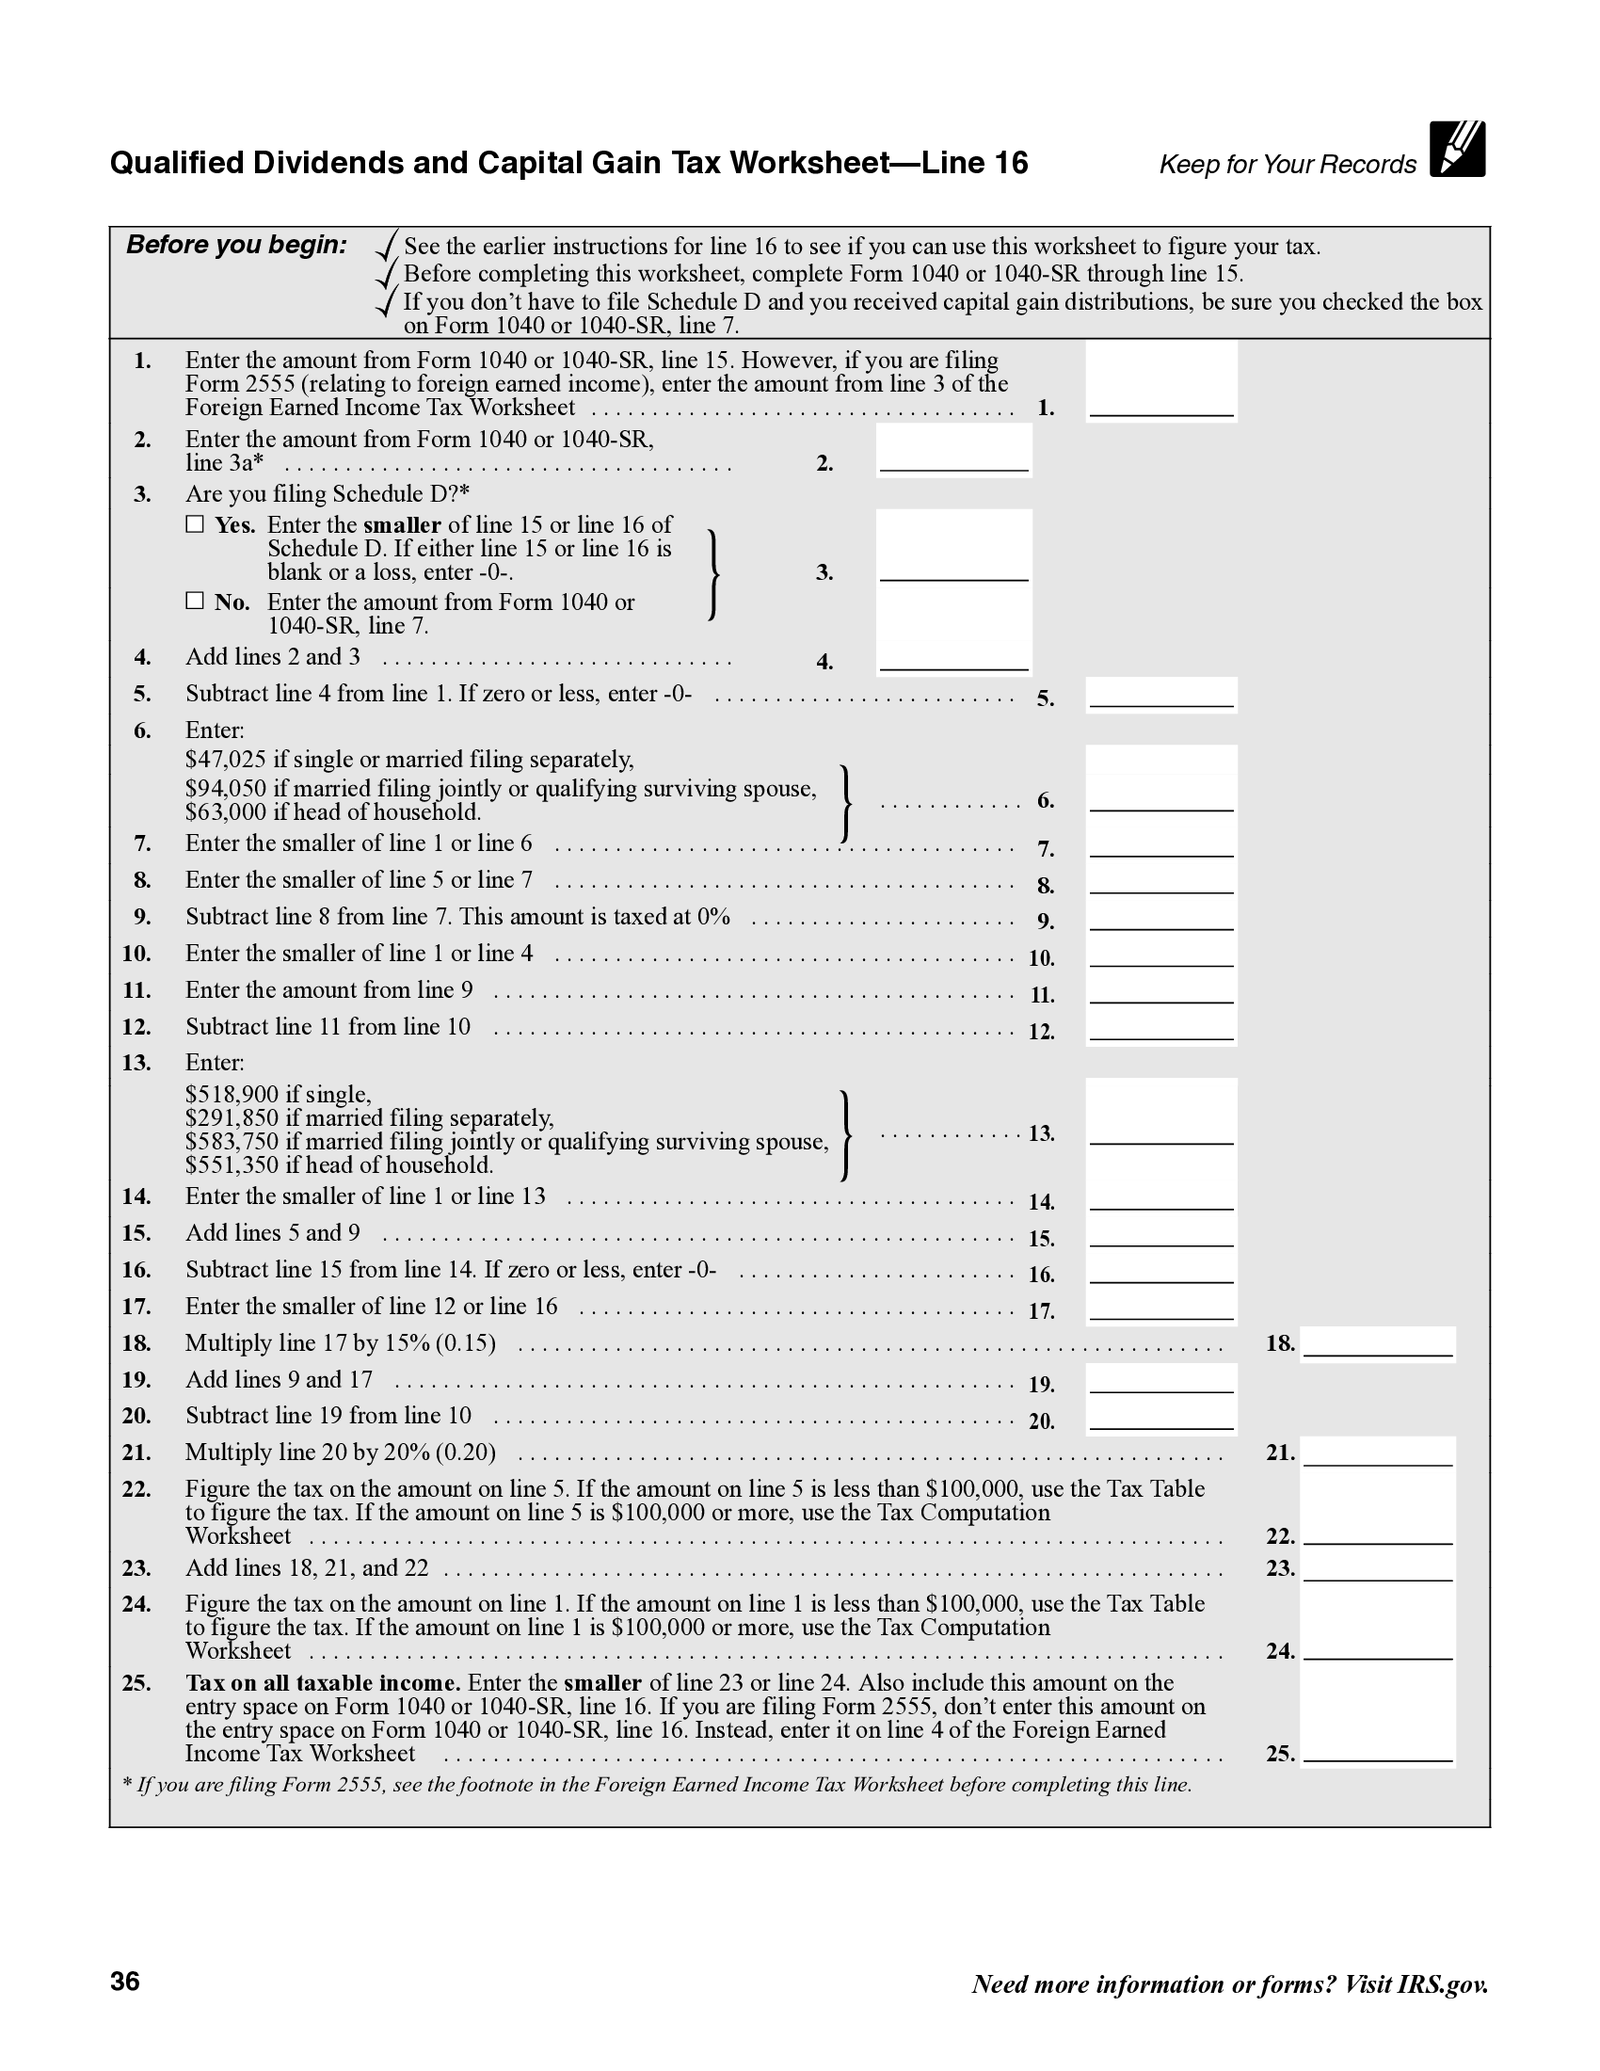
I've sat through enough tax season horror stories to know that when people panic over the Qualified Dividends And Capital Gain Tax Worksheet Line 16 2021, it's usually because they don't trust their own numbers. The worksheet itself isn't difficult, but a single misstep — wrong line on your 1040, missing a form, mixing up types of gains — cascades into a mess that takes an hour to untangle. Here's how to actually use it without second-guessing yourself. First, grab the current version from irs.gov. Search for "2021 Qualified Dividends and Capital Gain Tax Worksheet" directly. The PDF is standalone. It doesn't come pre-filled inside the 1040 instructions. Download it, print it, or load it into a PDF editor. Do not rely on tax software output alone if you want to verify the math yourself. The worksheet splits your taxable income into two buckets: ordinary income and income taxed at preferential rates. That's it in plain terms. The preferential bucket includes qualified dividends, collectibles gain, unrecaptured Section 1250 gain, and Section 1202 gain. If your situation only involves qualified dividends and long-term capital gains from stocks, you're dealing with the simpler version of this worksheet. The more exotic items push you into the "Worksheet B" branch, which adds layers.
Here's the basic flow. You start with your taxable income from Line 15 of your 2021 Form 1040. Subtract your qualified dividends and net capital gain. What's left is ordinary income. You calculate tax on the ordinary portion using the regular tax brackets. Then you calculate tax on the preferential portion using the 0/15/20% capital gains rates. Add them together. That final sum is Line 16 — the total tax before credits and other adjustments. The actual mechanics look like this. Enter your taxable income on line 1 of the worksheet. Enter the total qualified dividends. Enter the total net capital gain. Line 4 is line 1 minus lines 2 and 3 — that's your ordinary taxable income. Compute tax on that using the 2021 tax rate schedules. Then compute tax on the preferential income using the qualified dividends and capital gain rate table or the marginal rate schedule, depending on the version you're working with. Combine the two tax amounts. That combined number goes to Line 16. I ran into a specific problem last year with a client who had both unrecaptured Section 1250 gain and qualified dividends. She assumed the standard worksheet would handle it in one pass. It doesn't. The unrecaptured gain gets taxed at a maximum 25% rate, which sits between the ordinary brackets and the 20% capital gains rate. The worksheet branches at that point. She had to follow the alternate path for Worksheet B, recalculate her ordinary income after isolating the 25% gain, and recompute the bracket interaction. Took me about twenty minutes to redo, but it meant she wasn't short by roughly three thousand dollars. The core issue was that most people don't read the branching instructions and just follow the first path they see.
Another thing nobody warns you about: the interaction between the net capital loss and the preferential income. If you have a net capital loss that exceeds $3,000 of ordinary income, it gets carried forward. But the carryforward amount is treated as a short-term loss in the following year, which can distort the split between ordinary and preferential income in a way that makes the current year's worksheet results feel off. Cross-reference your capital loss carryforward from Schedule D, line 7, against the Worksheet line 3 input. If they don't reconcile, something's double-counted or missing. There's also the issue of state-level recalculation. A few states conform to the federal preferential rates. Some don't. California, for example, taxes all capital gains at ordinary income rates. If you're filing a composite return or a state add-on, the federal Worksheet Line 16 result won't match your state substitution. Budget extra time for that. It's not part of the federal worksheet, but it will show up as a discrepancy during review. The tax rate table you use matters. For 2021, the qualified dividends and capital gain tax rate table applies if your taxable income is below certain thresholds. Above those thresholds, the rate schedule method kicks in. The threshold for the table in 2021 is generally tied to the top of the 15% capital gains bracket: $78,750 for single filers, $157,500 for married filing jointly. If your income sits near that line, small changes in deductions can flip you between methods and shift the result by a few hundred dollars. Check both paths if you're within a thousand dollars of the cutoff. It saves the back-and-forth later.
Get the Full Details

One practical tip: work through the worksheet in pencil or a reversible digital annotation layer. I've seen people transfer an intermediate number directly into Line 16 without tracking which bracket the ordinary income landed in. When the final number looked wrong, they couldn't trace the error because there was no visible audit trail. Keep a copy of each line visible alongside the 1040. Match every line number to its source on your actual return. If you want the raw document, go to irs.gov and search the 2021 Form 1040 instructions. The Qualified Dividends and Capital Gain Tax Worksheet is Appendix B in those instructions. The PDF is available there. The 2021 versions are archived but still accessible. No purchase required. The main pitfall is assuming the worksheet produces your final tax liability. Line 16 is an intermediate result. You still need to account for the earned income credit, child tax credit, foreign tax credit, and any additional taxes like the net investment income tax or the early withdrawal penalty. If you have a net investment income tax situation — which kicks in at $200,000 for joint filers — the worksheet doesn't capture that. You'll file Form 8960 separately. The tax from that form gets added to Line 16 on your 1040, but it's not part of the worksheet itself. That's a common source of underpayment.
Also worth noting: passive activity losses can interact with the worksheet in ways that aren't obvious. If you have a suspended passive loss from a prior year and it becomes allowable in 2021, it can reduce your ordinary income and indirectly shift more of your gain into the preferential bucket. The worksheet doesn't flag this. You need to check Form 8582 first, then adjust your Line 4 ordinary income accordingly. Otherwise the tax computation is structurally wrong, even though the numbers look clean. For most people with straightforward qualified dividends and long-term stock gains, the worksheet will resolve in under ten minutes. The edge cases — 25% gain, cross-state issues, NIIT, passive losses — are where people lose hours. Know your scenario before you start filling it out. It determines which branch you follow and how much verification you actually need.