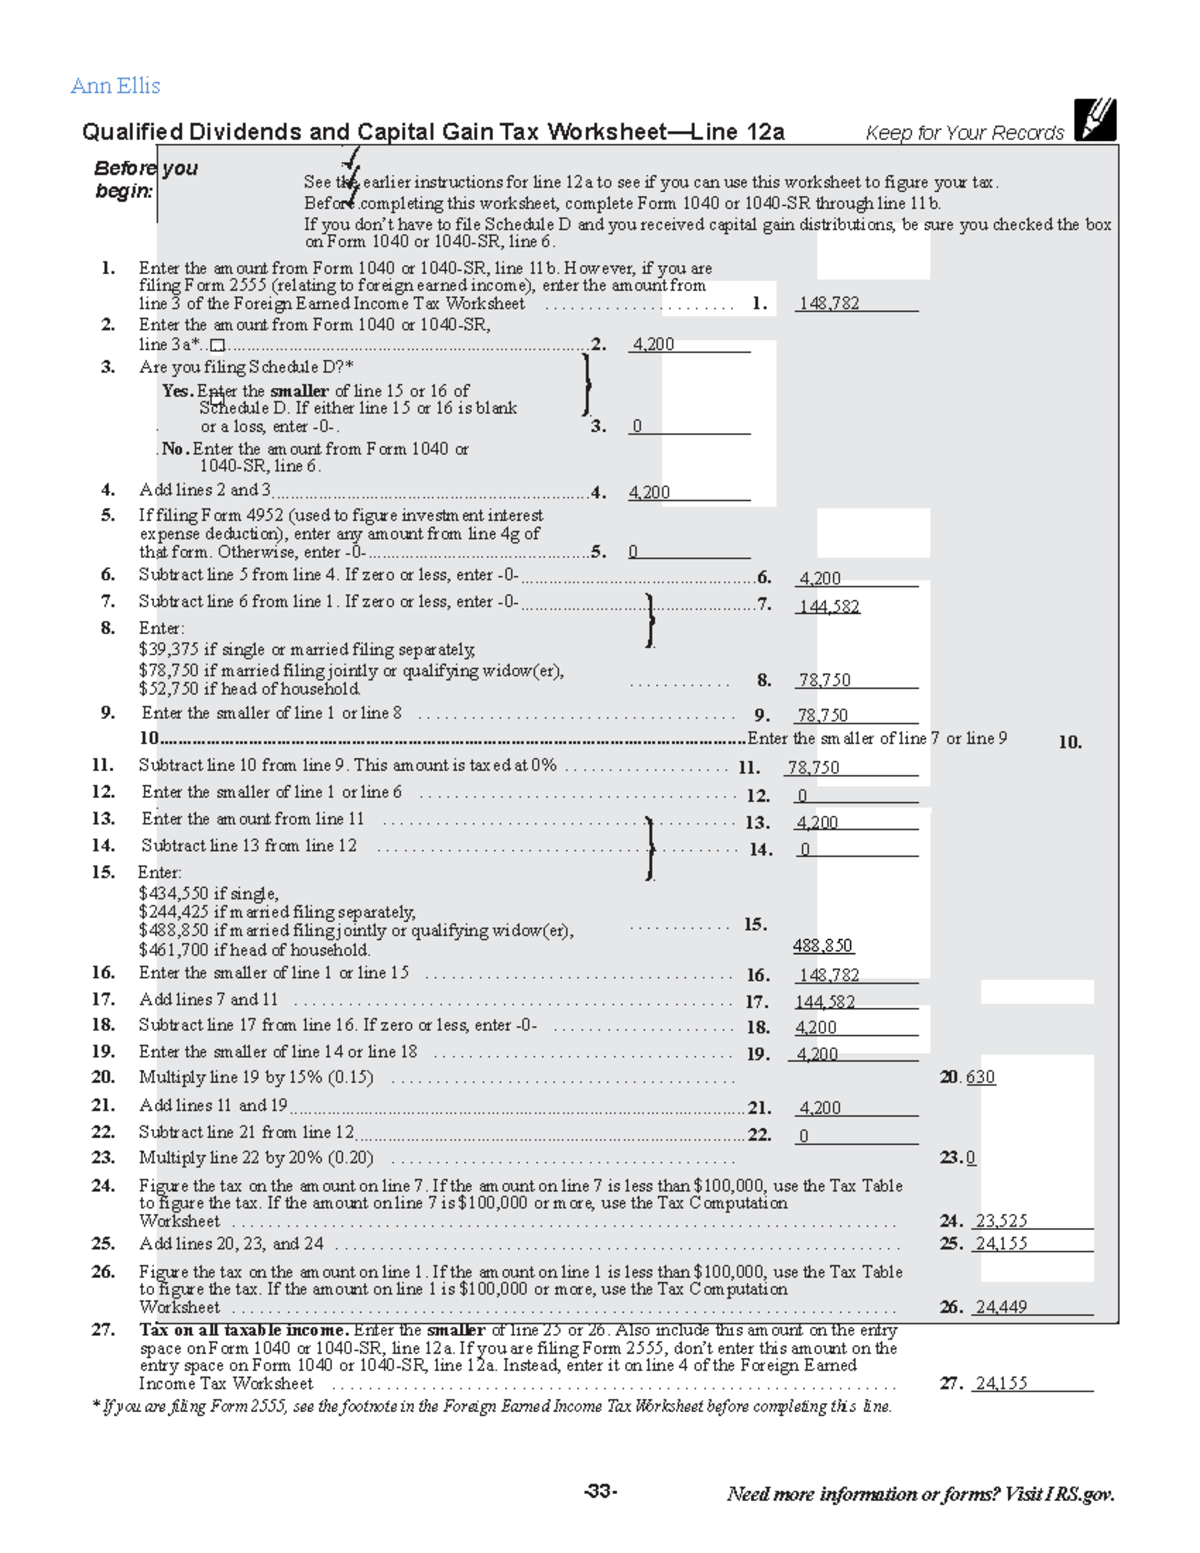
Working Through the Qualified Dividends And Capital Gains Worksheet
The Qualified Dividends And Capital Gains Worksheet is one of those things that trips people up without much reason. It is only six or seven lines long depending on the tax year and how your situation looks, but there are enough conditional branches that you can easily go down the wrong path. I am going to walk through this line by line, and I want to focus on Line 16 specifically because that is where most people make their mistake. Line 16 is asking you to enter the smaller of two numbers. On the current version of the worksheet, line 14 is your taxable capital gain or qualified dividend amount after all the netting and phase-in calculations. Line 15 is your taxable income minus any adjustments or exemptions that push your total below certain thresholds. Line 16 takes whichever of those two values is lower and carries it forward. That seems straightforward until you realize both numbers require work from earlier lines, and if either of them is wrong, line 16 is automatically wrong too. I dealt with a situation a few years back where a client had net capital loss carryovers from three years ago. The losses were already reflected on Schedule D, but they had not been pulled into the Qualified Dividends and Capital Gains Worksheet correctly. When I recalculated, line 14 came out negative because the carryover exceeded his gains for the year. I entered zero on line 16 since the worksheet instructs you to use zero instead of a negative number. Most tax software would have caught that automatically, but he had prepared this return himself for the first time. It took me about forty minutes to trace where the carryover got lost.
How To Fill Out The Worksheet Step By Step
Start with line 1. That is your taxable income from Form 1040 line 15. If you are looking at an older form, it might be labeled differently, but the number is the same. Move to line 2, which asks for your standard deduction or itemized deductions. This is straightforward if you do not have any special situations like the foreign earned income exclusion or the deduction for self-employment tax that requires its own worksheet first. Line 3 combines the results. You subtract line 2 from line 1. If the result is zero or less, you stop and do not need the worksheet at all. Your tax is just the regular tax calculation. Most people do not realize this shortcut exists and fill out the entire thing anyway. That wastes time and introduces the chance of an arithmetic error where none was needed. Lines 4 through 13 get into the actual qualified dividend and capital gain math. Line 4 is your qualified dividend income reported on Form 1040. Line 5 is your taxable capital gain from Schedule D line 15 or 16, whichever applies. Line 6 is the unrecaptured section 1250 gain. This is a specific type of depreciation recapture that gets taxed at a maximum rate of twenty-five percent instead of the lower capital gains rates. Line 7 is your qualified dividend income plus any Section 642(c) gains. These are rare but show up in estate and trust situations.
Lines 8 through 13 handle the interaction between these different types of income and the various tax brackets. Line 8 takes the smaller of line 5 or line 6. Line 9 subtracts line 8 from line 5. Line 10 is the smaller of line 3 or line 9. Line 11 multiplies line 10 by the appropriate rate depending on your filing status and bracket. Line 12 adds the remaining capital gain amounts. Line 13 multiplies the unrecaptured gain by twenty-five percent. All of this feeds into line 14. Line 14 is your total taxable amount subject to the preferential rates. Line 15 is your taxable income minus the standard or itemized deduction again, essentially confirming you have not double-counted anything. Line 16 is the minimum of those two. This minimum protects you from applying preferential rates to income that has already been taxed at ordinary rates elsewhere in the worksheet.
Get the Full Details

Common Mistakes People Make
The most common error is entering the wrong number on line 15. People grab their total income from Form 1040 without subtracting the standard deduction. This makes line 15 larger than it should be, and if line 14 is smaller, line 16 will incorrectly use the larger line 15 number instead of the correct line 14 number. The tax comes out higher than it should. I see this at least once a month when people send me their returns for a quick review. Another issue is forgetting about the Phase-In Range. The preferential capital gains rates apply differently depending on where your taxable income falls. For 2024, the single filer phase-in range starts at fifty-five thousand dollars and goes to four hundred ninety-six hundred seventy-five dollars. Married filing jointly is double those numbers with an offset at the top. If your income lands in that band, some of your qualified dividends and capital gains get taxed at fifteen percent instead of the zero or twenty percent rates. The worksheet handles this automatically, but you need to make sure Schedule D is completed first and the numbers flow through correctly. Here is something most guides do not mention. If you have both qualified dividends and long-term capital gains, the worksheet netts them together before applying the rate. That means a $10,000 long-term gain and a $3,000 qualified dividend do not get taxed separately. They combine into a single pool. This can push you into a higher bracket than you expect if you only look at the dividend income in isolation. I learned this the hard way when a client thought they were well within the zero percent capital gains bracket based on their dividend income alone. Their total gain income pushed them into the fifteen percent zone.
When The Worksheet Does Not Apply
The Qualified Dividends And Capital Gains Worksheet is not always the right path. If you are filing Form 2555 for foreign earned income, you need a different worksheet. If you have Amtrak State of the Art Pass income, that goes on a separate calculation too. Passive loss limitations can also force you into a different routing. If your Schedule E shows a passive activity loss that is being carried forward, the standard worksheet will not account for it properly. In those cases, the Qualified Dividends and Capital Gain Tax Worksheet from Form 1040 Schedule D becomes the default, which is a simpler version. It skips some of the phase-in calculations and just applies the flat rates. It is less precise but adequate for most simple situations. If your income is above the threshold where the preferential rates phase out anyway, you might as well use the Schedule D worksheet and save yourself the trouble of the longer form.
Final Thoughts
The worksheet itself is not complicated. The complexity comes from making sure every input number is correct before you reach line 16. I usually spend about ten minutes verifying each line individually rather than rushing through. The time investment pays off because a single wrong number early in the worksheet cascades through every subsequent line. If you catch an error on line 4, everything from line 6 onward is contaminated. Print the worksheet, work through it with a calculator or spreadsheet, and verify each line against your source documents. Schedule D, Form 1099-DIV, and your 1040 should all tell the same story. If they do not, stop and figure out why before you proceed. That is usually where the real problem lives, not in the worksheet mechanics themselves.