Working Through the Qualified Dividends Tax Worksheet 2022
Most people skip straight to the tax software boxes because filling out Schedule D and the associated worksheets manually feels like going back to school. But when you have mixed income sources—capital gains, regular dividends, qualified dividends, maybe some rental income—the software isn't always transparent about how it arrived at your final tax liability. Understanding the Qualified Dividends Tax Worksheet 2022 matters when you need to verify the numbers or catch an error before the return is filed. I started dealing with this worksheet seriously after a client sent me a Form 1099-DIV with qualified dividends in box 1b totaling more than their ordinary dividends in box 1a, but also with ordinary dividends reported on a separate Schedule B that didn't tie cleanly to the main return. The automated tool calculated something, but the qualified dividend tax rate wasn't applying correctly because of how the ordinary income interacted with the capital gains brackets. I had to pull up the actual worksheet from the IRS instructions and work through it line by line to figure out where the disconnect was. It took me about twenty minutes manually.What the Qualified Dividends Tax Worksheet 2022 Actually Does
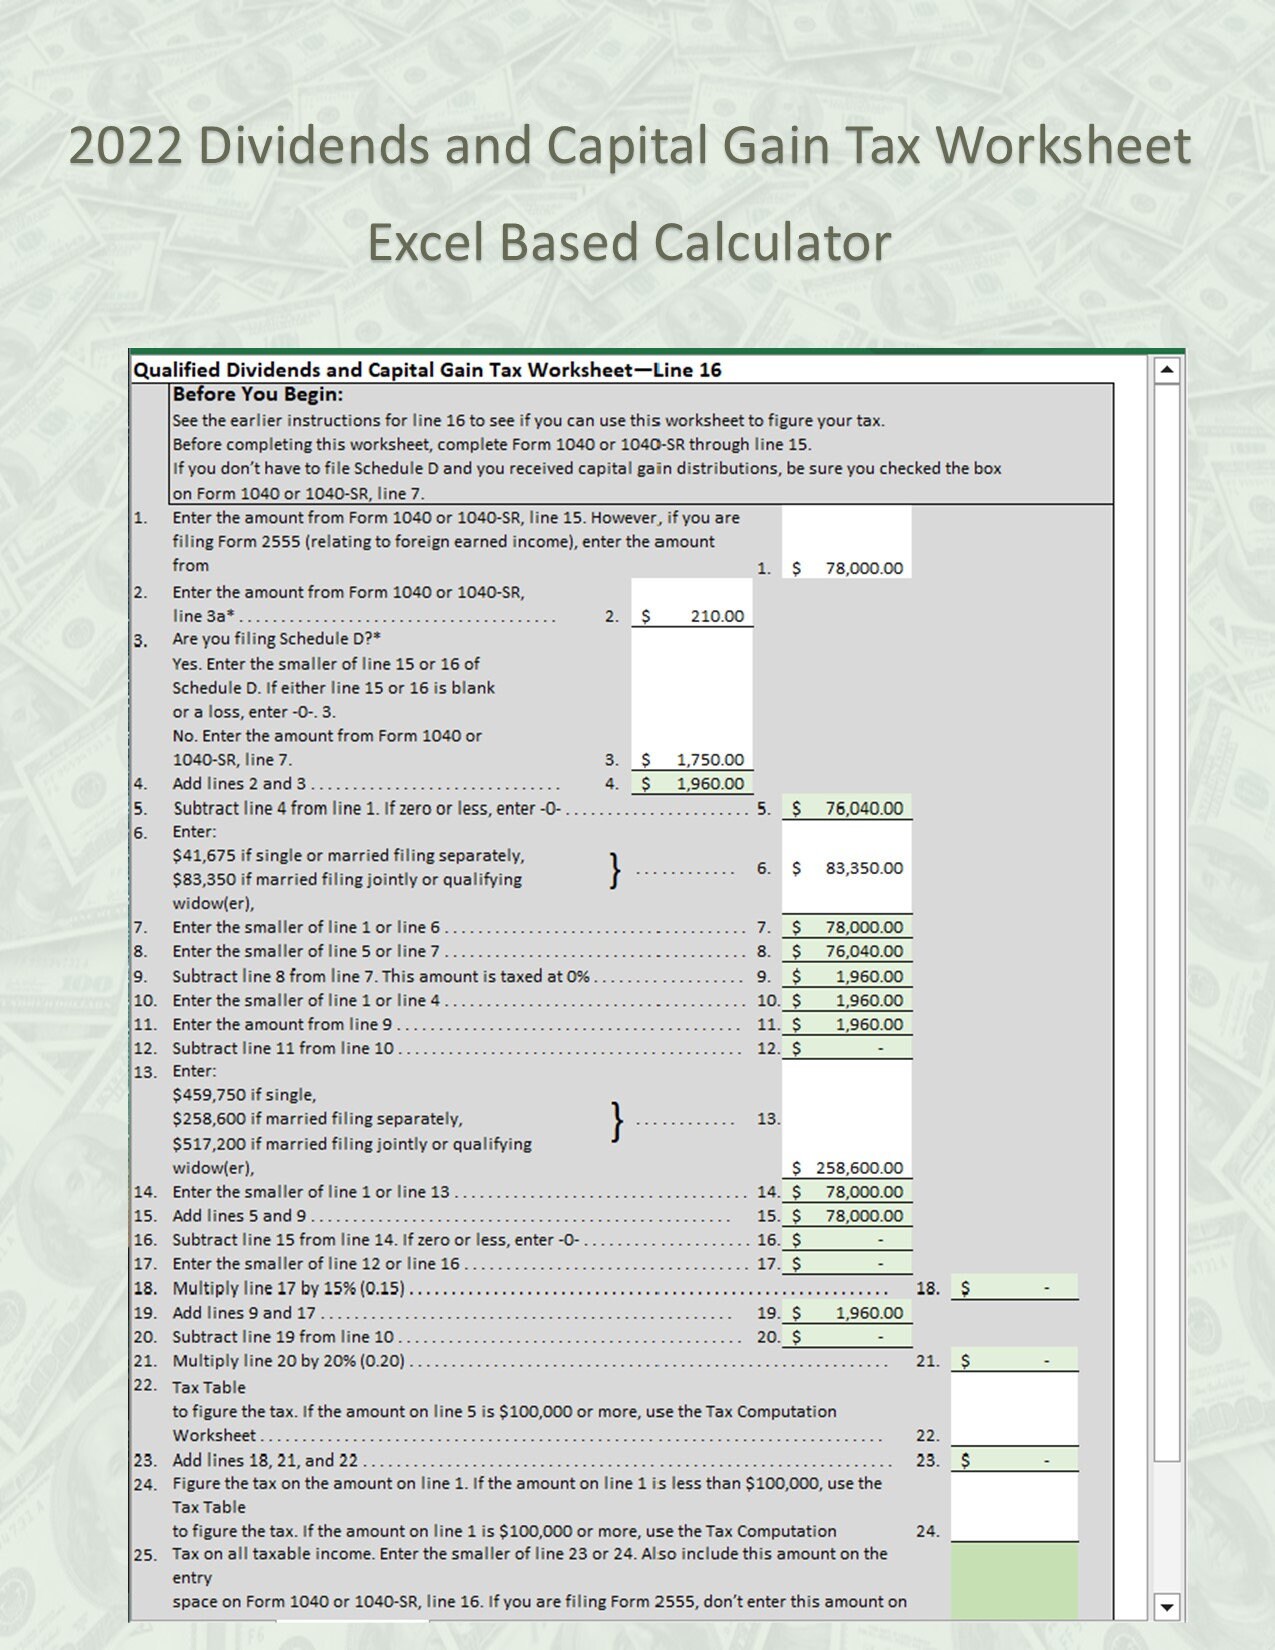
The worksheet exists to determine whether your qualified dividends are taxed at the preferential capital gains rates (0%, 15%, or 20%) or whether they get pushed up into ordinary income taxation due to the interaction with your total taxable income. It lives in the Instructions for Form 1040, specifically for taxpayers who have both qualified dividends and net capital gain reported on Schedule D. It is not a standalone form. You do not mail it with your return. You use it on paper or in a spreadsheet to calculate the correct tax amount, then enter the result into the appropriate line on your 1040. The worksheet appears in different versions depending on your situation—some for Schedule D filers with gain, some for those with losses, and some for cases involving the Net Investment Income Tax. Using the wrong version is one of the most common errors I see in practice.
How to Actually Use It Step by Step
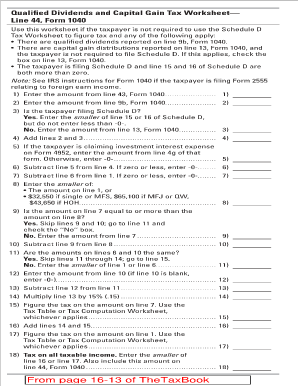
Start by gathering your documents. You need your Form 1099-DIV showing box 1a (ordinary dividends) and box 1b (qualified dividends), your Schedule D if you have capital gains or losses, and your Form 1040 taxable income figure. If you have foreign income or amercan Samoa/Puerto Rico income, that changes things too, but that is an edge case I will get to later. Line 1 of the standard qualified dividends worksheet asks for the amount from your Schedule D, line 16. This is your net capital gain or the qualified dividends amount from line 15 if it is larger. If you do not have a Schedule D, you skip ahead to the simplified version. Line 2 is your taxable income from Form 1040, line 15. Line 3 is the smaller of line 1 or line 2. You then compare that against the capital gains tax brackets for the year. For 2022, the 0% bracket for single filers goes up to $41,675 of taxable income. The 15% bracket runs from $41,676 to $459,750. Above that is 20%. The worksheet walks you through which portion of your qualified dividends falls into each bracket and applies the correct rate. It is arithmetic, not intuition.
One thing that trips people up is that the worksheet does not just tax your qualified dividends at the preferential rate and call it done. It recalculates your total tax by combining ordinary income tax with the preferential tax on the qualified portion. This means your effective tax rate on ordinary income can shift slightly depending on how the brackets interact. It is subtle but real.
Get the Full Details
A Specific Problem I Ran Into
Last year I was reviewing a return where the taxpayer had qualified dividends of about $28,000 and ordinary dividends of $12,000, with a modest capital loss from Schedule D that reduced their net capital gain below the qualified dividend amount. The software I used applied the qualified dividend rate to the full $28,000, but when I walked through the Qualified Dividends Tax Worksheet 2022 manually, I found that the capital loss was effectively reducing the taxable income line in a way that pushed part of the qualified dividends out of the 0% bracket and into the 15% bracket. The difference was about $340 in additional tax. The automated calculation was wrong because it treated the qualified dividends and capital gain lines independently rather than recognizing their interaction through the worksheet logic. The workaround was straightforward: I filled out the worksheet on paper, got the correct tax figure from line 19, and entered that into the 1040 manually rather than letting the software auto-calculate. It is faster to do it once correctly than to spend hours debugging after filing.
Where the Worksheet Breaks Down
The qualified dividends tax worksheet is not designed for every situation. If you have the Alternative Minimum Tax, the worksheet does not account for that. If you have net investment income subject to the 3.8% NIIT, you need a separate calculation. If you are filing as head of household or qualifying widow or widower, the bracket thresholds are different, and using the wrong worksheet version will give you an incorrect result. There is also a separate worksheet for situations where you have unrecaptured section 1250 gain or section 280F gain, which interact with the qualified dividend calculation in non-obvious ways. The biggest practical limitation is that the worksheet assumes your qualified dividends are reported cleanly on a single Form 1099-DIV. When you have multiple brokerage accounts, each issuing their own 1099-DIV, the totals might not reconcile if one broker reports qualified dividends differently than another. I had a case where two brokers reported slightly different qualified dividend amounts for the same holding period, and the IRS would ultimately side with the sum of the forms, but your worksheet calculation could be off by a few hundred dollars if you did not cross-check each 1099 against your actual transaction records. If you have a complex situation involving foreign trusts, ESOP dividends, or dividend recharacterization from a short sale, the standard worksheet will not cover it. In those cases, you need specialized software or a preparer who understands the specific code sections involved.
Common Mistakes to Avoid
One mistake is confusing box 1a with box 1b on your 1099-DIV. Box 1a is your total ordinary dividends. Box 1b is only the portion that qualifies for the preferential rate. Some people assume box 1a is all qualified and end up overstating the benefit. Another mistake is forgetting that qualified dividends still count toward your total taxable income for bracket purposes even though they are taxed at a lower rate. That means your ordinary income tax calculation can be pushed into a higher bracket because of the qualified dividends sitting on top of it. A third mistake is using last year's worksheet for a current year return. The bracket thresholds change annually, and the line numbers sometimes shift slightly between versions. Always confirm you are working from the 2022 instructions, not 2021 or 2023.
When to Use It Versus When to Skip It
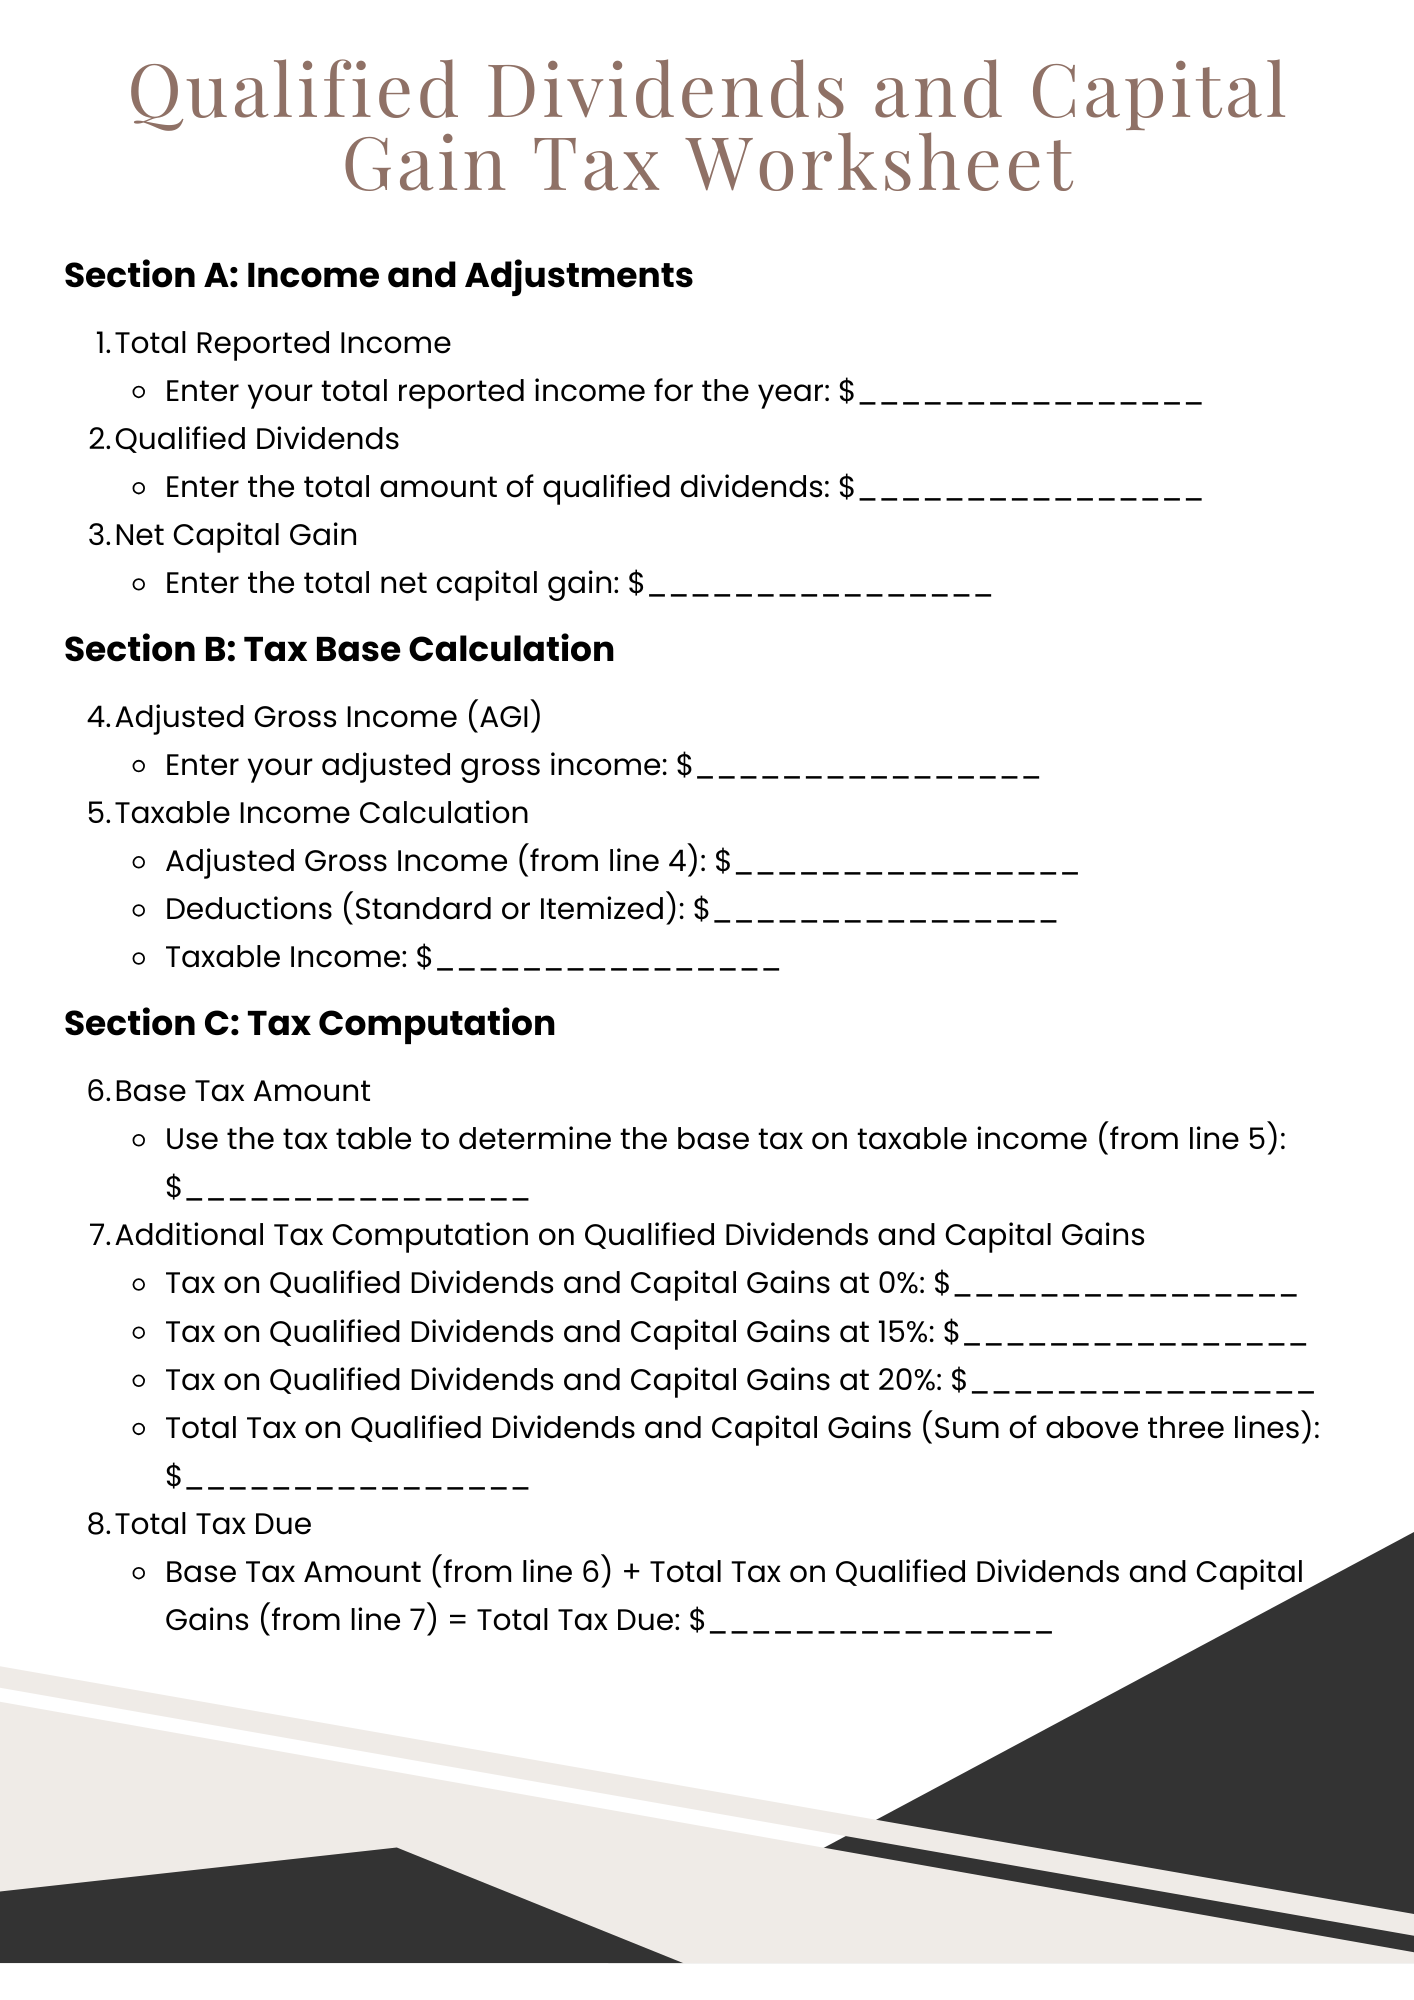
If your only dividend income is qualified dividends and you have no capital gains or losses, you likely do not need the full worksheet. The tax software handles that automatically, and the result will match what the worksheet produces. But if you have any capital gain or loss, any ordinary dividend income, or any complexity beyond a clean 1099-DIV, walking through the Qualified Dividends Tax Worksheet 2022 manually is worth the time. It takes about ten to fifteen minutes for someone who has done it a few times, and it gives you a concrete number to verify against whatever the software produces. You can find the official worksheet in the Instructions for Form 1040 for tax year 2022, available on the IRS website under the publication 17 section or directly from the forms and instructions page. It is a PDF you can print and fill by hand or copy into a spreadsheet for easier calculation. There is no downloadable tool that replaces it, though several tax preparation platforms let you view the worksheet output if you request it during the audit process.