So You're Filling Out Form 8974
I've been wrestling with this form for about six years across a handful of small employers, and the IRS instructions still manage to be frustratingly opaque every time. The core idea is straightforward—you ran a qualifying small business and paid more in Social Security and Medicare than you should have because of the Employee Retention Credit. Now you need to reconcile that. That's what Qualified Small Business Payroll Tax Credit Form 8974 is: the reconciliation document. Let me explain the actual mechanics first, because the order the IRS presents everything in is backwards from how you'd think about it.
The calculation that actually matters
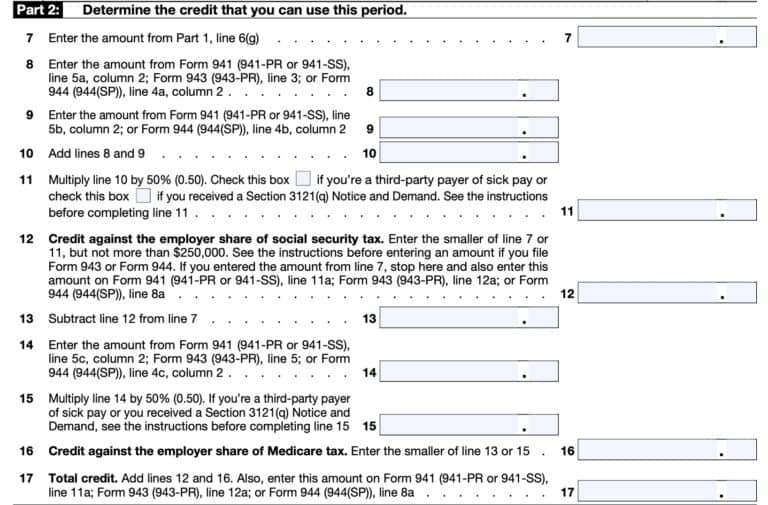
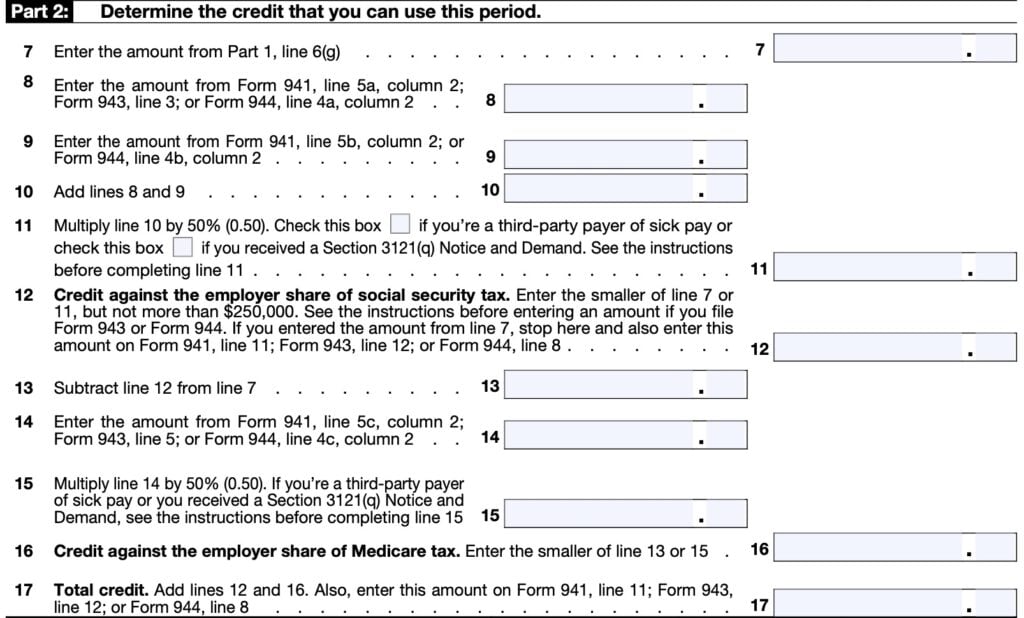
You don't fill out Form 8974 and then figure out your credit. You do the credit work on your quarterly return first—Form 941 with the ERC worksheet—and Form 8974 just verifies the math. That distinction trips people up constantly. Here's what happens in practice: Step one, you determine your qualified wages for each quarter. For a qualified small business, that means gross receipts under $5 million and fewer than 500 employees. The employee count part is deceptively simple—you count them as of any single day in the prior year, not an average. I've seen two businesses mess this up by trying to average their headcount across quarters. It doesn't work that way. Step two, you calculate the credit amount. For 2021, it's 70% of qualified wages per quarter, capped at $7,000 per employee per quarter. That's $28,000 in potential credit per employee if they qualified all four quarters. The employer portion of Social Security tax (6.2%) and Medicare tax (1.45%)—combined 7.65%—is what you're essentially getting back through this mechanism. The credit offsets that liability.
Step three, you report the credit on Form 941. Line 11c on the 2024 version of the form. You reduce your deposit requirement by the amount of the credit you're claiming. This is where it gets weird—your deposit schedule can change mid-year based on the credit. Step four, you file Form 8974 by the due date of your quarterly return, including extensions. If you filed your 941 late, 8974 is late too. They're linked.
Get the Full Details

My own headache with the form
Here's a specific problem I ran into last year that the instructions don't really cover. I had a client with about 40 employees who used a third-party payroll processor that reported wages differently than how they actually tracked qualified wages internally. The processor was reporting on a calendar basis, but my client had some employees on a semi-monthly schedule with wages split across fiscal periods. The issue manifested on line 5 of Form 8974, where you list each employee's qualified wages. The math didn't reconcile between what the 941 showed and what I was putting on the 8974. The discrepancy was roughly $3,200—small in absolute terms but enough to trigger an automatic matching flag from the IRS. Here's what I did: I pulled the raw payroll transaction logs from the processor's source data instead of relying on their summarized reports. The processor's quarterly summary was off because they were including some wages that shouldn't have counted—specifically, tips that exceeded the tip exclusion threshold. Once I stripped those out and recalculated, the 941 and 8974 numbers aligned perfectly. The workaround was essentially auditing the payroll processor's output against the underlying transaction data, which took about three hours for that one client. I now flag this upfront for any client using third-party processors—I ask for the raw export, not the summary, before I even start on the form.
Common pitfalls I keep seeing
The biggest one by far is double-counting wages. You can't claim the same dollars for the ERC on Form 8974 and also use them for the Work Opportunity Tax Credit or the health insurance premium credit. The IRS sees this. They have cross-referencing systems that catch it automatically, and the penalty for the mismatch isn't worth whatever small credit you might salvage. Another thing: the form requires you to list every employee who received qualified wages, including those who received zero credit. I know this feels tedious—it really is—but leaving someone off the list creates a gap in your documentation that will come back to haunt you during an audit. I keep a separate spreadsheet outside the form itself just to track every employee and their wage numbers, then pull from that when filling out 8974. There's also the question of which employees count toward the 500-employee threshold. This is counterintuitive: you count employees regardless of whether they received qualified wages. Part-time, seasonal, contractors—wait, contractors don't count, that's the other side. Independent contractors are not employees. But you count every W-2 employee, full or part time, in your headcount test. This matters because hitting 500 employees changes the qualified wage definition entirely. Under 500, all wages count. Over 500, only wages paid while the employee isn't providing services count. Businesses regularly miss this distinction and apply the wrong rule.
When Form 8974 won't help you
This credit has real limitations that the promotional material around the ERC tends to gloss over. If your business had gross receipts over $5 million in any quarter of 2021, you're out of luck for the qualified small business path. There's no workaround—this is a hard cutoff built into the statute. Some people try to restructure their business to appear smaller, but the IRS looks through that pretty quickly if you've made changes just before the eligibility window. Another limitation: the credit is non-refundable. If your payroll tax liability is less than the credit amount, you don't get the difference back as a check. You can carry forward the excess, but that means next year's liability has to absorb it. For some businesses with very low payroll taxes relative to their qualified wages, this creates a situation where they've technically "earned" a large credit but can't monetize it fully in the year it applies. And here's something most people don't realize—the credit reduction applies at the employer level, not just the employee level. If you're a multiple employer entity with shared services, the employee count and gross receipts tests apply across the whole controlled group. What looks like a small business on paper might fail the test once you include the sister companies.

Practical filing advice
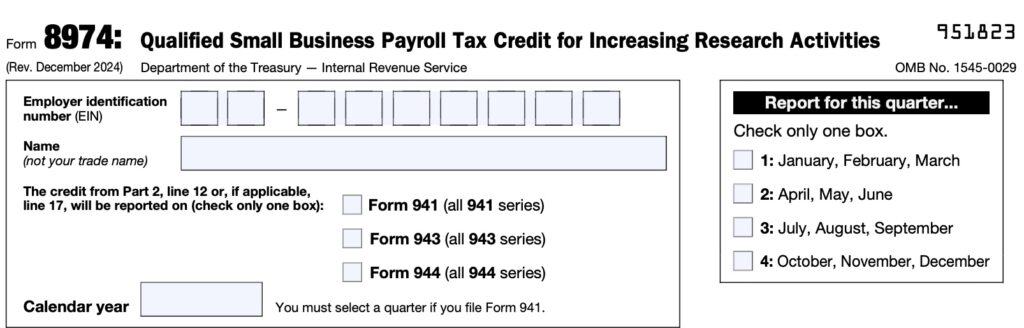
The form itself is three pages and not especially complicated. Download it from irs.gov—search for "Form 8974" and grab the current year's version. Fill it out by hand or through e-file; there's no advantage to one method over the other. Make sure your name, EIN, and quarter information match exactly what's on your 941. Any mismatch there is an easy rejection or, worse, a manual review flag. Retain supporting documentation. I mean real supporting documentation—payroll records, wage calculations, employee lists with dates. The statute of limitations for the ERC runs from the date you file the return claiming the credit, and the IRS has been aggressive about going back three years on these. I recommend keeping records for at least seven years after the filing year, because the extension period adds time you might not expect. If you're unsure about any part of the calculation, consider having a tax professional review the numbers before you file. The cost of professional help—probably $500 to $1,500 depending on complexity—is small compared to the penalty if the IRS disallows the credit later. And they have been disallowing these at a meaningful rate, particularly where the qualified wage documentation is thin.
The deadline is April 15th for the first quarter, July 15th for the second, October 15th for the third, and January 15th for the fourth—each matching your 941 due date. Extensions on your return extend the 8974 deadline too, but only if you file the right extension form first.