Why Most QoE Reports Miss The Point
Most people treat Quality Of Earnings analysis as a checklist exercise. Adjust EBITDA, tick it off, move on. That approach works fine when you're dealing with a clean service business with straightforward revenue recognition. It breaks down fast in anything with inventory, long-term contracts, or cross-subsidized product lines. The real skill isn't in applying standard adjustments. It's in knowing which adjustments are going to be contested and why. I've spent years digging through revenue schedules and operating statements for M&A transactions. The difference between a useful QoE and a decorative one usually comes down to how much time you spend on working capital normalization versus how much you fiddle with one-time expenses. Most analysts over-index on the latter because it's easier to defend in writing. Working capital normalization is where deals actually go wrong.
What Quality Of Earnings And Earnings Management Actually Look Like In Practice
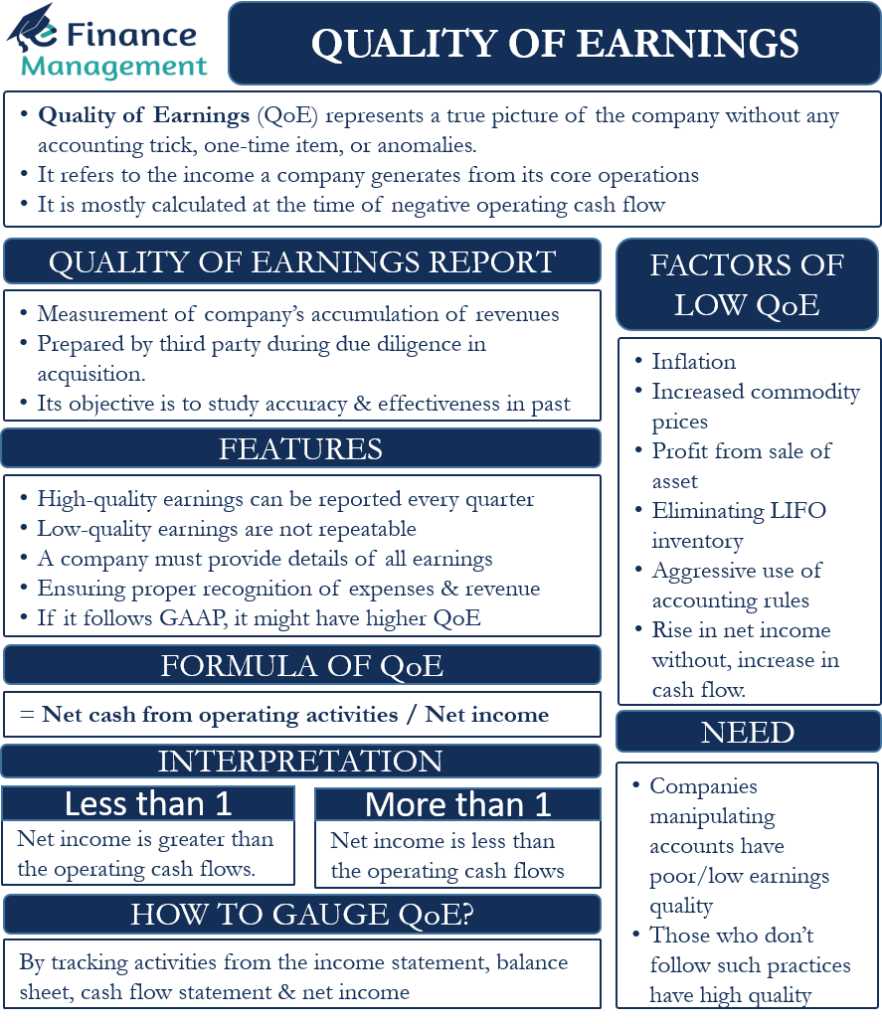
Earnings management isn't always fraud. Sometimes it's just a company optimizing when expenses get recognized or accelerating revenue into a quarter because that's how their bonus structure works. The line between aggressive accounting and manipulation is thinner than most deal teams want to admit. A common red flag I see repeatedly is revenue recognition shifted from cash to accrual without adjusting the collection risk. If a company records all invoiced revenue regardless of whether those invoices are collection-ready, that's earnings management whether the CFO intends it as manipulation or not. The quality of earnings itself refers to how sustainable and predictable reported earnings actually are. It's not a single metric. It's a composite judgment based on cash conversion, recurrence of adjustments, revenue concentration, margin stability, and the consistency of accounting policies over time. When I see a company with EBITDA margins expanding while operating cash flow stays flat or declines, I assume something is being managed unless proven otherwise. Normalize before you conclude. The first thing I do with any target company is strip out everything labeled non-recurring, then test whether those items actually recur. In one engagement, a manufacturer had $2.4 million in what they called restructuring charges spread across three quarters. Digging into the detail, those were mostly reclassifications of permanent headcount into temporary staffing and vice versa. The underlying labor cost never changed. The EBITDA improved by $2.4 million on paper but stayed identical in reality. That adjustment alone flipped the deal from attractive to uninvestable.
The Core Framework Without The Fluff
Start with the income statement and the cash flow statement side by side. Calculate cash conversion by dividing operating cash flow by net income over at least two full fiscal years. A ratio below 0.8 consistently suggests earnings are being managed upward through accruals. Above 1.2 over multiple periods suggests the opposite, sometimes conservative reserve building. Move to revenue quality. Check concentration. If more than 30 percent of revenue comes from a single customer or a single contract type, the quality drops regardless of how clean the rest of the P&L looks. Next, examine the sales pipeline relative to recognized revenue. Deferred revenue turning over too slowly can indicate revenue is being pulled forward. An abnormally fast turnover can signal aggressive recognition or even channel stuffing. For adjustments, categorize them into three buckets: recurring operating items that should be normalized, genuinely one-time events that should be excluded, and items that look one-time but are structurally embedded in the business model. The third category is where most valuations go off track. A logistics company's fleet maintenance costs might look lumpy and discretionary, but if the business runs aging equipment and defers replacement, those maintenance costs are structural. Removing them inflates EBITDA artificially.
Get the Full Details
A Real Edge Case That Almost Got Missed
Early in my career I worked on a SaaS acquisition where the target reported strong recurring revenue with a 95 percent retention rate on paper. The QoE adjustment schedule looked pristine. Gross margins were expanding. Churn was minimal. Everything checked out until I dug into the gross margin by customer cohort instead of at the aggregate level. The expansion margin was entirely driven by a shift in mix toward enterprise clients with lower support costs, while the SMB segment was actually burning cash on a per-account basis. The aggregate numbers told a story that didn't exist at the segment level. The workaround was straightforward but tedious. I pulled individual customer-level profitability data spanning four quarters and built a cohort analysis that allocated shared support costs based on actual ticket volume per tier. The adjusted EBITDA came in 18 percent lower than the reported figure. The deal price was renegotiated accordingly. Without that granular view, the acquirer would have overpaid by roughly $4 million on a $22 million transaction.
Where This Methodology Falls Apart
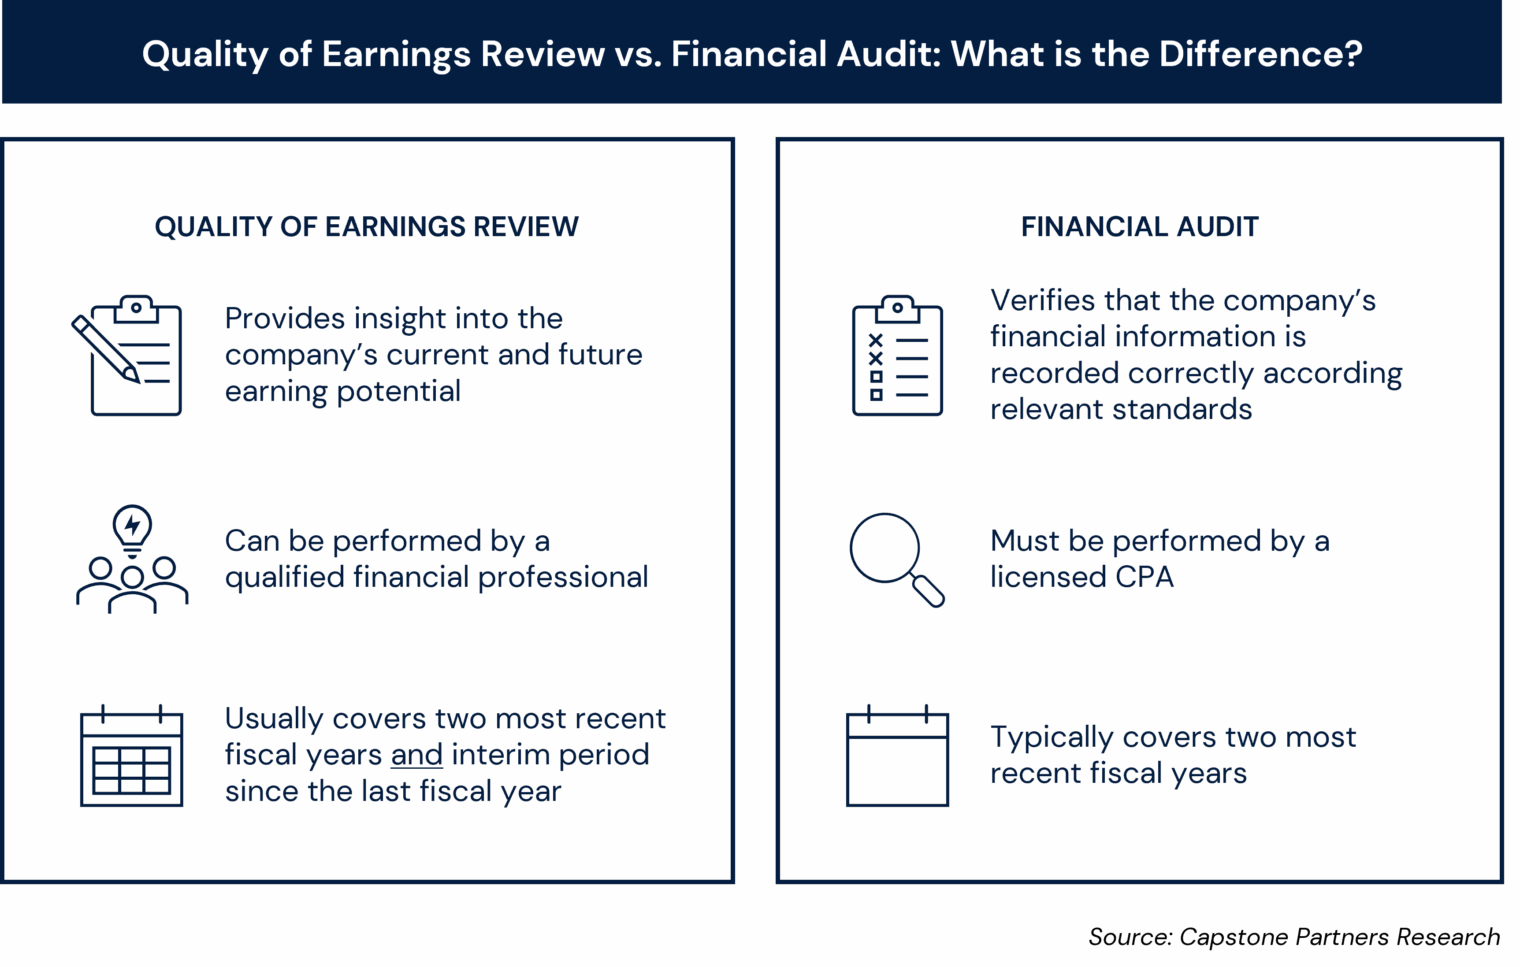
Quality Of Earnings analysis assumes you have access to detailed financial data. In smaller buy-side engagements or competitive auctions with limited data rooms, you're often working with summarized P&Ls and delayed financials. The adjustments become speculative rather than grounded. In those situations, the QoE report becomes more of a directional indicator than a precise tool. It can flag risks but can't quantify them reliably. Another hard limitation: QoE analysis is backward-looking by nature. It can't predict future earnings management unless historical patterns are extremely consistent. A company that learned to manage earnings effectively once has no obligation to keep doing it the same way. Accounting policies change. New CFOs bring different instincts. The 2023 adjustment patterns might tell you nothing about 2025. If you need forward-looking earnings quality, supplement the QoE with scenario-based sensitivity modeling and management interview probing around specific line items. Don't rely on the adjustment schedule alone to give you confidence in future performance. The adjustment schedule tells you what happened. It doesn't reliably tell you what will happen next.
Practical Takeaways For Deal Teams
Don't accept management's definition of non-recurring without testing it against historical patterns. Ask for the supporting detail on every adjustment. Request at least three years of data even if the engagement only covers two. Work capital normalization deserves more time than almost every other line item in the report. Cash conversion ratios should be tracked quarterly, not annually, to catch timing manipulation. And always build a reverse QoE where you try to find ways the numbers could be worse rather than better. It changes how you structure representations and warranties significantly.