Alpha isn't what you think it is
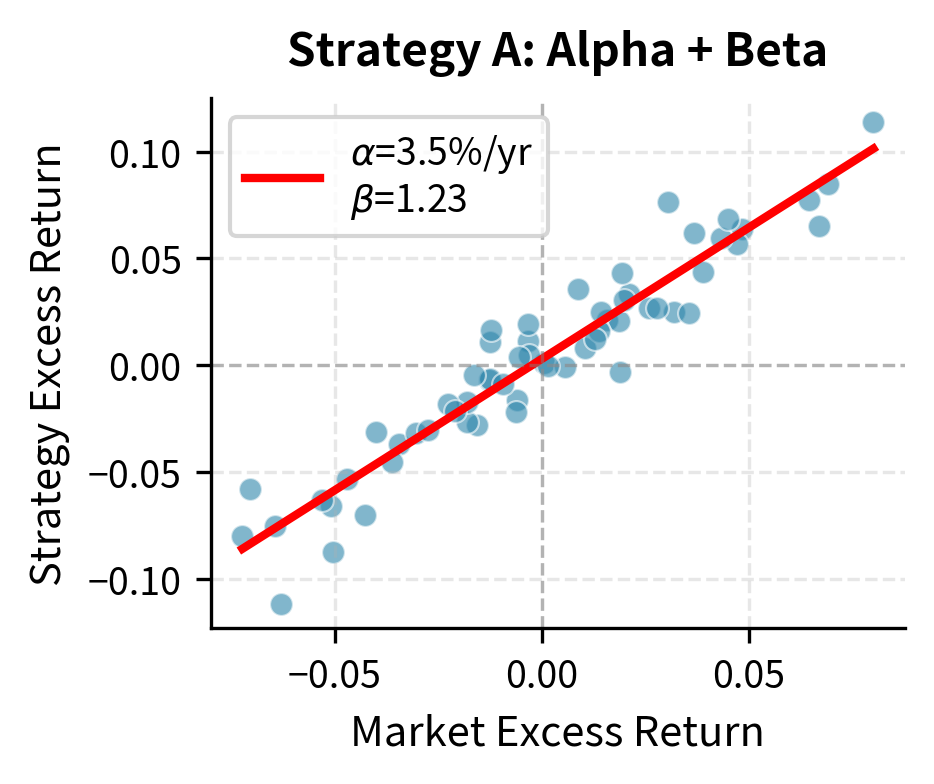
Most people hear "alpha" and picture a magic formula that prints money. It doesn't. Alpha is simply return above your benchmark after you've accounted for the risks you took to get there. The moment you understand that, the whole conversation changes. You stop looking for a Holy Grail and start looking for an edge, which is a much smaller, much harder thing to find. I've spent years watching quant teams chase strategies that look beautiful in a backtest and vanish the day they try to run them live. The difference usually comes down to one thing: understanding what the strategy is actually capturing versus what it's accidentally capturing. You need to know which one before you put a single dollar to work.
The core idea behind Quantitative Strategies For Achieving Alpha
Quantitative strategies for achieving alpha rely on systematic, rules-based methods to identify and exploit mispricings in financial markets. The approach strips out human emotion and relies on statistical signals derived from large datasets. It sounds elegant on paper. It is far messier in practice. Here is the basic architecture: you identify a market anomaly, formulate a hypothesis about why it exists, construct a signal from data, backtest it rigorously, and then deploy it while managing the costs that eat into returns. That last step is where most people fail. They optimize for raw signal strength and forget that every trade costs something. The signal itself can come from anywhere — price and volume data, alternative data like satellite imagery or credit card aggregates, fundamental metrics, macroeconomic indicators, or even sentiment extracted from news feeds. The source matters less than whether the signal has a plausible economic rationale and survives out-of-sample testing.
How factor construction actually works
Construction is where the real work happens. A factor is not just a formula you paste into a spreadsheet. It requires careful attention to universe selection, rebalancing frequency, weighting methodology, and normalization. Miss any of these details and your backtest becomes fiction. Take momentum. The simplest form is rank-ordering assets by their trailing returns over a lookback window and going long the winners while shorting the losers. That part is trivial. The hard part is deciding whether to use 12-month or 6-month lookbacks, whether to exclude the most recent month due to short-term reversal, how to handle delistings, and what kind of cross-sectional neutralization you need to isolate the effect from broader market movements. I worked on a project where we built a momentum factor using raw price data. The backtest showed impressive results. Then someone pointed out that our dataset included delisted stocks at their final trading prices without accounting for the delisting event. The factor was picking up survivorship bias and the apparent alpha evaporated almost entirely once we corrected for it. That was the most expensive lesson I have ever learned, and it cost exactly zero dollars.
Get the Full Details
Backtesting traps that will destroy your edge
Backtesting is not validation. It is hypothesis generation. There is a critical difference that most people gloss over. A backtest can tell you whether a strategy would have worked historically under certain assumptions. It cannot tell you whether it will work going forward. The market changes. Strategies decay. What worked five years ago may be arbitraged away today. Common pitfalls include lookahead bias, where your model uses information that was not available at the time the signal was generated. This is easier to introduce than you might think. If you normalize a variable using the mean of the entire dataset instead of only the data available up to that point, you have contaminated your results. Survival bias is another classic — ignoring the stocks that went bankrupt or were delisted gives you an artificially clean picture. Overfitting is the silent killer. You can always find a combination of parameters that produces perfect historical results if you search hard enough. The key is out-of-sample testing. Reserve a portion of your data entirely separate from your optimization process. If the strategy does not hold up on data it has never seen, it has no future.
Transaction cost estimation is where backtests go to die. Slippage, bid-ask spreads, market impact, and commission fees all matter. A strategy that generates a 20 basis point edge per trade but costs 15 basis points to execute is not viable. I once watched a team paper a conference presentation on a mean-reversion strategy that looked phenomenal on paper. When we ran it through a realistic cost model, the net edge dropped to near zero. We stopped the project that week.
Signal aggregation and portfolio construction
A single signal is rarely enough. The robust approach combines multiple uncorrelated signals into a composite framework. The question is how to weight them. Simple equal weighting is actually a defensible starting point. It avoids the illusion of precision that comes from trying to optimize weights based on noisy historical data. If you have ten signals each with an information coefficient of 0.03, combining them can materially improve your overall information ratio. Diversification across signals works the same way it works across assets. Portfolio construction also involves risk management. Factor neutrality is standard practice — you want pure alpha exposure, not unintended bets on size, value, or sector movements that happen to correlate with your signal. This requires constraints during optimization. You minimize tracking error while maximizing expected alpha, subject to neutrality constraints and turnover limits.
Turnover is both a cost driver and a signal decay indicator. High turnover means you are trading frequently, which increases costs and tax liability. It can also signal that your signal is noisy rather than persistent. I have found that strategies with turnover above 200 percent annually tend to underperform their theoretical expectations once costs are included, unless they are specifically designed for high-frequency execution.
What actually separates successful implementations from failures
Data quality is the foundation. Garbage in, garbage out applies universally. I have seen projects fail because the underlying data had missing values that were filled with the previous available observation, creating artificial stickiness in the signal. The fix was straightforward — use proper gap-filling methodology and validate the data pipeline before it touches the model. Implementation shortfalls are real and they are often underestimated. When you place a large order, the market moves against you. The difference between your expected execution price and the actual price is implementation shortfall. In liquid large-cap equities this might be 2 to 5 basis points. In small-cap or emerging market names it can be 20 basis points or more. Your model needs to account for this, not just the bid-ask spread. Regime changes are another practical concern. A value strategy that works in a rising rate environment may perform very differently in a falling rate environment. I encountered a situation where a factor that had been stable for three years suddenly reversed over a six-month period. The factor was not broken — the market regime had shifted. The solution was not to abandon the factor but to add a regime detection component that adjusted the signal weight based on the current environment.
The uncomfortable truths about quantitative alpha
Alpha decays. This is not a possibility, it is a certainty. As more capital flows into a strategy, the edge shrinks. Arbitrage exists precisely because it removes mispricings. The strategies that survive are the ones that adapt or operate in niches where competition is limited. Most public factors are already well understood and heavily traded. The academic literature on value, momentum, quality, and size is vast. Using these factors without modification means you are getting average exposure, not alpha. The edge comes from finding less crowded spaces or combining known factors in novel ways. Alternative data is promising but expensive and access is uneven. Credit card data, web scraping, satellite imagery — these can provide genuine informational advantages. But they require significant infrastructure investment, legal review, and ongoing data acquisition costs. The edge from alternative data also decays faster than traditional data because more firms are accessing similar sources simultaneously.
Machine learning adds power but also complexity. Neural networks and gradient boosting can capture nonlinear relationships that linear models miss. However, they are prone to overfitting, difficult to interpret, and require substantially more data and computational resources. I recommend starting with simpler models and only increasing complexity when simpler approaches clearly underperform.
A realistic workflow for building a strategy
Start with a clear hypothesis grounded in economic intuition. Don't mine data until you find something — that is just (data dredging) dressed up as research. Formulate a reason why an anomaly should exist, then test it. Build your data pipeline with validation at every stage. Check for missing values, outliers, and consistency. Log everything so you can reproduce your results. I keep a version-controlled directory for each project with the raw data, cleaned data, signal calculations, and backtest results all clearly separated. It takes more time upfront but saves days of debugging later. Backtest with realistic assumptions from day one. Include transaction costs, slippage estimates, and constraints that reflect how you would actually trade the strategy. A backtest that ignores costs is not a backtest — it is a fantasy.
Validate out of sample. Split your data into in-sample and out-of-sample periods. Optimize on the first, test on the second. If performance degrades significantly, you have overfitted. Try again with simpler assumptions or a different approach. Run a paper trading phase before committing real capital. This tests your infrastructure, your execution logic, and your psychology. You will find bugs that the backtest never revealed. Paper trading for at least three months is the minimum I would recommend. Deploy with careful scaling. Start small, monitor performance, and increase position sizes only as confidence grows. Even a validated strategy can fail in production due to execution issues, data errors, or unexpected market behavior.

When quantitative strategies don't work
There are conditions where quantitative alpha generation is fundamentally limited. In highly efficient markets with low transaction costs and widespread participation, edges are thin and short-lived. You are competing against firms with better data, faster technology, and more researchers. Accepting this reality is important. Small portfolios face structural disadvantages. Transaction costs represent a larger percentage of total assets when you are deploying less capital. Diversification is harder to achieve. This is not a reason to avoid quantitative methods, but it is a reason to adjust your expectations and focus on strategies that scale well. Strategies that rely on rare events are difficult to validate. If your signal only activates during market crashes, you may only get a handful of observations in a decade of data. Statistical significance is nearly impossible to establish. These strategies can work for large institutions with long track records but are risky for smaller operations.
If your goal is consistent outperformance, consider that a smart beta approach — combining factor exposure with lower-cost passive instruments — may deliver a better risk-adjusted outcome than attempting to generate pure alpha. This is not a concession. It is a recognition that many alpha-seeking strategies cost more than the alpha they produce.
Quantitative Strategies For Achieving Alpha in practice
The strategies that work are the ones built with rigor, deployed with discipline, and monitored with skepticism. They require continuous research, infrastructure investment, and the humility to accept when a strategy stops working. There is no shortcut. The firms that sustain alpha treat it as a competitive advantage that must be earned every single quarter, not a one-time discovery that pays forever. Start small. Focus on one signal, one market, one frequency. Learn the failure modes before they bite you. Build processes that make it easy to test new ideas and discard old ones quickly. The market rewards speed of learning more than speed of trading. The edge is real but it is fragile. It exists in the details — the way you handle missing data, the assumptions you bake into your cost model, the constraints you impose on your optimizer. Those details are boring. They are also what separate strategies that work from strategies that look good on paper and lose money in practice.

