Understanding How the Math Actually Works in Practice
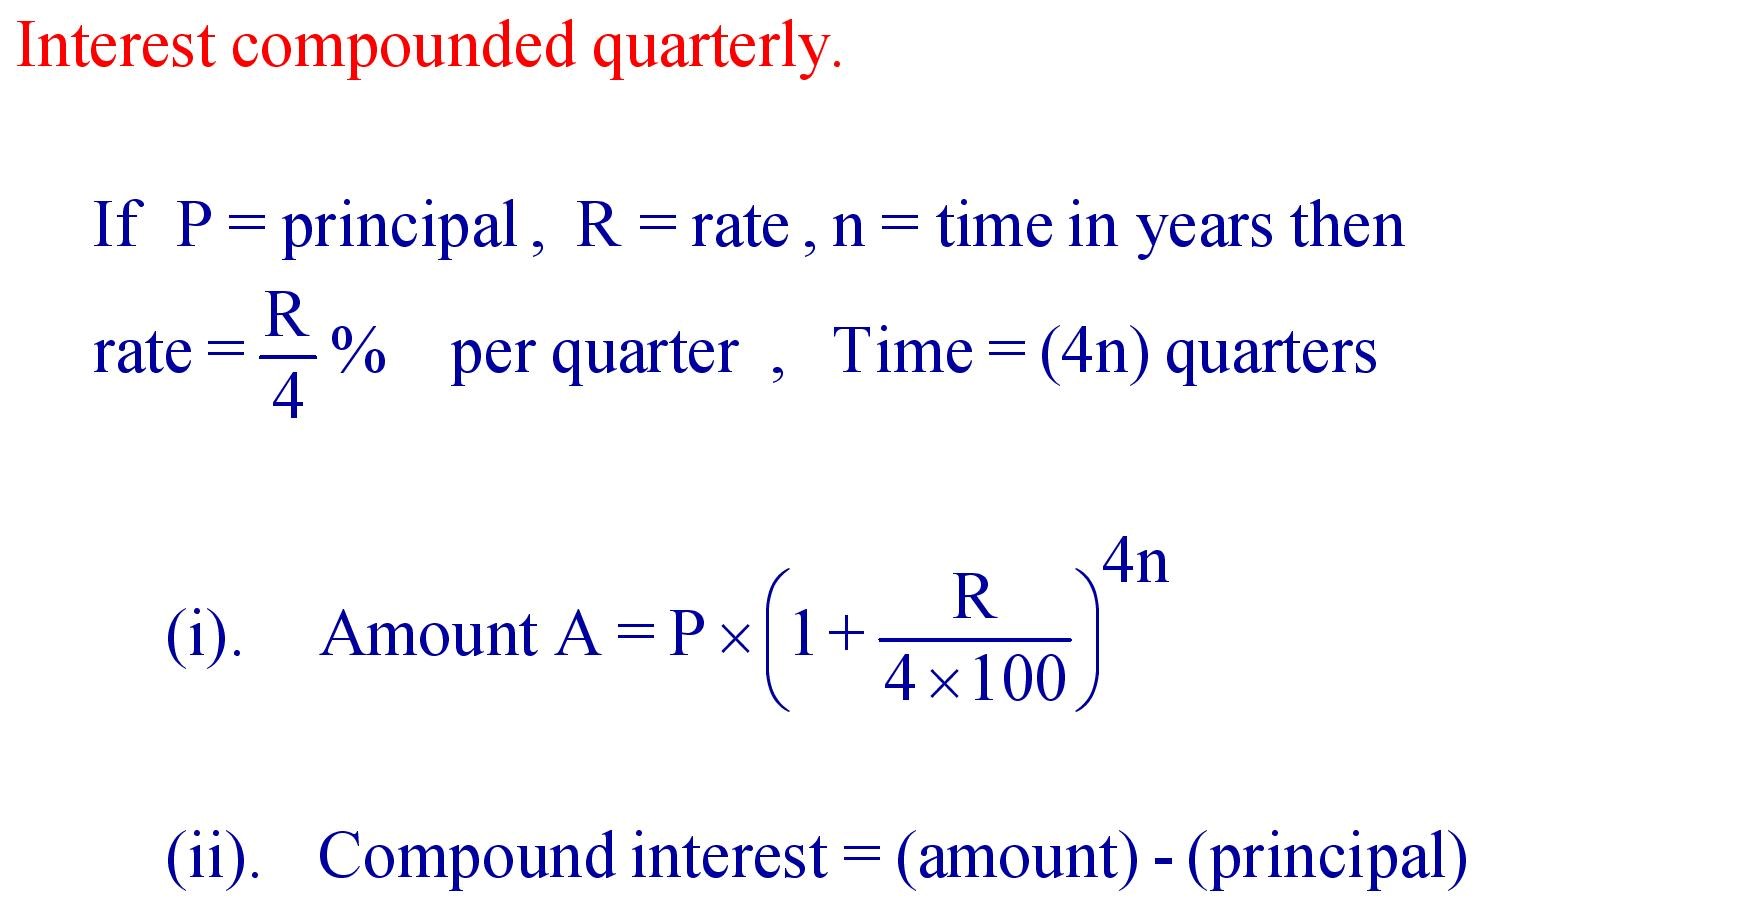
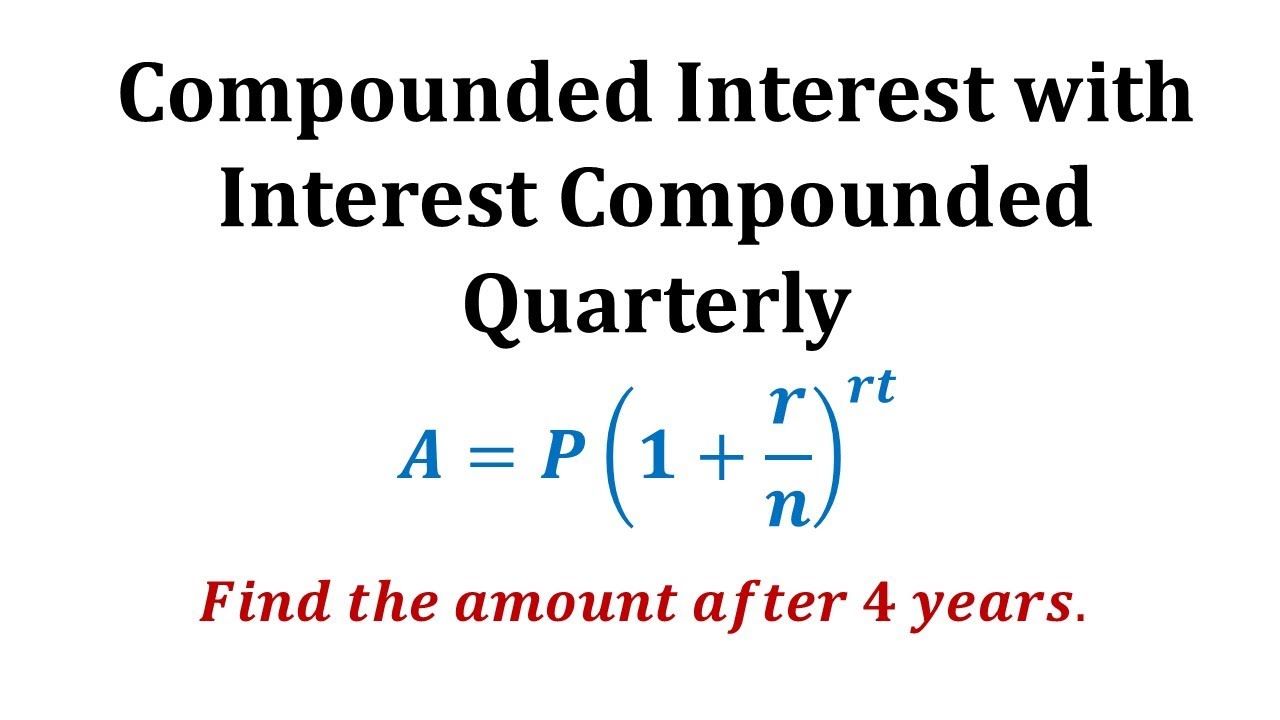
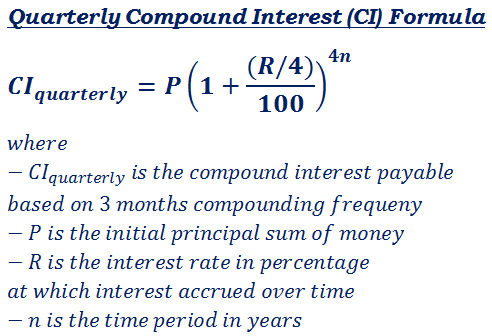
The formula most people need is A = P(1 + r/n)^(nt). A is the future amount. P is your principal. r is the annual rate as a decimal. n is how many times per year interest compounds. t is the number of years. For quarterly compounding, n is always 4. That's it. The rest is just plugging numbers into the right slots and making sure your calculator doesn't choke on order of operations. I spend most of my time building financial models for small commercial lending operations, and quarterly compounding shows up constantly. It sits somewhere between monthly and annual compounding in terms of complexity, which is exactly why it causes so many errors. People either forget to convert the annual rate to a quarterly rate or they mess up the exponent. Both happen about the same frequency in my experience. Let me walk through a quick example. Say you invest $10,000 at 6% annual interest, compounded quarterly, for 3 years. You'd set P to 10000, r to 0.06, n to 4, and t to 3. The quarterly rate becomes 0.06 divided by 4, which is 0.015. You compound that over 4 times per year for 3 years, so the exponent is 12. The calculation is 10000 × (1.015)^12. That gives you roughly $11,956.18. Simple enough on paper.
Here's where things get interesting and where most people don't bother looking. The difference between quarterly and monthly compounding at the same nominal rate is small but measurable. At 6% over 3 years on $10,000, quarterly gives you $11,956.18 while monthly pushes it to $11,966.80. That's about $10.62 difference. Over a 30-year mortgage or a large corporate loan, that gap becomes significant. I've seen borrowers lose thousands just by not comparing compounding frequencies side by side. Another thing nobody mentions often enough: the effective annual rate. When you see a quoted rate of 6% compounded quarterly, the actual return you earn over a full year is higher than 6%. Specifically, it's (1 + 0.06/4)^4 - 1, which works out to about 6.136%. Banks advertise the nominal rate because it looks better. Savvy lenders know the effective rate is what actually matters for comparing products. If you're evaluating two loans with different compounding frequencies, always convert to effective annual rate before making a decision. It takes about 30 seconds in any spreadsheet and prevents expensive mistakes. I ran into a specific problem last year that took me about four hours to track down. We were modeling a series of commercial leases where the quarterly compounding schedule had been set to align with the fiscal quarters of the lessor, not the calendar. The lease started March 15, meaning the first compounding period wasn't a full quarter. Someone had rounded the partial period to a full quarter in the model, which understated the interest accrued in that first period by about 0.3%. On a $2.4 million lease over 10 years, that rounding error accumulated to roughly $18,000 in uncollected interest. The fix was to switch from standard quarterly compounding to day-count fraction compounding for that first partial period, then resume the normal quarterly schedule. Most spreadsheet templates don't account for this edge case out of the box. You have to build it yourself or find a tool that handles irregular periods natively.
There's also a limitation worth being honest about. Quarterly compounding assumes interest is added and begins earning its own interest exactly four times per year. In reality, some financial products use actual/360 or actual/365 day-count conventions that shift the timing slightly. If you're doing rough estimates for personal finance, the standard formula is fine. If you're underwriting a loan or building a pricing model for a financial product, you need to know which day-count convention applies. Using the wrong one won't break your model, but it will make your numbers systematically off, and the drift grows over longer time horizons. For most people reading this, the practical takeaway is straightforward. Use the formula, convert your annual rate to a quarterly rate by dividing by 4, count your total quarters by multiplying years by 4, and plug it in. If you're comparing investment or loan products, calculate the effective annual rate for each and compare those directly. Don't trust the nominal rate alone. And if you're building a model that spans more than five years or involves large principals, double-check that your compounding periods actually match the contract terms. I still do this check on every model now, no matter how simple it looks.
Get the Full Details