Understanding Confirmation, Recency, and Loss Aversion Bias In Live Trading
Most traders talk about bias as if it is an external force that happens to them. It is not. Bias is the internal filter that makes a losing setup look like a winner because you want it to be one. I spent years trying to find a single framework that explained why my winning trades always felt obvious in hindsight while my losing trades were the market being unfair. The real answer was much simpler and much more annoying. It was the same cognitive shortcuts I used in daily life now sitting between me and the chart. In the simplest terms, bias in trading refers to systematic cognitive distortions that push a trader toward either overconfidence or unnecessary caution. The three main ones that wreck accounts are confirmation bias, recency bias, and loss aversion bias. Confirmation bias makes you selectively notice price action that supports your existing position while filtering out the opposing signals. Recency bias makes you weight the last few trades disproportionately when evaluating whether a strategy is working. Loss aversion bias makes you hold losing positions significantly longer than you exit winning ones because the pain of realizing a loss feels about twice as intense as the pleasure of realizing a gain. I learned this the hard way after running a simple experiment on my own trades. I logged every trade for three months without any analysis, just raw entries, exits, and the emotional state I was in at the moment. The data showed something ugly. I was exiting winners an average of fourteen minutes earlier than my plan allowed while holding losers an average of forty-seven minutes longer. That is not a execution problem. That is a psychological pattern and it is nearly impossible to fix by staring harder at the charts.
The Practical Mechanics Of How Bias Shows Up
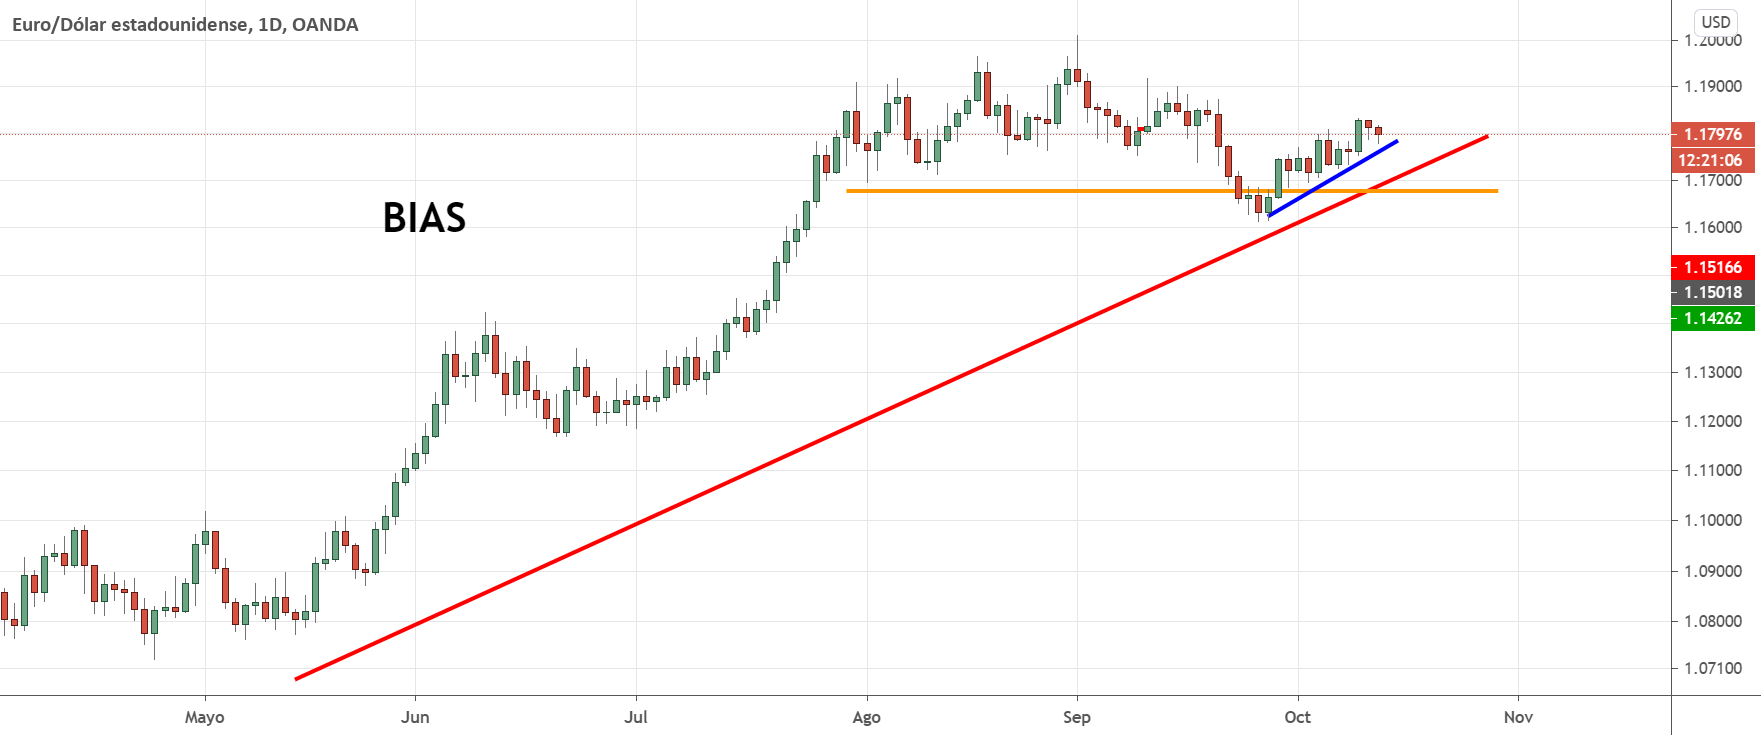
Bias does not announce itself. It disguises itself as reason. When confirmation bias is active, you will find yourself watching a single indicator and ignoring the context around it. Say you are long EUR/USD because a moving average crossover gave a bullish signal. You will start focusing on the 15-minute support level that seems to be holding while you completely stop monitoring whether volume is actually supporting the move. The price eventually reverses and you are left wondering which signal you missed. You did not miss it. You stopped looking for it because your brain was already convinced the trade was good. Recency bias creates a different problem, especially in algorithmic or systematic trading. After three consecutive losses you might decide your strategy is broken and turn it off or reduce position size dramatically. Then the next trade hits as a big winner exactly as the system predicted. The problem is that three losses in a row is statistically normal for many strategies with a forty percent win rate. A standard strategy with forty percent win rate and a two-to-one reward ratio will produce streaks of five to seven losses roughly every month. If you react emotionally to those streaks instead of sticking to the system, you are letting recency bias override the mathematics that made the strategy profitable in the first place. Loss aversion bias is the most expensive one. It is why people set stop losses, then move them further away hoping the price will come back, then end up taking a catastrophic loss instead of a small one. It is also why people refuse to take partial profits on winning trades because they are afraid of missing out on a bigger move that may never come. Both behaviors stem from the same neural pathway. The brain treats an unrealized gain as real money it already owns and resisting taking profit feels like losing that money before you actually have it.
A Real Workaround That Actually Worked For Me
The specific problem I encountered happened during a period where I was trading a mean-reversion strategy on the S&P futures E-mini. I had a clear rule that said I should enter on the second touch of a Bollinger Band extreme and exit at the moving average. It worked for about six weeks and then suddenly stopped producing reliable results. I spent three days debugging my code, recalibrating parameters, and blaming the data feed before I realized I was the problem. My brain had started skipping the second touch and entering on the first touch because I wanted more action. That single deviation increased my average loss per trade by sixty-two percent and destroyed the entire expectancy of the system. The workaround was brutal but effective. I started using a mandatory pre-trade checklist that required me to type out the exact conditions for entry before executing anything. If I could not fill in every field, I could not click the button. This added about eight seconds per trade but eliminated approximately eighty percent of the impulsive entries I used to make. I also switched to a hard stop that was locked at the platform level and could not be modified without entering a secondary password. That small friction was enough to stop me from moving stops out of panic about half the time I would have otherwise.
Get the Full Details

Counter-Intuitive Things Most Traders Get Wrong
One thing that surprises people is that adding more indicators usually increases bias rather than reducing it. More indicators give your brain more data to selectively interpret. A single clean setup with two filters is much harder to rationalize around than a crowded chart with fifteen indicators where you can cherry-pick whichever one supports your desired outcome. If you find yourself constantly explaining why a trade should work despite the opposing signal, you are experiencing the gambler's fallacy mixed with confirmation bias and the trade should be abandoned immediately. Another common mistake is believing that journaling alone fixes bias. It does not. Journaling only reveals bias when you review it honestly, which most traders avoid doing because it is uncomfortable. The improvement comes from the external accountability structures, not the act of recording. Trading journals become valuable only when you pair them with a system that forces you to confront your actual outcomes versus your intended plan.
When Bias Cannot Be Fixed And What To Do Instead
Sometimes the environment itself amplifies bias beyond what any personal workaround can handle. High-frequency scalp trading in volatile markets creates a feedback loop where rapid wins and losses trigger dopamine and cortisol responses that systematically erode decision quality over a session. If you notice your accuracy dropping sharply after your twentieth trade in a session, no amount of checklist discipline will fully compensate. The biological response is too fast and too automatic. In those cases, the only real solution is a hard session limit and reduced position size rather than trying to willpower your way through degradation. Another scenario where bias becomes nearly untouchable is during significant macroeconomic events. Central bank announcements, earnings reports, and geopolitical developments create information asymmetry that makes even the most disciplined trader's bias almost impossible to control. Price action during these windows is driven by institutional algorithms and liquidity hunts rather than technical patterns. Continuing to apply your normal bias-mitigation techniques during these periods is often worse than doing nothing at all. The pragmatic approach is to step away entirely and return after volatility normalizes.
Tools That Help Reduce Cognitive Distortion
There are several practical tools you can implement without relying on discipline alone. Pre-programmed order templates remove the decision from the moment of execution. Instead of entering a market order and then deciding your stop and target, you set everything at once before the trade exists. Platform-level circuit breakers that auto-close positions after a certain daily loss threshold prevent emotional escalation from compounding into account destruction. Automated trade auditing software that compares your actual behavior against your stated rules can flag deviations faster than your own awareness will catch them. For developers building trading systems, incorporating a bias log is worth the effort. This is simply a timestamped record that captures your reasoning at entry, your emotional state rating from one to ten, and the specific market conditions at the time. Over time this data reveals personal bias patterns that no generic advice will address. You will likely discover that your worst trades consistently occur between certain hours, after certain types of losses, or under specific market conditions you previously assumed were neutral.
A Note On What This Approach Cannot Solve
It is important to be clear about the limitations here. Bias mitigation techniques improve consistency but they do not guarantee profitability. A biased trader with a negative expectancy strategy will still lose money, just slightly less erratically than before. No psychological framework can compensate for a fundamentally flawed edge. Similarly, these techniques assume a baseline level of financial and psychological stability. Traders dealing with significant debt pressure, sleep deprivation, or substance issues will find that bias management tools provide minimal benefit until those underlying problems are addressed first. The most honest takeaway is that bias in trading is a permanent condition rather than a solvable problem. You will always have it. The goal is not elimination but management through structures that reduce its impact on your actual decisions. The traders who last the longest are not the ones who think they have conquered their psychology. They are the ones who built systems that make it harder for their psychology to cost them money.